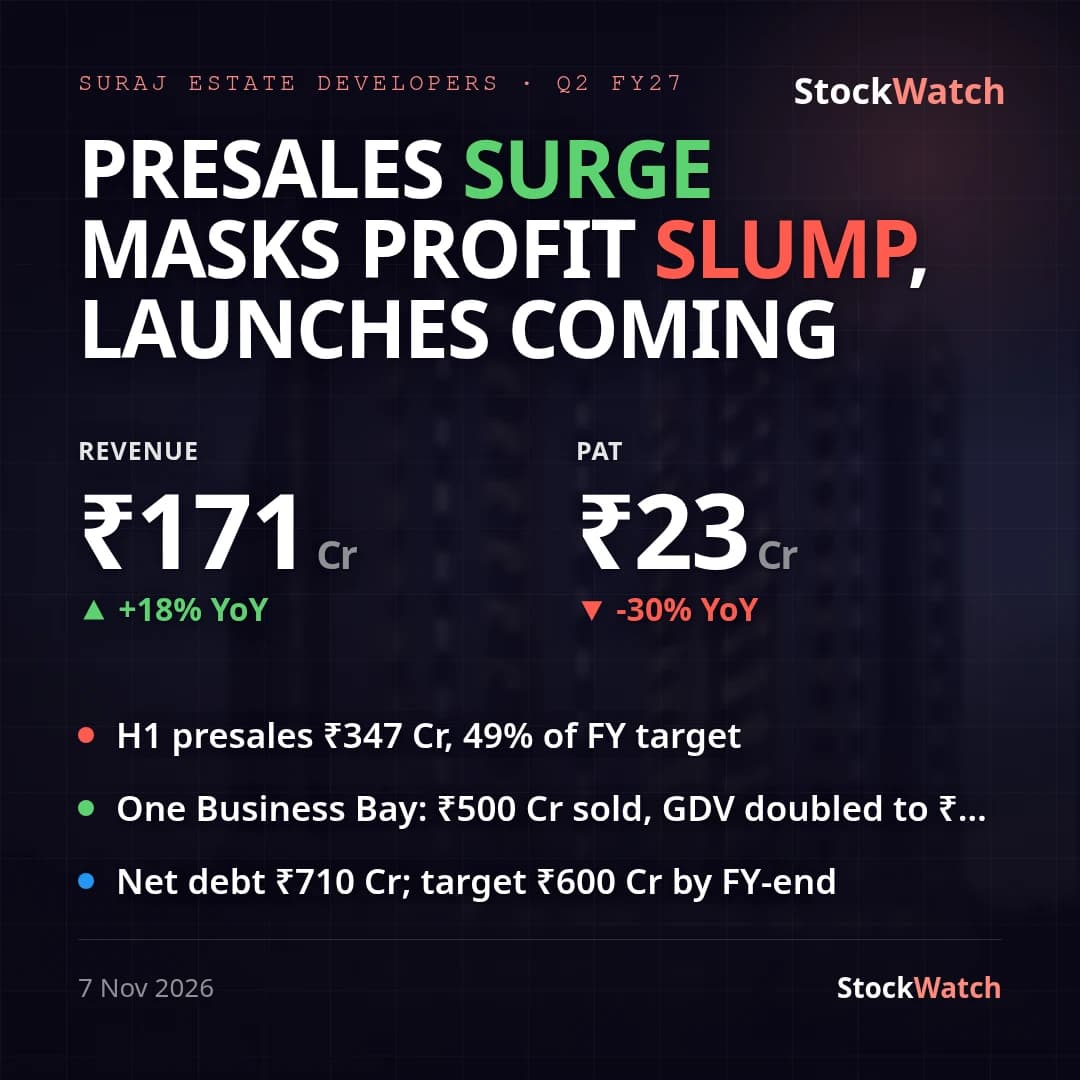
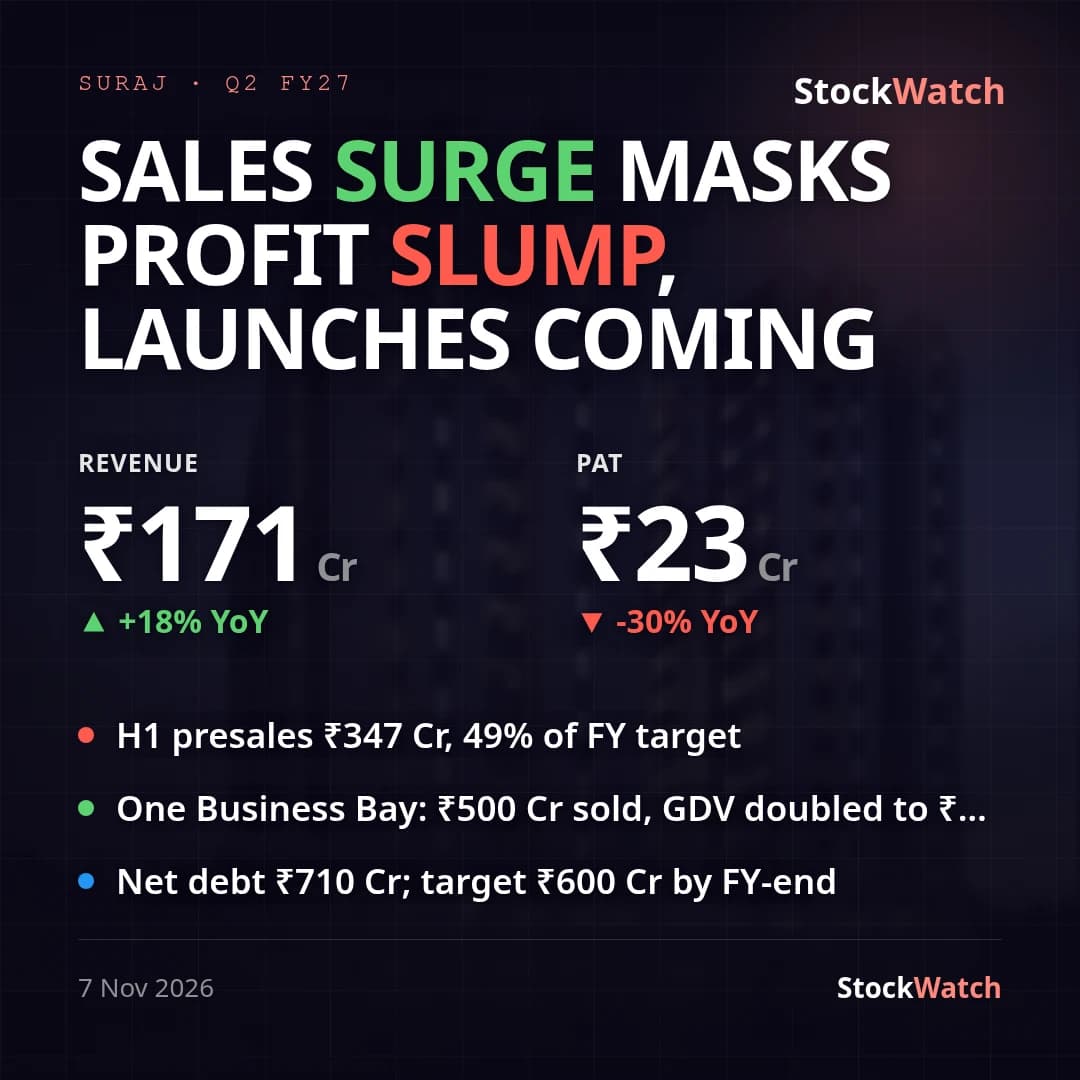
Suraj Estate Q2FY27: consolidated PAT falls 30% YoY to ₹23 Cr despite 18% revenue growth
Suraj Estate Developers' consolidated PAT fell 30.3% YoY to ₹23.07 Cr in Q2 FY27 (from ₹33.09 Cr), even as consolidated revenue from operations grew 17.6% YoY to ₹170.04 Cr (from ₹144.56 Cr). Sequentially, PAT was roughly flat (+1.0% QoQ versus ₹22.85 Cr in Q1 FY27) while revenue rose 17.5% QoQ — so the decline is purely a year-on-year story, not a sequential one, and with no exceptional items on either side of the comparison the decline is organic margin compression rather than a base effect.
Total expenses rose to 81.9% of total income from 69.7% a year ago (78.6% last quarter), pulling net profit margin down to 13.5% from 22.8% YoY (15.6% QoQ). Finance costs were a specific contributor, up 19.1% YoY to ₹24.39 Cr as borrowings climbed — gross debt stood at roughly ₹799.5 Cr at quarter-end versus ₹642.0 Cr at FY26 year-end — consistent with management's prior guidance that net debt (then ₹614 Cr) would rise temporarily to fund capacity build, including the ₹82.72 Cr Mahim land-rights acquisition closed September 25, 2026. Quarterly EBITDA margin came in near 33.0%, below the FY27 guided 35-37% band, though cumulative H1 FY27 EBITDA margin of ~35.1% still sits just inside the low end of that range.
Management's FY27 guidance called for 10-15% revenue growth; H1 FY27 consolidated revenue grew 13.6% YoY (₹314.76 Cr vs ₹277.03 Cr), tracking within that band even as the quarterly margin undershoot is a watch item. No formal Street consensus for this specific quarter turned up; the closest available read is an analyst FY27 PAT growth projection of 15-20% (univest.in) — this quarter's 30% YoY PAT decline runs well short of that full-year pace, though one quarter alone doesn't confirm a miss on the annual number. No press release or management commentary on this print was available to weigh against the figures. Standalone tells a materially different story than consolidated: standalone revenue fell 51.1% YoY to ₹69.03 Cr (from ₹141.08 Cr) and standalone PAT fell 47.2% YoY to ₹19.07 Cr (from ₹36.10 Cr) — a sharp divergence from consolidated's growth, indicating a growing share of billing is being recognized at the subsidiary/SPV level rather than in the standalone entity.
The widening gap between consolidated growth and standalone contraction, together with rising leverage for capacity build, makes H2 FY27 execution — converting the previously flagged ₹1,600 Cr launch pipeline and ₹700 Cr presales target into revenue without further margin give-up — the key swing factor for whether full-year guidance (10-15% revenue growth, 35-37% EBITDA margin) and the Street's 15-20% full-year PAT growth expectation stay reachable.