

Swaraj Engines Q2 FY27: revenue +26% YoY to ₹635 Cr, record PAT +22% beats soft guide
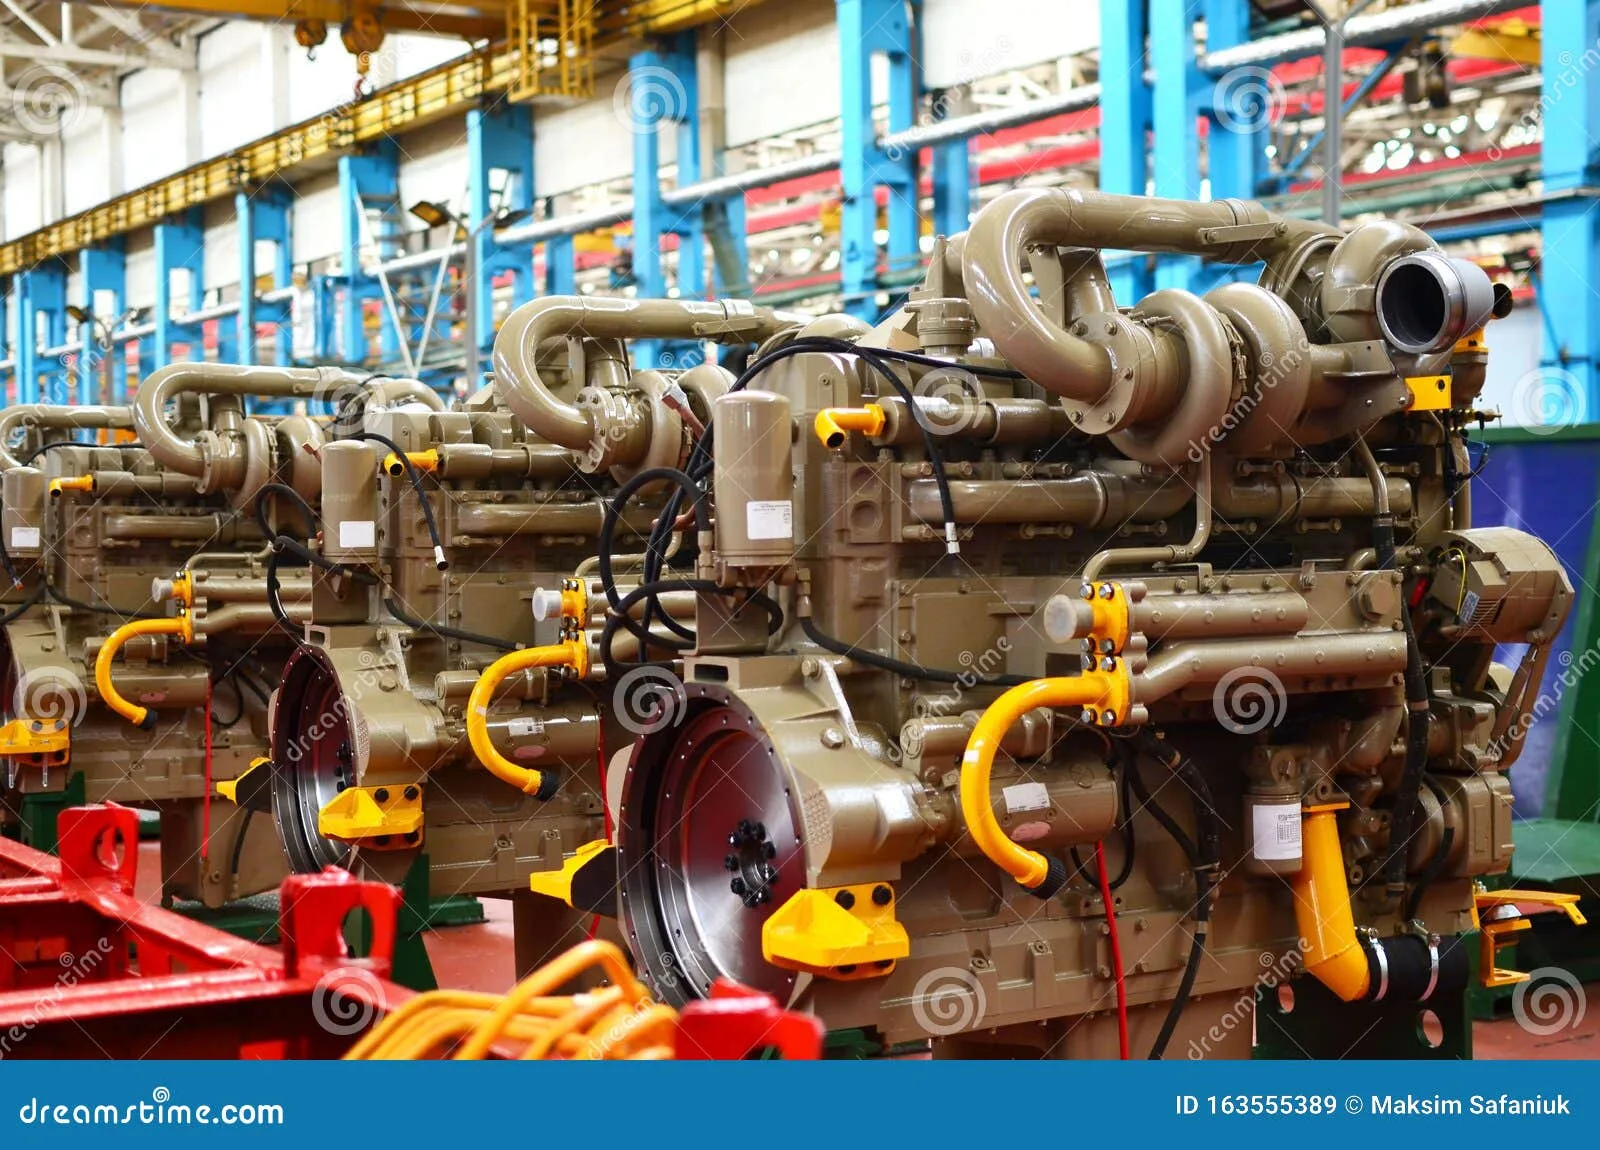
Swaraj Engines posted standalone revenue of ₹635.19 Cr in Q2 FY27, up 26.0% YoY (₹504.04 Cr) and 7.96% QoQ (₹588.39 Cr), on record engine sales of 61,216 units versus 51,164 a year ago (+19.7% YoY). PAT came in at ₹60.57 Cr, up 21.9% YoY and 9.1% QoQ — management calls it the highest-ever quarterly PBT (₹81.38 Cr) and PAT. Both figures are clean: there were no exceptional items in either the current or year-ago quarter, so reported YoY growth is also the adjusted growth. The print cleared every bar our pre-result preview set: revenue against an expected ₹520-550 Cr, volumes against an expected 52k-54k units, OPM against an expected 12.5-13%, and PAT growth against an expected low-to-mid-single-digit YoY print — the actual 21.9% PAT growth is roughly 4-5x the top of that range. Two of the three watch items we flagged resolved favourably (volume momentum stayed double-digit; OPM was defended well above 12.5%), but management gave no explicit H2/monsoon commentary to confirm the trajectory into H2. Operating margin actually expanded to 13.61% from 13.50% a year ago (and 13.05% last quarter) as cost of materials held flat near 79.2% of revenue while employee costs (2.56% vs 2.76% YoY) and other expenses (5.25% vs 5.39% YoY) both eased as a share of sales — classic operating leverage off record volumes. Net margin nonetheless slipped to 9.54% from 9.77% YoY: other income fell 65.7% YoY to ₹1.58 Cr (from ₹4.61 Cr) as the company drew down investments and bank deposits to fund a capex ramp, and depreciation rose to ₹6.55 Cr (from ₹5.79 Cr) as gross PP&E jumped to ₹199.64 Cr from ₹106.68 Cr at FY26-end, on H1 capex spend of ₹67.52 Cr versus just ₹13.77 Cr in H1 FY26. The tax rate was flat at ~25.6%, so the PBT-to-PAT bridge wasn't a factor. Management gives no formal forward guidance (none on record, and none found in a web check), so this result is judged against the Street's bullish pre-print stance: analyst consensus carried a Strong Buy rating with an average 12-month target of ₹4,572 (27-28% upside), reflecting confidence that Q1's surge was structural rather than a one-off. This quarter's accelerating YoY revenue growth (26.0% vs Q1's 21.5%) and sustained volume growth support that read, though a direct third-party Street PAT estimate for Q2 wasn't available to cross-check against the ₹60.57 Cr actual. The quarter also coincided with a management transition: Sanjay Kshirsagar, appointed Whole Time Director & CEO effective August 31, 2026, signs these results and fronts the press release, which frames the quarter as "growth in Q2 sales and profit" driven by "sustained customer demand" — a characterization the numbers back on revenue and volumes, though the net-margin dip shows some of that growth is being reinvested (via capex) rather than falling straight to the bottom line. H1 FY27 PAT of ₹116.10 Cr (+16.5% YoY) on revenue of ₹1,223.58 Cr (+23.8% YoY) confirms the growth has been sustained across both quarters, not a single-quarter spike.
Key Highlights
- Standalone revenue ₹635.19 Cr, +26.0% YoY / +7.96% QoQ, on record engine volumes of 61,216 units (+19.7% YoY vs 51,164)
- PAT ₹60.57 Cr, +21.9% YoY / +9.1% QoQ — management calls it the highest-ever quarterly PBT (₹81.38 Cr) and PAT
- OPM expanded to 13.61% (vs 13.50% YoY, 13.05% QoQ) but NPM slipped to 9.54% (vs 9.77% YoY) on a 65.7% YoY drop in other income (₹1.58 Cr vs ₹4.61 Cr) and higher depreciation (₹6.55 Cr vs ₹5.79 Cr)
- Beat every line of our pre-result preview: revenue vs ₹520-550 Cr expected, volumes vs 52k-54k expected, OPM vs 12.5-13% expected, PAT growth vs low-to-mid-single-digit YoY expected
- H1 FY27 PAT ₹116.10 Cr (+16.5% YoY) on revenue ₹1,223.58 Cr (+23.8% YoY), volumes 118,019 units (+17.8% YoY)
- Capex ramp: gross PP&E up to ₹199.64 Cr from ₹106.68 Cr at FY26-end, H1 capex spend ₹67.52 Cr vs ₹13.77 Cr H1 FY26
- No consolidated results — company has no subsidiary/associate/JV; basic EPS ₹49.86 vs ₹45.70 QoQ and ₹40.89 YoY
Price Impact
More from SWARAJENG