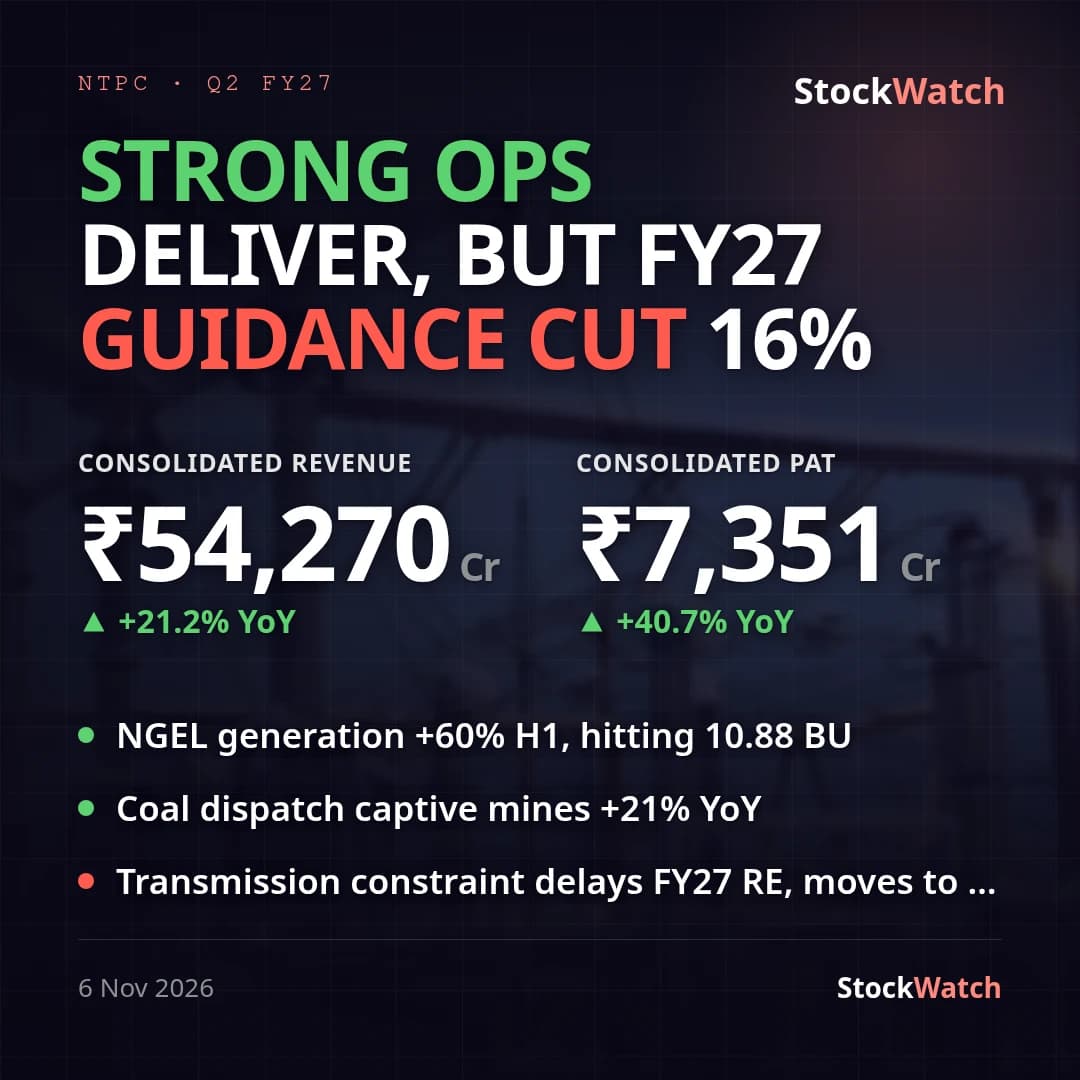
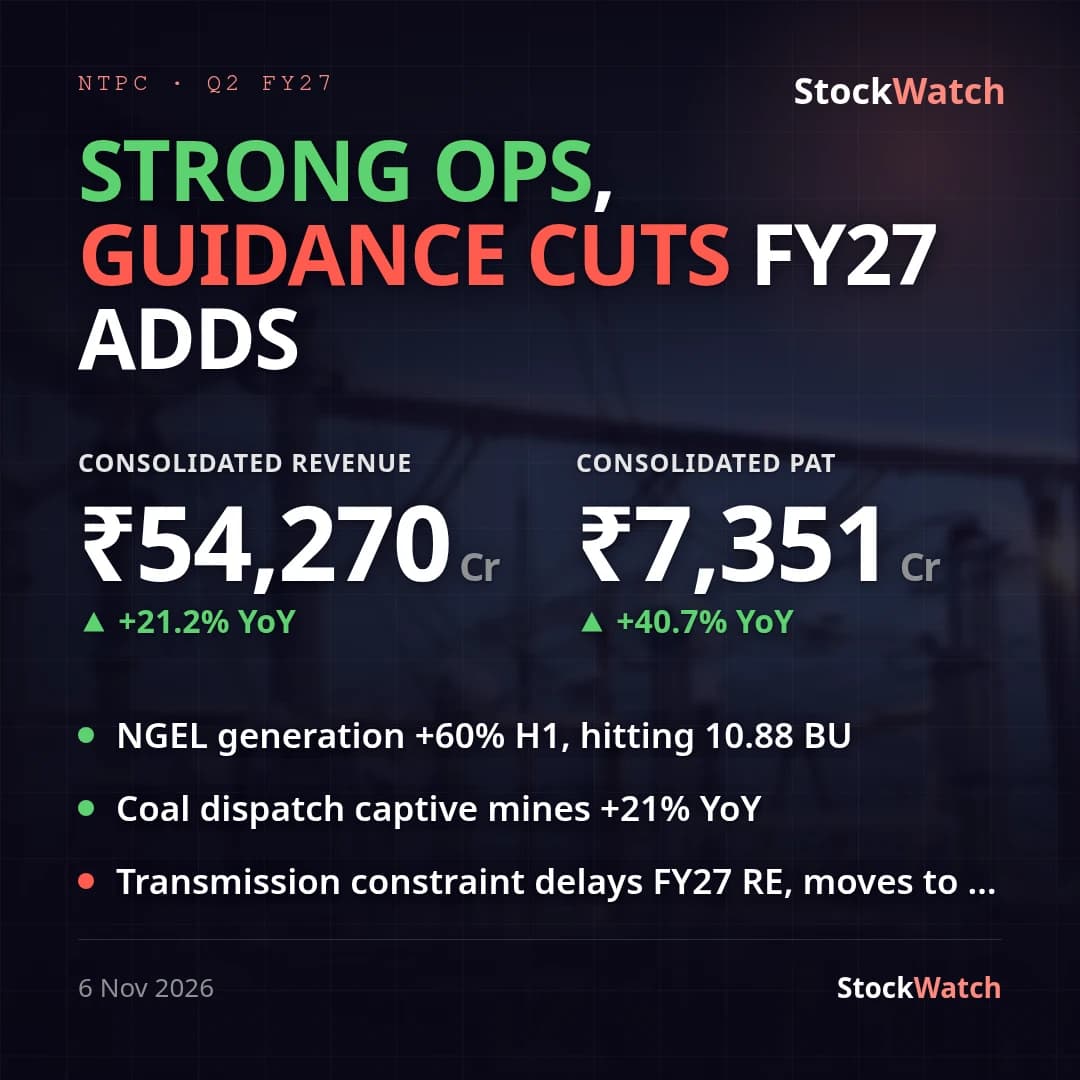
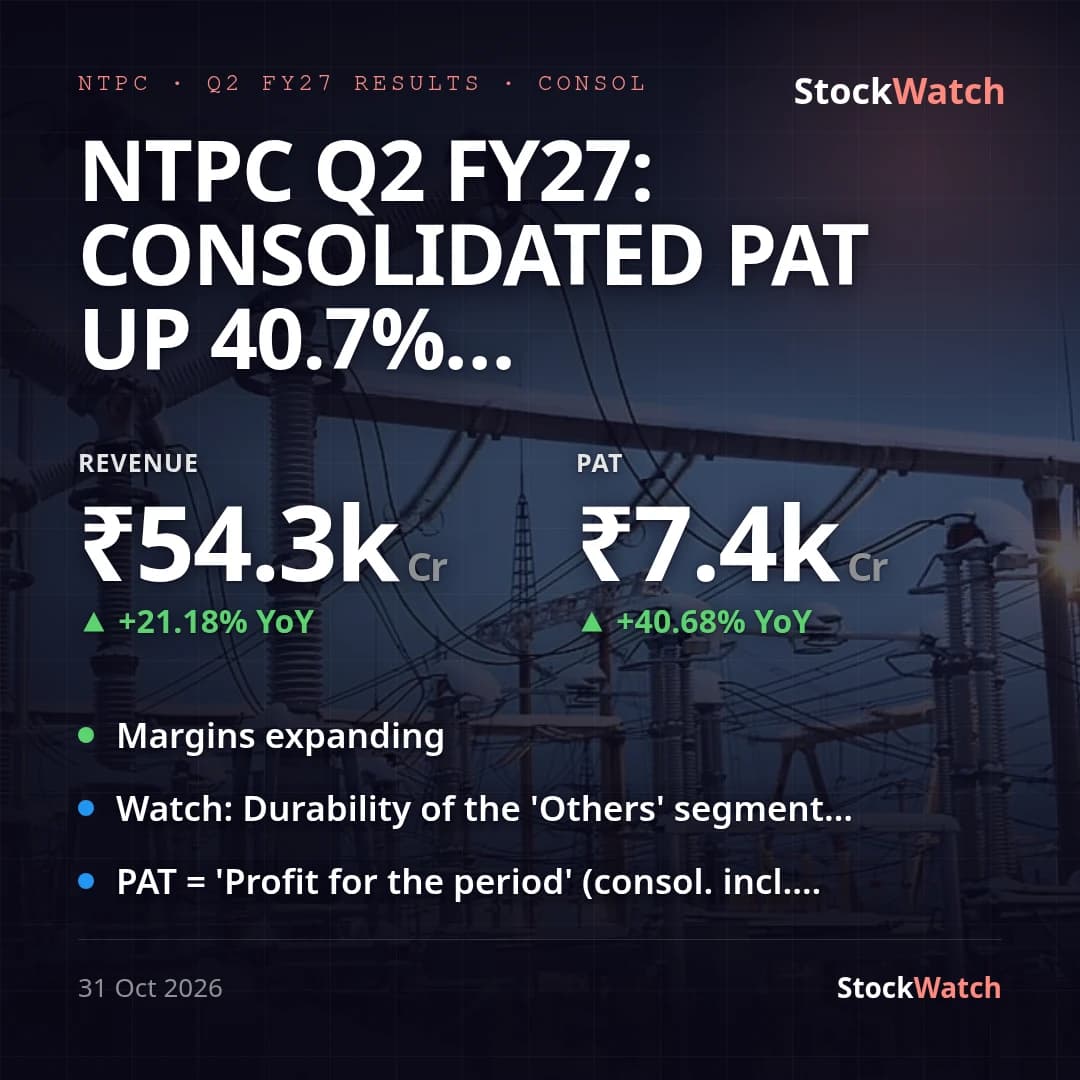
NTPC Q2 FY27: consolidated PAT up 40.7% YoY to ₹7,351 Cr, revenue +21.2%, margins expand
NTPC's consolidated (primary) PAT for Q2 FY27 came in at ₹7,350.79 Cr, up 40.7% YoY from ₹5,225.30 Cr and up 6.6% QoQ from ₹6,896.44 Cr, on revenue from operations of ₹54,269.95 Cr (+21.2% YoY, +7.0% QoQ). Consolidated NPM expanded to 13.54% from 11.67% a year ago (OPM 23.38% vs 21.99%), while QoQ margins held roughly flat against Q1 FY27's 13.59%/23.83%. Standalone (secondary) PAT was ₹5,319.94 Cr on revenue of ₹45,752.00 Cr.
The headline PAT growth isn't driven by the core generation business alone. Consolidated segment results show 'Generation' profit of ₹9,212.36 Cr, up a more modest 12.7% YoY (₹8,175.63 Cr) but down 12.7% QoQ (₹10,548.80 Cr) on higher finance costs (₹4,086.43 Cr vs ₹3,432.46 Cr YoY) and depreciation (₹5,329.78 Cr vs ₹4,815.50 Cr). The outsized swing came from the 'Others' segment (trading/non-generation units), whose profit jumped to ₹1,674.81 Cr from ₹260.30 Cr a year ago and ₹899.56 Cr in Q1 FY27. Separately, the net movement in regulatory deferral account balances — NTPC's routine CERC tariff true-up mechanism — added back ₹1,936.20 Cr post-tax this quarter, versus ₹520.06 Cr in Q1 FY27 and ₹1,677.15 Cr a year ago. Stripping this out, underlying pre-deferral profit was ₹5,414.59 Cr, up a stronger 52.6% YoY (from ₹3,548.11 Cr) — so the regulatory item is not inflating the YoY story; core growth excluding it is even better than the headline.
No formal Street consensus specific to this quarter could be confirmed — public trackers show only a full-year FY27 revenue consensus (~₹2.08 lakh Cr) with no Q2 FY27-specific preview on record, so vsStreet is marked unknown rather than assumed. Against management's own prior guidance (FY27 capacity addition of ~9.6 GW — 7-8 GW renewable plus thermal/coal — and a 36-40% dividend payout ratio that was to 'keep increasing'), this quarter's confirmed capacity progress was limited to a subsidiary's 95.6 MW solar commissioning and its first BESS project going commercial — too small to independently verify trajectory against the 9.6 GW target, so guidance tracking is unknown rather than beat/met/missed. The Board did declare a first interim dividend of 30% (₹3/share, face value ₹10, record date 6 November 2026), consistent with the stated intent to raise payouts, though the full-year ratio against the 36-40% target can't be assessed until year-end. Other developments this quarter — LIC raising its stake to 7.004% (22 October), two director appointments (19 and 23 October), and a clarification of a news article (20 October) — don't move the P&L. No management press release accompanying this result has been extracted, so there is no company framing to reconcile against the filed numbers. Notably, standalone and consolidated growth diverge materially: standalone revenue grew 16.8% YoY (vs consolidated 21.2%) and standalone PAT grew just 14.3% YoY (vs consolidated 40.7%) — a >26 percentage-point gap — because standalone Generation segment profit actually fell both YoY (-2.3%) and QoQ (-27.3%), fully offset by a surge in the parent's own Others segment (₹272.70 Cr to ₹1,350.35 Cr YoY). Readers comparing the standalone figure elsewhere should not read it as contradicting consolidated strength — it reflects where in the group structure the quarter's gains landed.
Going into Q3 FY27, the durability of the Others-segment contribution and the regulatory deferral add-back's trajectory are the two accounting-driven swing factors to track, alongside confirmed progress on the ~9.6 GW capacity target beyond this quarter's incremental solar and BESS commissioning.