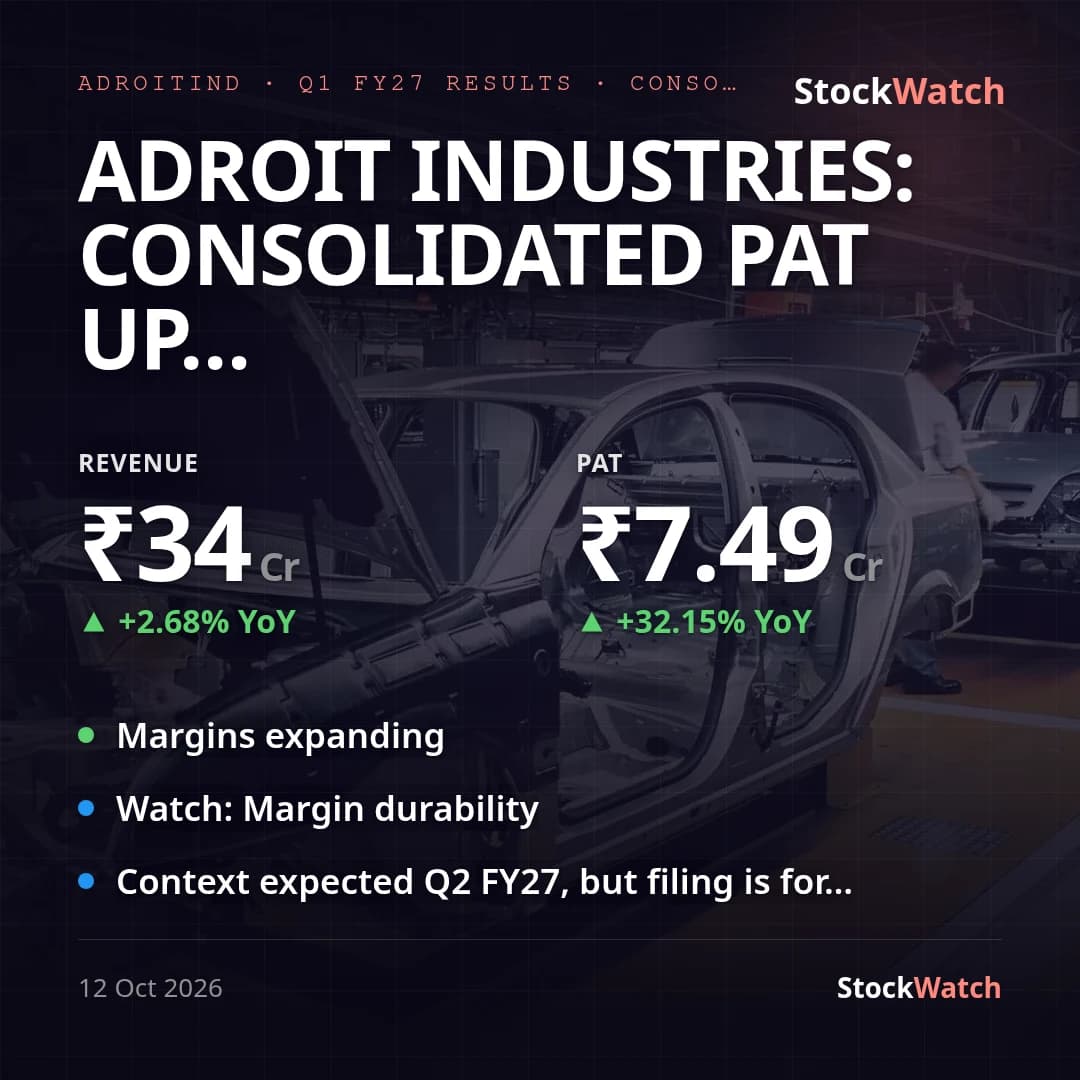
Adroit Industries: consolidated PAT up 32% YoY to ₹7.5 Cr on sharp margin expansion
Adroit Industries, the Pithampur-based propeller-shaft (driveshaft) manufacturer, reported its first quarterly result since listing on the BSE and NSE on September 30, 2026. On a consolidated basis — the primary read, since subsidiaries now account for most of group revenue — PAT rose 32.2% YoY to ₹7.49 Cr on revenue of ₹34.11 Cr, up a modest 2.7% YoY. Sequentially revenue fell 13.1% QoQ against a seasonally stronger March quarter (₹39.25 Cr) while PAT still rose 9.4% QoQ. On a standalone (parent-only) basis the picture diverges sharply: revenue fell 24.1% YoY to ₹8.51 Cr even as PAT rose 9.1% YoY to ₹0.69 Cr — a reminder that consolidated, not standalone, now tells the group's real story.
The YoY profit growth was margin-led rather than volume-led. Consolidated net margin expanded to 21.9% from 17.1% a year ago, and PBT margin to 27.9% from 22.9%, as total expenses actually fell 0.3% YoY (₹25.87 Cr vs ₹25.95 Cr) even as revenue grew 2.7% — driven mainly by lower other expenses (₹8.40 Cr vs ₹10.46 Cr) and reduced stock-in-trade purchases, partly offset by higher employee costs (₹5.93 Cr vs ₹5.41 Cr). No exceptional items feature in either statement, so this is a clean, unadjusted comparison.
There is no analyst coverage or consensus estimate on record for this recently listed micro-cap (IPO priced at ₹134/share, a ₹150.71 Cr issue in September 2026), and management has issued no formal guidance, so the print cannot be benchmarked against a street number or a prior outlook; no company press release was available for this filing either. The auditors' limited-review note breaks out the subsidiary contribution: Indian unit Adroit Driveshafts Pvt Ltd added ₹32.07 Cr revenue and ₹6.68 Cr PAT, while the two foreign units (Canada, USA) together added ₹1.65 Cr revenue and ₹0.52 Cr PAT — together explaining why consolidated revenue runs roughly four times standalone. The company operates a single reportable segment (propeller shafts) under Ind AS 108, so no further segment detail is disclosed; the quarter's other corporate events — the FY26 annual report/32nd AGM notice (Oct 6) and routine insider-trading window closures — are procedural and don't bear on the P&L.
With this the first consolidated quarterly filing and the first as a listed company, Q2 FY27 will be the first period with a genuine YoY consolidated comparable base and the first chance for management to set out formal guidance; until then, the ~22% consolidated net margin and the standalone-consolidated gap are the two numbers worth tracking.