StockWatch
·

ALKYL AMINES CHEMICALS LTD.-$

BSE: 506767

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27·vs Q2 FY26
Revenue
501.72
-6.6%+26.4%
Expenditure
411.63
-0.2%+21.9%
Net Profit
65.17
-31.1%+51.8%
OPM %
19.90%
-5.40pp+1.87pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.00150.45300.89451.34601.79Q2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

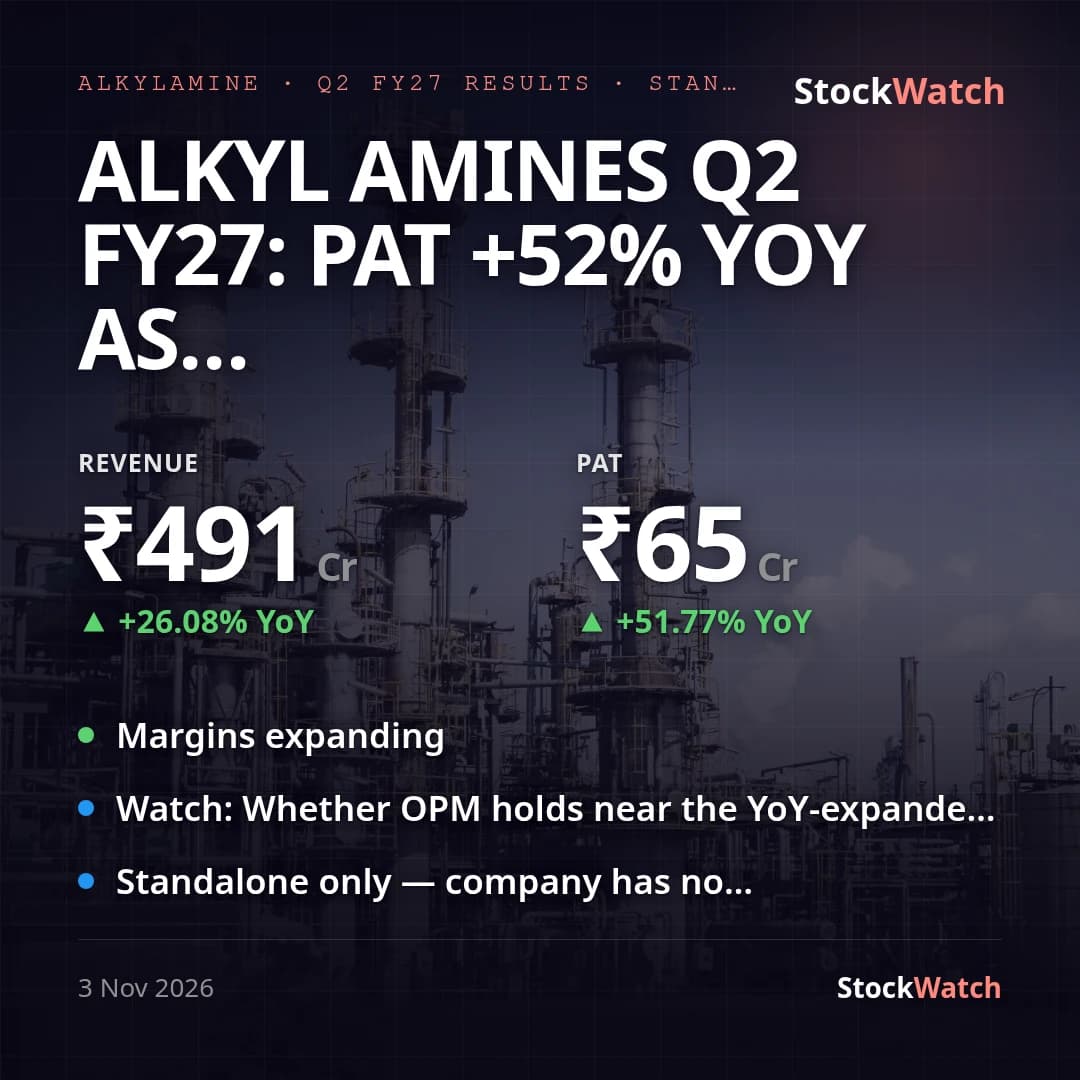
Alkyl Amines Q2 FY27: PAT +52% YoY as margins expand, but cools 31% QoQ off Q1 peak

specialty chemicals · margin expansion · sequential slowdown

ResultsQ2 FY2703 Nov 20263 minMetals & Mining

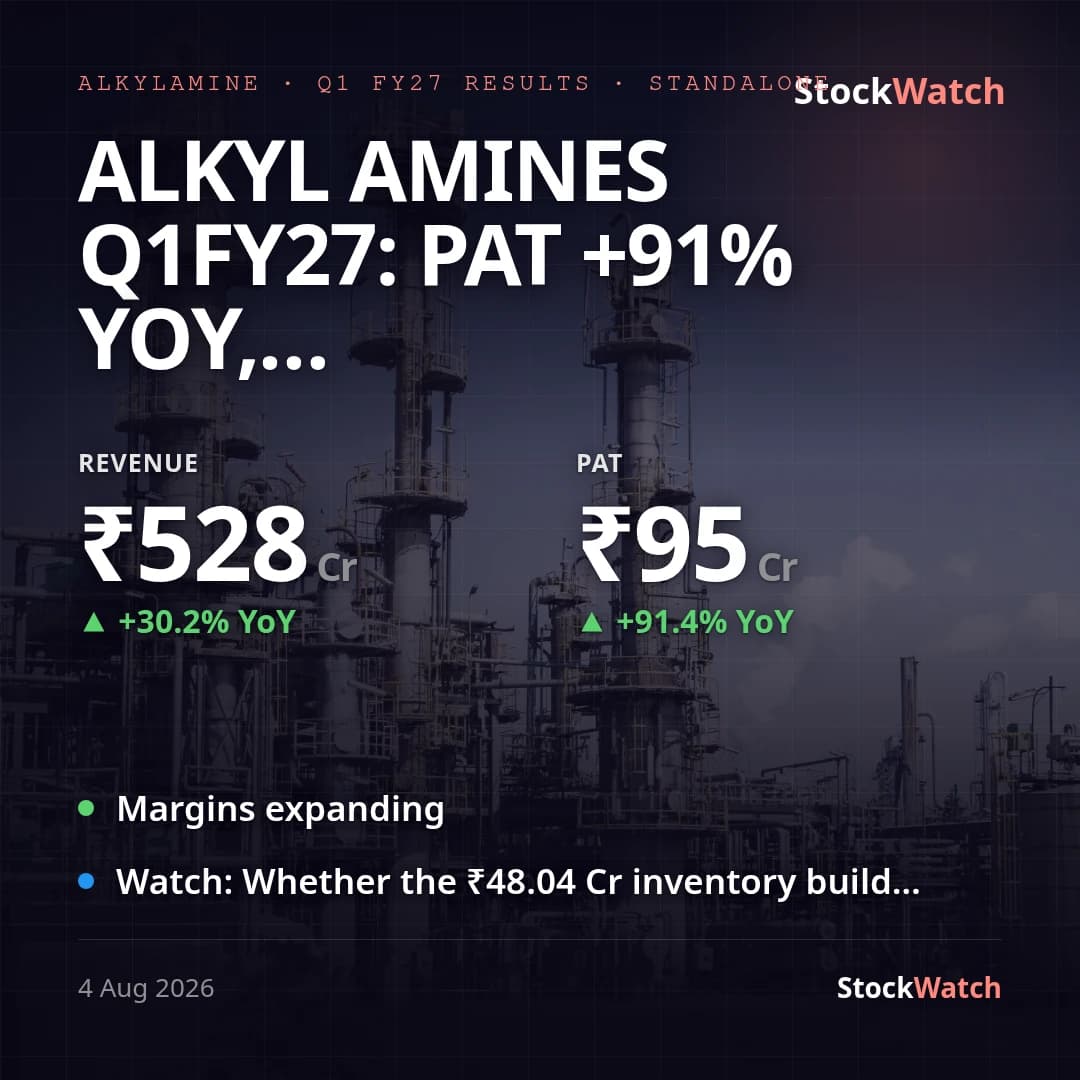
Alkyl Amines Q1FY27: PAT +91% YoY, revenue +30%, margins expand to 25.3%

specialty chemicals · margin expansion · inventory swing

ResultsQ1 FY2704 Aug 20263 minMetals & Mining

Ammonia Recovery to Drive Q1 Print—Watch for Margin Normalization

ammonia supply · margin recovery · specialty amines

Result previewQ1 FY2704 Aug 20263 minMetals & Mining
Latest
Quarterly Result3 Nov, 1:21 pm

Alkyl Amines Q2 FY27: PAT +52% YoY as margins expand, but cools 31% QoQ off Q1 peak

Alkyl Amines' standalone PAT came in at ₹65.17 Cr on revenue from operations of ₹490.95 Cr for the September 2026 quarter. Year-on-year — the primary read — revenue grew 26.1% (₹389.41 Cr) and PAT grew a faster 51.8% (₹42.94 Cr), with net margin expanding to 13.0% from 10.8% and operating margin to 19.9% from 18.0%. Sequentially the print is softer: revenue fell 7.0% and PAT fell 31.1% against Q1 FY27 (revenue ₹528.01 Cr, PAT ₹94.63 Cr, OPM 25.3%), but Q1 was itself an exceptionally strong base — the company had flagged PAT +91% YoY and margin expansion to 25.3% that quarter — so the QoQ dip reads as reversion rather than fresh deterioration; no exceptional items appear in any of the compared quarters. The margin bridge sits mostly on operating leverage: cost of materials consumed eased to 53.1% of revenue from operations (versus 59.9% in Q1 and 49.2% a year ago), but employee costs (₹33.95 Cr) and other expenses (₹90.16 Cr) held roughly flat in absolute terms versus Q1 (₹36.31 Cr and ₹90.05 Cr), so the 7% QoQ revenue decline compressed operating margin from Q1's elevated 25.3% to 19.9% — still above the year-ago 18.0%. Tax worked out to ₹24.92 Cr on PBT of ₹90.09 Cr (effective rate 27.7%), in line with recent quarters. No public analyst consensus for this quarter turned up in search, so vs-street is unknown rather than assumed. Against management's own May 2026 concall guidance — 5-10% volume growth for the year, revenue significantly higher on elevated prices, and margins bottoming out with room to improve — this print is broadly on-track: YoY revenue and margin both moved in the guided direction, though the QoQ pullback means the margin recovery is not yet linear. No management press release commentary was available in the context to cross-check against. Separately, the stock saw a trading-volume spike in early October that drew a BSE clarification request (company confirmed no undisclosed price-sensitive information) — unrelated to this result. On the balance sheet, the company drew ₹19 Cr of secured borrowings for the first time in recent periods and capital work-in-progress rose to ₹159.53 Cr from ₹130.48 Cr, with H1 FY27 capex of ₹36.72 Cr tracking within the ₹80-90 Cr full-year guided band.

3 Nov 2026, 01:21 pm

Board Meeting4 Aug, 2:26 pm

Alkyl Amines Q1FY27: PAT +91% YoY, revenue +30%, margins expand to 25.3%

Alkyl Amines' standalone revenue for Q1 FY27 came in at ₹528.01 Cr, up 30.2% YoY from ₹405.53 Cr and up 36.5% QoQ from ₹386.91 Cr. Standalone PAT of ₹94.63 Cr rose 91.4% YoY (₹49.44 Cr) and 108.6% QoQ (₹45.37 Cr), with basic EPS of ₹18.50 for the quarter versus ₹9.67 a year ago. The company reports only standalone numbers — it has no subsidiary, associate or joint-venture entity for the quarter, per note 5 of the filing, so there is no consolidated figure to reconcile against. Reported EBITDA margin (OPM) jumped to 25.3% from 18.9% a year ago and 18.3% last quarter, but the bulk of that expansion traces to one working-capital line: 'changes in inventories of finished goods and WIP' swung to a ₹48.04 Cr build this quarter, against a ₹23.37 Cr drawdown in Q4 FY26 and a ₹1.53 Cr drawdown a year ago — swings of roughly ₹71 Cr and ₹50 Cr respectively that mechanically lower recognised cost of goods sold. Normalising that swing back to flat cuts implied OPM to roughly 16%, below the 18-19% seen in the comparison quarters. Consistent with that, cost of materials consumed actually rose to 59.9% of revenue this quarter versus 53.8% a year ago and 48.1% last quarter — the raw-material cost ratio worsened even as the headline margin expanded. Management's prior (Q4 FY26) guidance had flagged 'cautious optimism that margins have bottomed out' on the back of passing through higher input costs; the reported margin did expand, but the underlying materials-cost trend suggests that pass-through has not yet shown up cleanly, and part of this quarter's margin story would reverse if the inventory build is drawn down next quarter. No consensus estimate for this specific quarter surfaced in a web search, so the print cannot be graded against a street number. Peer Balaji Amines separately reported a 114% YoY PAT jump for the same quarter, suggesting a sector-wide raw-material tailwind rather than one specific to Alkyl Amines. On June 3, 2026 the company issued a clarification on a volume surge in its stock ahead of results, and today's board meeting also approved a succession plan: Yogesh Kothari moves to Executive Chairman, Kirat Patel and Suneet Kothari are elevated to Joint Managing Director, and Rakesh Goyal is re-designated Executive Director – Operations, all effective October 1, 2026 and subject to shareholder approval by postal ballot. No management press release accompanied the filing and no fresh FY27 guidance was given beyond what was stated last quarter (5-10% volume growth, capex capped near ₹80-90 Cr); the inventory drawdown pace and materials-cost ratio in Q2 FY27 are the cleanest checks on whether this quarter's margin expansion holds.

4 Aug 2026, 02:26 pm

Corporate Events

Board MeetingALKYLAMINE
2026
3Nov

Board Meeting

The meeting of the Board of Directors of the Company will be…

BSE Filing ↗
Board MeetingALKYLAMINE
2026
4Aug

Board Meeting

The meeting of the Board of Directors will be held to consid…

BSE Filing ↗
Board MeetingALKYLAMINE
2024
5Nov

Board Meeting

Approval Of Unaudited Financial Results

BSE Filing ↗
Board MeetingALKYLAMINE
2024
1Aug

Board Meeting

Approval of Unaudited Financial Results

BSE Filing ↗
Board MeetingALKYLAMINE
2024
9May

Board Meeting

approval of Audited Financial Results for the quarter and fi…

BSE Filing ↗
Board MeetingALKYLAMINE
2024
2Feb

Board Meeting

Approval of Unaudited Financial Results for the quarter and …

BSE Filing ↗
Board MeetingALKYLAMINE
2023
7Nov

Board Meeting

Approval of Unaudited Financial Results for the quarter and …

BSE Filing ↗