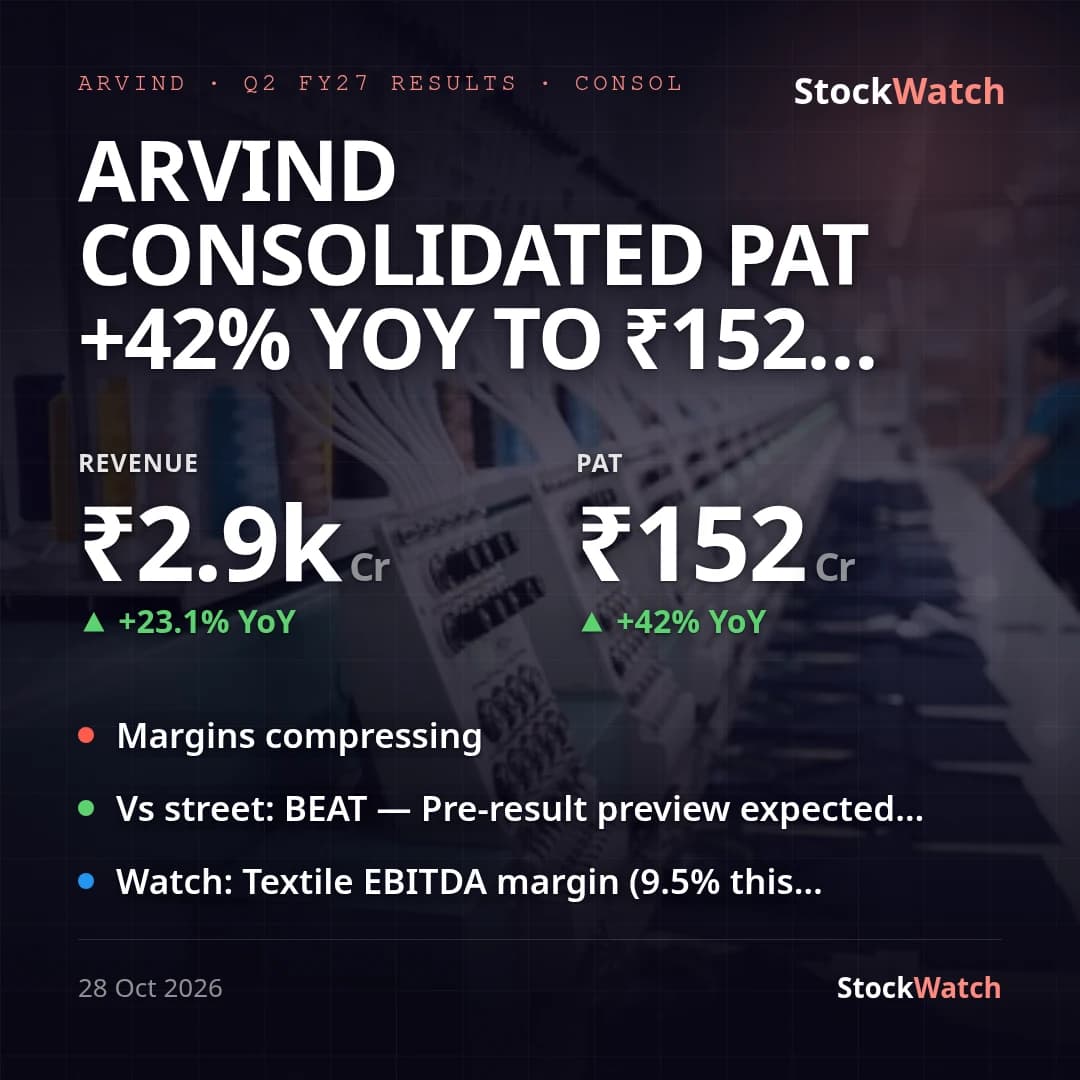
Arvind consolidated PAT +42% YoY to ₹152 Cr, adjusted growth ~16% after one-off gain
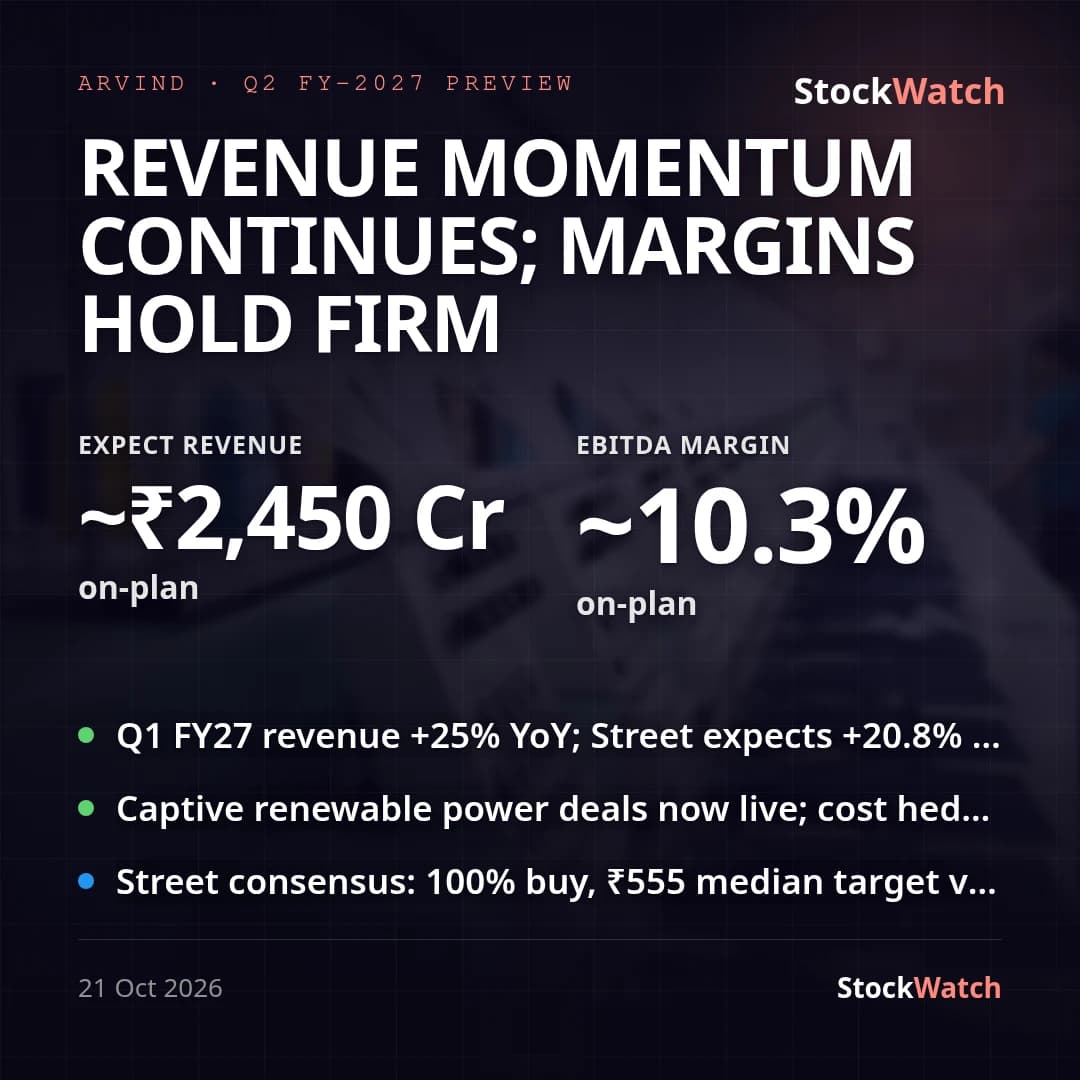
Arvind's consolidated revenue hit an all-time-high ₹2,918.62 Cr for Q2 FY27, up 23.1% YoY and 16.7% QoQ, comfortably ahead of our pre-result preview's ~₹2,450 Cr expectation and its ~10.3% EBITDA margin bar (actual 11.4%) — a clear beat on both counts. Consolidated PAT of ₹151.6 Cr is reported up 42.0% YoY, but that number is flattered by a ₹28.2 Cr net exceptional gain (mostly a ₹30.7 Cr reversal of an old land-impairment provision after authorities withdrew the underlying demand) against zero exceptional items a year ago; stripped of one-offs, PAT (company-reported "before exceptional items") was ₹123 Cr, up ~16% YoY — the figure management itself highlighted, and the one to anchor to over the headline 42%.
EBITDA grew a genuine 27% YoY to ₹331 Cr with margin up 40bps to 11.4%, driven by a richer mix toward higher-margin Advanced Materials (AMB): AMB India revenue +23% YoY to ₹550 Cr with EBITDA +29% to ₹78 Cr (14.2% margin), plus a first full quarter of the newly acquired Dalco-GFT business contributing ₹256 Cr revenue and ₹41 Cr EBITDA at a 16.0% margin. Core Textiles told a weaker story: EBITDA margin compressed ~75bps YoY to 9.5% as cotton, yarn and dyes-chemicals costs outran realisation increases (denim realisation +12% YoY to ₹266/mtr, woven +12% to ₹227/mtr). Below the EBITDA line, finance costs jumped 71% YoY to ₹70.7 Cr and depreciation 49% to ₹107 Cr, both inflated by the debt and intangible-amortisation load from funding the Dalco-GFT acquisition — which is why adjusted net margin (~4.23%) actually dipped versus a year ago (4.50%), even as EBITDA margin expanded.
Against the targets management set on the last concall (AMD 18–20% medium-term growth, Garments ~15% FY27 growth, Dalco 9–10% growth, AMD+Dalco combined margin 15–17%), the quarter was a mixed scorecard: AMB India's 23% growth beat the guided range, but garmenting revenue grew only ~9% YoY to ₹577 Cr on flat volumes (11.1 Mn pieces, a second straight quarter at that level) — short of the 15% target — and the AMB+Dalco combined EBITDA margin of 14.8% landed just under the guided 15–17% band. The quarter carried real corporate-action weight too: Care Ratings upgraded Arvind one notch to "AA" (stable outlook), the company commissioned Phase 1 of its Varanasi greenfield garmenting facility (~₹75 Cr capex, ~₹250 Cr annual revenue potential) inaugurated October 25, and it closed a 46% stake in Arvind GCC on October 6 alongside the 26.6% Torrent Urja 21 renewable-power stake completed September 17 — both consistent with the capital-deployment plans flagged pre-result. Management's own framing — "strong momentum in Advanced Material Business, headwind in cost persists" — matches the numbers: the AMB-led revenue and EBITDA beat is real, but textile cost inflation and acquisition-financing costs are the swing factors keeping underlying profit growth well behind the headline 42% PAT print.
For Q3 FY27, management guides AMB India revenue/EBITDA growth of ~18% at a stable 14–15% margin, Dalco-GFT growth at 15–16% margin, "early double-digit" textile revenue growth with margin holding near current (pressured) levels, and full-year capex crossing ₹500 Cr. The read-through: the growth engine (AMB, Dalco-GFT) is intact and beating its own targets, but textile margin recovery and the interest/depreciation drag from the Dalco-GFT acquisition — not the exceptional-item noise — are what will determine whether reported PAT growth converges back toward the ~16% adjusted run-rate or re-accelerates.