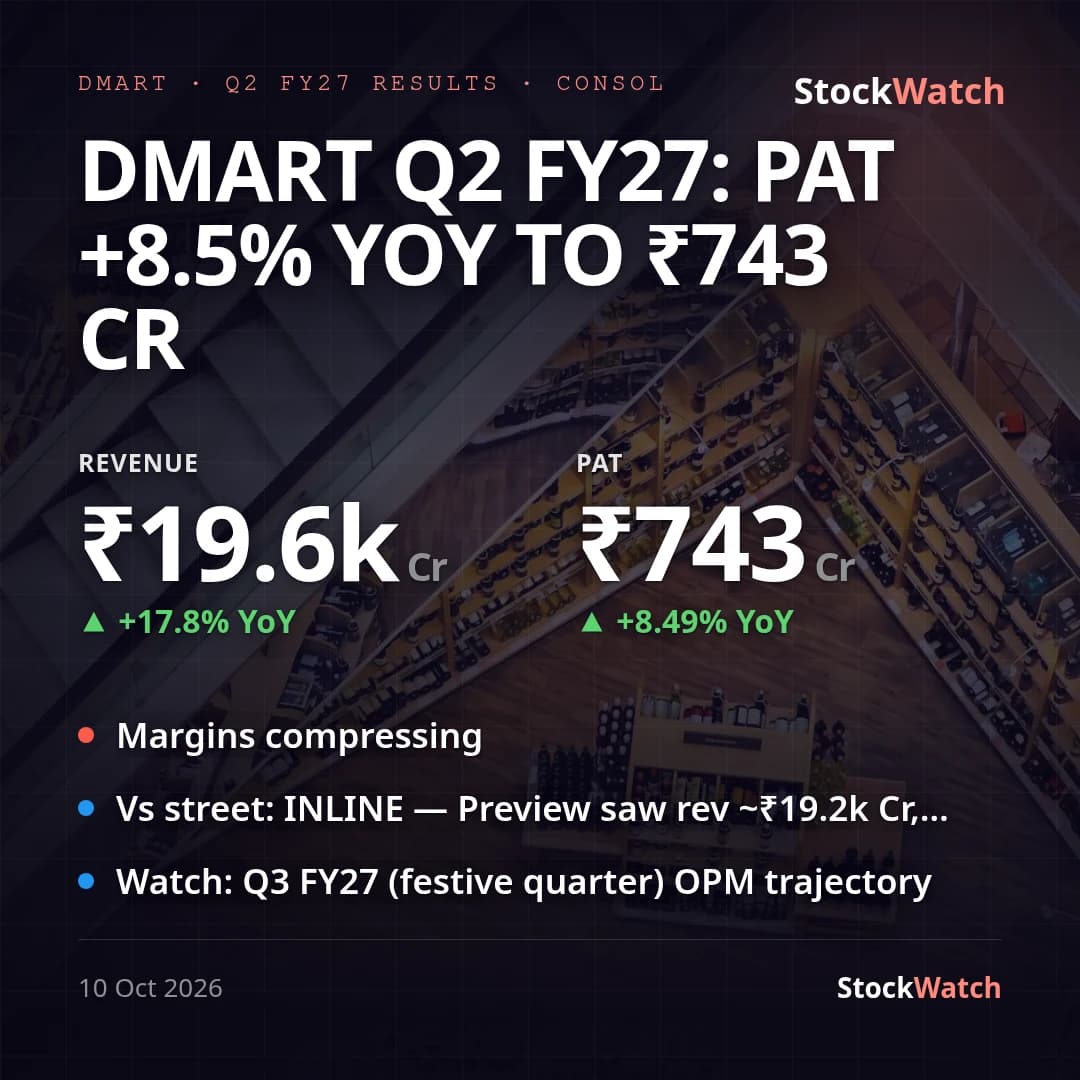
DMart Q2 FY27: PAT +8.5% YoY to ₹743 Cr, NPM dips to 3.78% despite 17.8% revenue growth
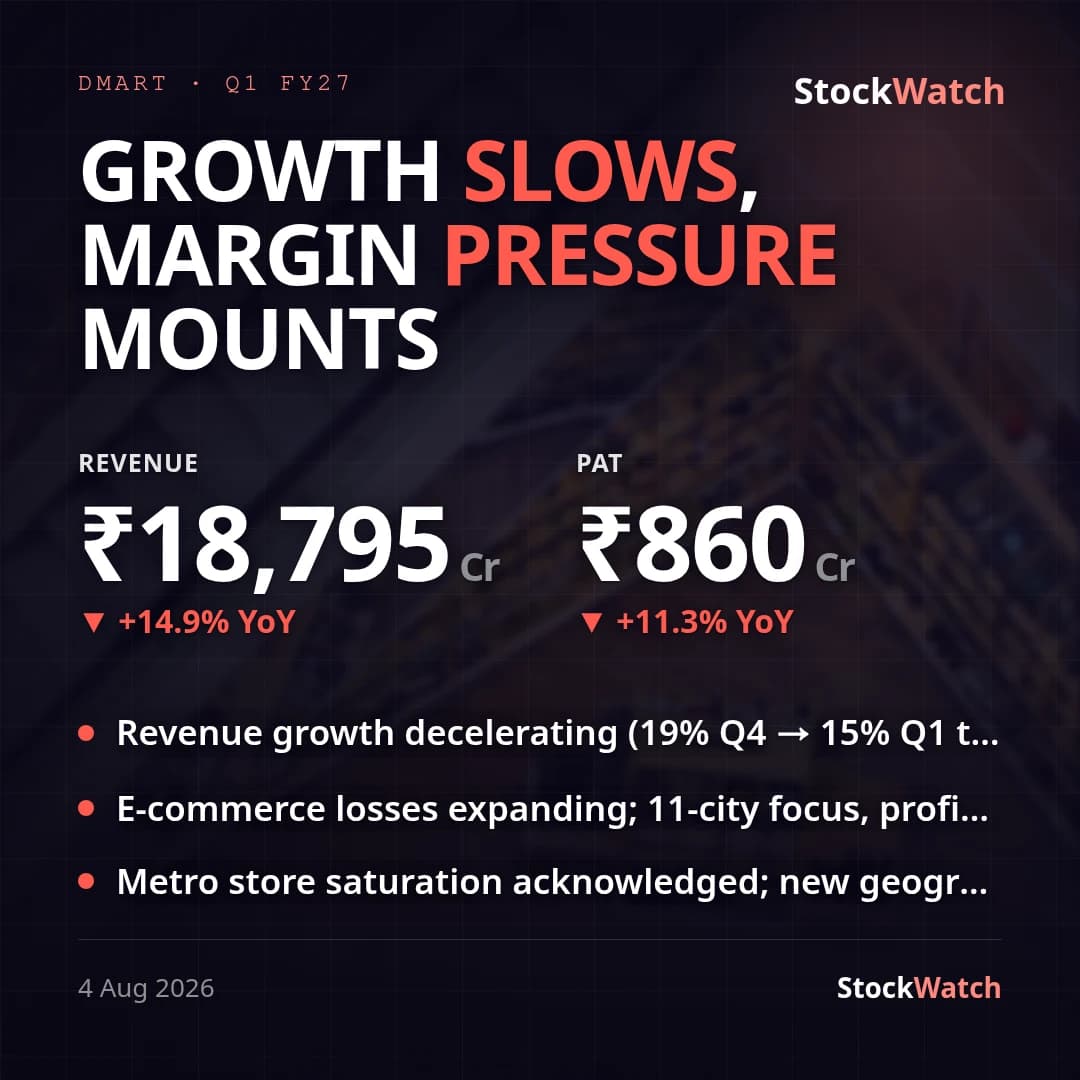
Avenue Supermarts (DMart) reported consolidated revenue of ₹19,644 Cr for Q2 FY27 (quarter ended Sep 30, 2026), up 17.8% YoY from ₹16,676 Cr and up 4.5% QoQ from ₹18,795 Cr. Consolidated PAT was ₹743 Cr, up 8.5% YoY from ₹685 Cr but down 13.7% QoQ from ₹860 Cr. Standalone (parent-only) PAT was higher at ₹804 Cr (EPS ₹12.32) versus consolidated EPS of ₹11.40 — the gap is a loss-making subsidiary, not a standalone/consolidated discrepancy in the core business.
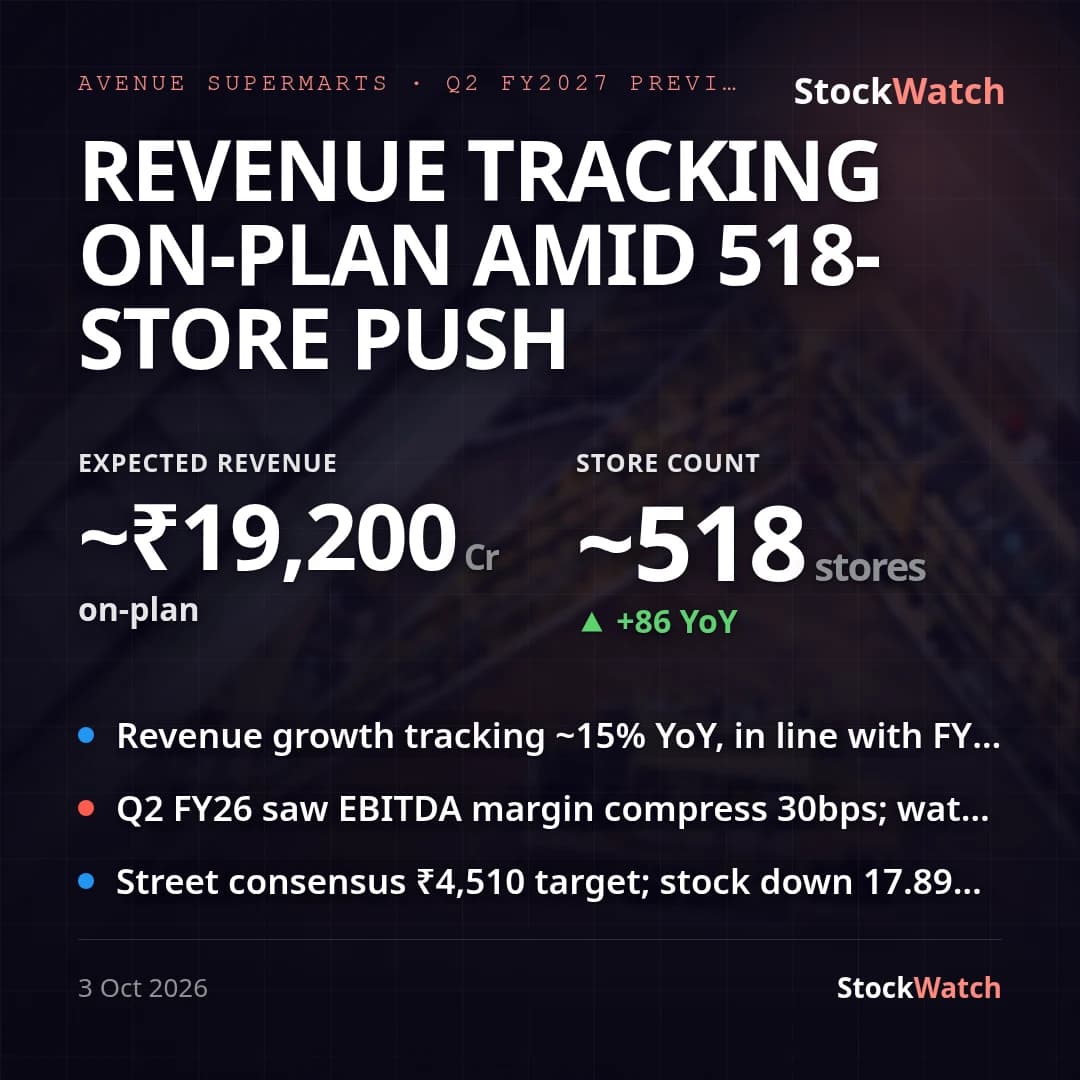
Revenue and EPS landed essentially in line with the pre-result preview (~₹19,200 Cr revenue, EPS ₹11–12), and consolidated operating margin of 7.09% sat inside the previewed 7.0–7.3% watch band, though at the low end — continuing the YoY compression flagged going in: OPM fell from 7.28% a year ago, and NPM from 4.11% to 3.78%. Gross margin, by contrast, held up at roughly 14.9% of revenue, within management's stated 14–15% North Star band, so the squeeze sits below the gross-margin line: employee costs rose to ₹447 Cr from ₹376 Cr YoY, depreciation to ₹318 Cr from ₹253 Cr as the store and capex base expanded, and finance costs nearly doubled YoY to ₹64 Cr as short-term borrowings climbed to ₹2,629 Cr from ₹965 Cr at FY26-end. The sequential PAT decline is largely a seasonality artifact typical of the July–September quarter for grocery retail — Q1 FY27 carried a materially richer 4.58% NPM — and should not be read as a standalone warning sign.
Street sentiment going in was split (32% Buy, 39% Hold, 29% Sell per our pre-result tracking), with bears citing the stock's 18% de-rating from its 2024 ATH on margin and same-store-sales concerns; this print, with margins compressing roughly as expected rather than materially worse, does not resolve that debate either way. The company added 3 stores in the quarter (including one in Ahmedabad) to reach 518, consistent with its 15% annual store-addition target, and separately rolled over ₹500 Cr of commercial paper on Sep 30 after repaying ₹300 Cr and ₹200 Cr of maturing CP in late September — routine working-capital activity, not a liquidity signal. No same-store-sales figure was disclosed in this filing to check progress against management's stated 7–8% FY27 target, and no separate press-release commentary from management was available to cross-check against the numbers.
With consolidated net margin at 3.78%, still below the ~5% net-margin North Star management maintains as a long-term target, the key swing factor into Q3 FY27 — DMart's seasonally strongest, festive quarter — is whether operating leverage from festive footfall offsets the employee-cost and finance-cost drag seen this quarter.