Bajaj Electricals: CP turns EBIT-positive, consol PAT ₹48 Cr; revenue growth soft at 2.3%
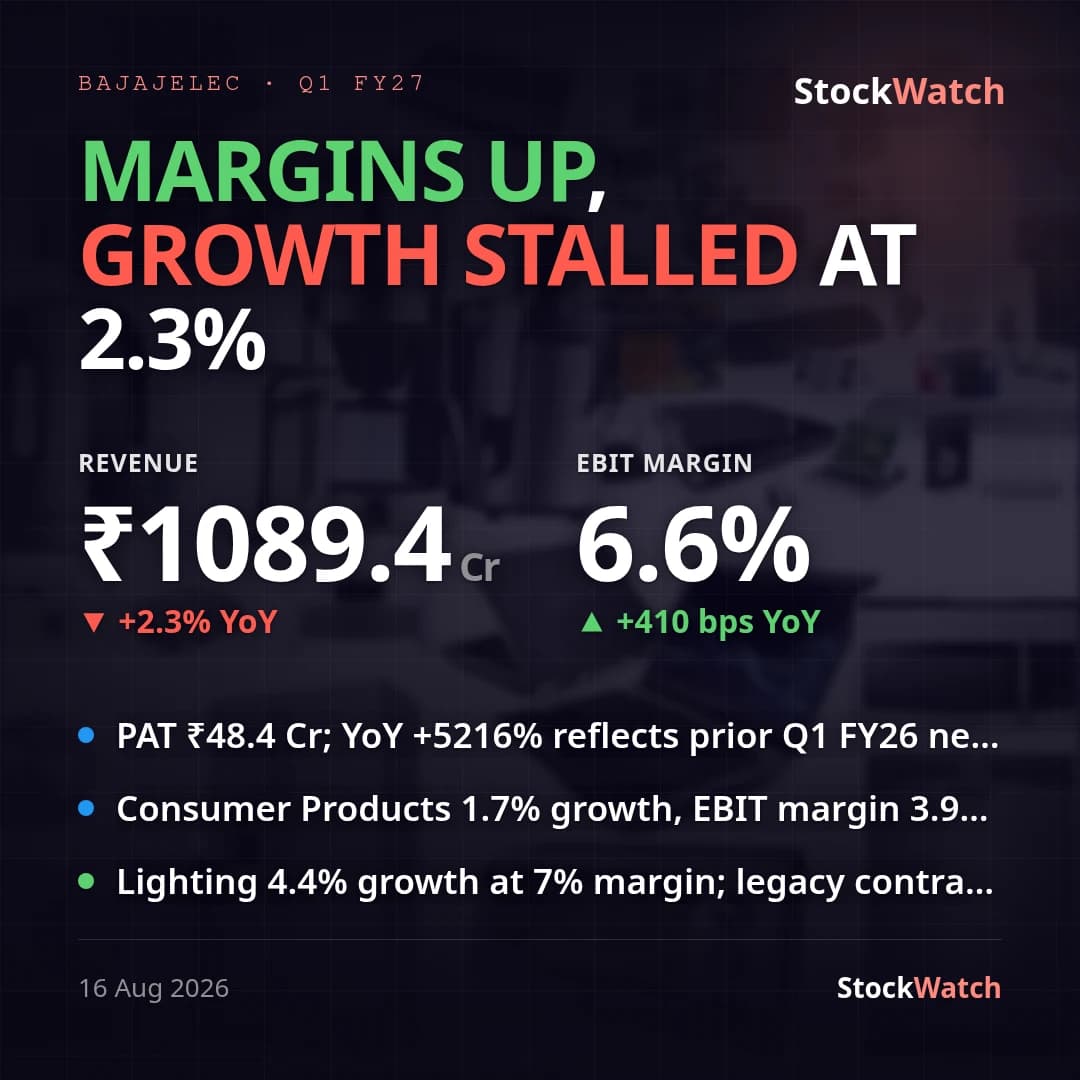
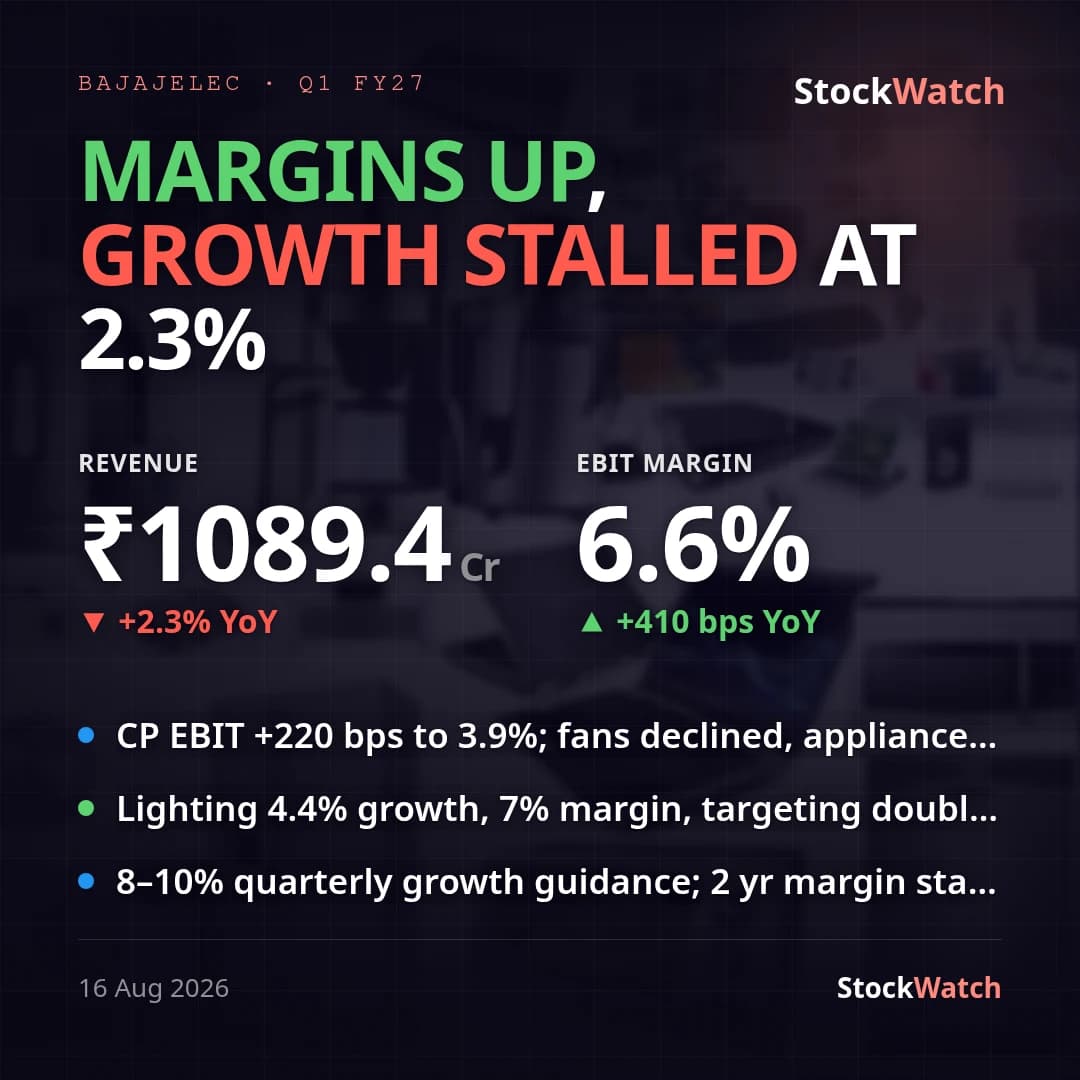
Bajaj Electricals reported consolidated revenue of ₹1,089.4 Cr for Q1 FY27, up 2.3% YoY from ₹1,064.6 Cr, and consolidated PAT of ₹48.4 Cr against ₹0.9 Cr a year ago (standalone PAT ₹48.0 Cr — standalone and consolidated tell the same story this quarter, with the divergence limited to the associate/JV share of ₹0.43 Cr). PBT jumped to ₹65.7 Cr from ₹1.5 Cr YoY. No external consensus estimates for this specific print turned up in a web search, so vsStreet is marked unknown rather than assumed.
The swing was driven almost entirely by Consumer Products (CP), which turned EBIT-positive at a 3.9% margin (₹32.4 Cr) versus a ₹13.6 Cr loss (-1.7% margin) in Q1FY26, even as CP revenue grew just 1.7% YoY to ₹820 Cr — margin recovery, not volume growth, did the work. Lighting Solutions (LS) grew revenue 4.4% YoY to ₹269 Cr, but its EBIT fell to ₹17.9 Cr (6.7% margin) from ₹27.2 Cr (10.5% margin) — a clear compression that runs counter to management's prior guidance of "steady revenue growth and stable EBIT margins" for the vertical. Company-wide EBIT margin (ex-exceptional items) came in at 6.6%, up sharply from roughly 0.8% a year ago and already close to the 6-9% band management had targeted for FY28-29. The quarter carries a ₹8.78 Cr one-off gain on sale of immovable property, against a ₹6.68 Cr one-off Nashik factory ex-gratia charge in the year-ago quarter; adjusting for both, consolidated PAT still rose roughly 422% YoY, though off a low ₹7.6 Cr adjusted base — so the headline growth rate is real but exaggerated by how close to breakeven the year-ago quarter was.
Against the prior concall's guidance — CP to "bounce back in FY27" on kitchen appliances and fixes to fans/BLDC, LS to deliver steady growth with stable margins, and overall growth "ahead of market" at mid-single digits — this is a mixed scorecard: CP's EBIT turnaround materialized largely as flagged, but revenue growth of 2.3% trails the mid-single-digit ambition and LS margins compressed rather than held steady. Sequentially, revenue fell 12.1% QoQ from ₹1,239.5 Cr and PAT swung from a ₹67.5 Cr loss to a ₹48.4 Cr profit — but the Q4 loss was itself driven by ₹55.6 Cr of exceptional impairment charges (goodwill and moulds/dies) rather than a genuine slowdown, and Q4-Q1 both sit inside India's summer demand window, so this QoQ swing reads as a one-off/base effect rather than a trend and is not the headline. The same board meeting appointed Krishnan Sundaram (ex-HUL, ex-Vini Cosmetics) as Chief Growth & New Business Officer effective August 11, and approved expanding the ESOP pool from 5.76 lakh to 30.03 lakh options, alongside a revised whole-time-director remuneration structure — none of these carry a P&L impact this quarter.
Chairman Shekhar Bajaj called it "a strong start to the year" despite "input cost inflation, uneven summer demand, and industry-wide price increases," while MD & CEO Sanjay Sachdeva attributed the CP turnaround to "strategic actions, margin expansion, and operating leverage" and noted LS's 4.4% growth came "on a strong base" — management's own framing implicitly concedes the LS margin softness even while spotlighting the CP recovery. Going into Q2, the key question is whether CP can sustain EBIT-positive economics without one-off support, and whether LS can arrest the margin slide shown this quarter.