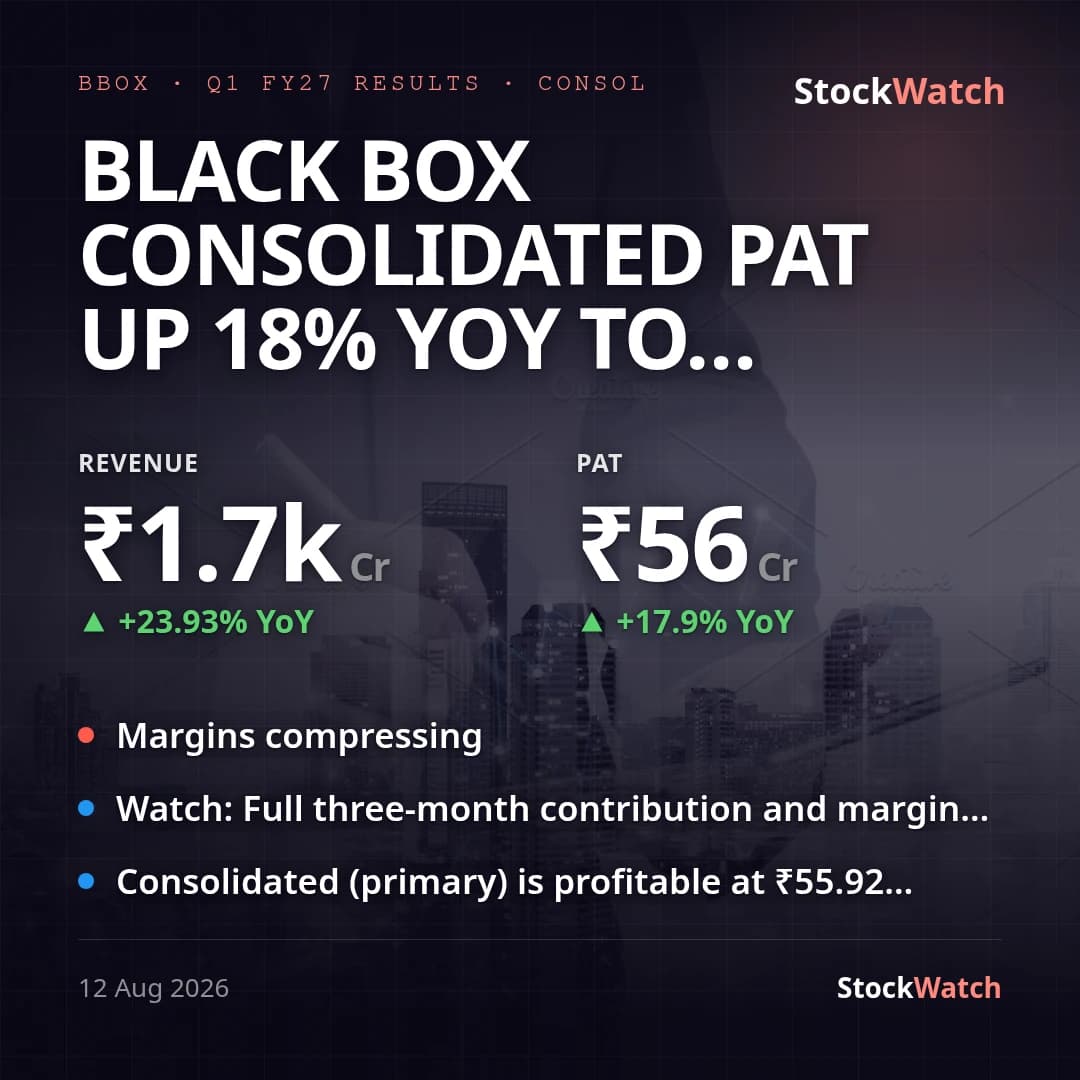
Black Box consolidated PAT up 18% YoY to ₹56 Cr on 24% revenue growth; NPM slips to 3.3%
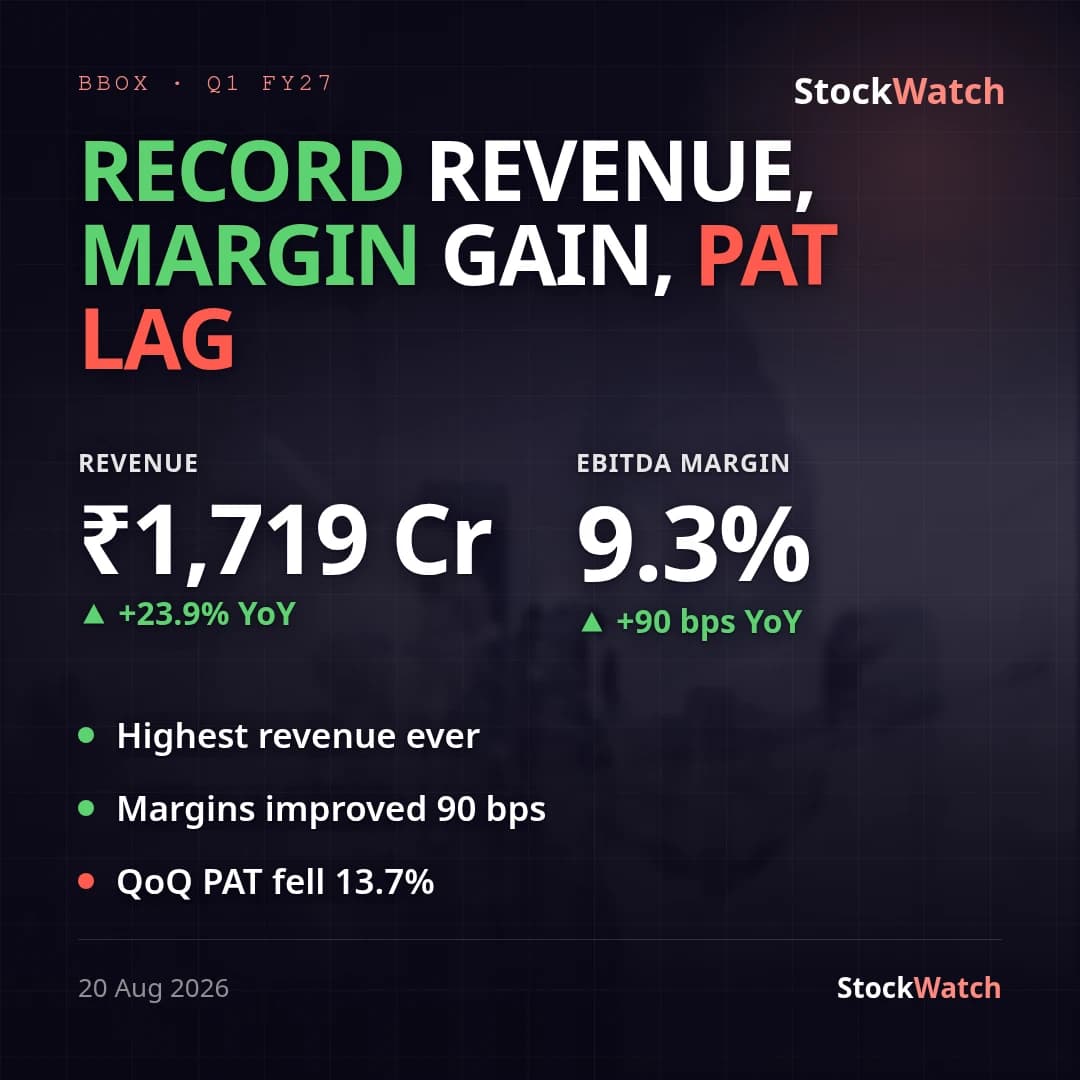
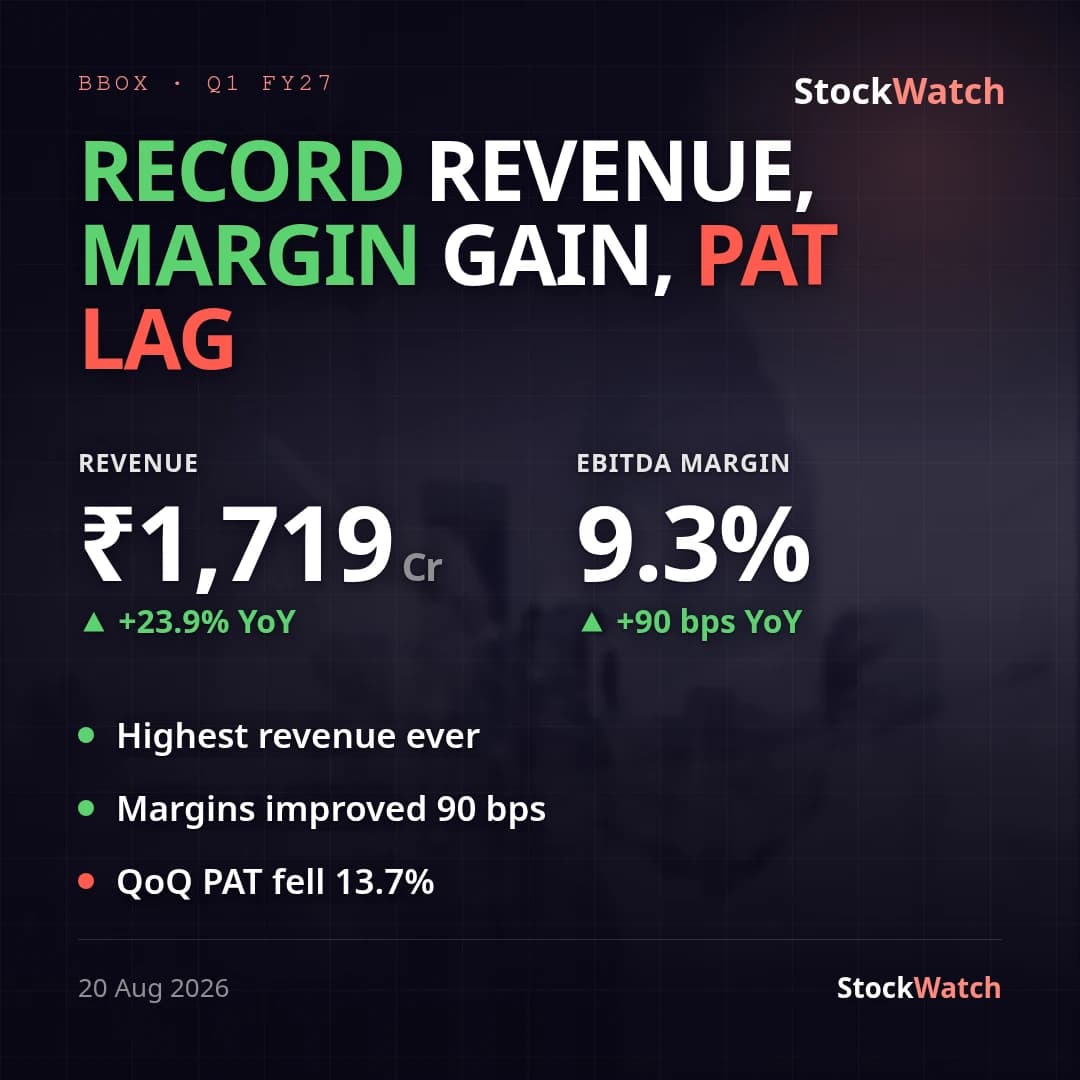
Black Box's consolidated (primary) revenue for Q1 FY27 (quarter ended June 30, 2026) came in at ₹1,718.50 Cr, up 23.9% YoY from ₹1,386.74 Cr and up a modest 1.6% QoQ from ₹1,690.94 Cr. Consolidated PAT was ₹55.92 Cr, up 17.9% YoY on a reported basis (~24.6% YoY on an adjusted basis excluding exceptional items on both sides — ₹18.91 Cr of severance/lease-foreclosure charges this quarter vs ₹12.60 Cr a year ago) but down 13.7% sequentially from ₹64.76 Cr. Basic EPS was ₹3.15 (₹4.21 before exceptional items) against ₹2.80 in Q1 FY26 and ₹3.78 in Q4 FY26. Net profit margin slipped to 3.25% from 3.42% YoY and 3.83% QoQ.
Topline growth was led by System Integration (+21.6% YoY to ₹1,412.54 Cr) and Technology Product Solutions (+41.6% YoY to ₹267.06 Cr), and includes roughly two months of inorganic contribution from the 2S Inovações Tecnológicas (Brazil) acquisition completed May 1, 2026 for ₹496.59 Cr; stripping an estimated ~₹83 Cr of 2S revenue still leaves organic growth near 18% YoY. At the operating level, segment results improved to ₹113.34 Cr (6.6% of revenue) from ₹78.23 Cr (5.6%) a year ago, but that gain was offset below the line: finance costs jumped 43% YoY to ₹48.00 Cr (from ₹33.58 Cr), largely funding the acquisition, while exceptional severance/lease charges rose to ₹18.91 Cr. Technology Product Solutions stayed loss-making, with its segment loss widening to ₹(14.11) Cr from ₹(6.28) Cr YoY. Standalone results were weaker still — a ₹2.40 Cr loss (EPS -₹0.14) versus a ₹1.16 Cr profit a year ago.
Revenue growth of 23.9% YoY (~18% ex-acquisition) exceeds the 12-15% organic growth range management has targeted for FY27, and stays consistent with the FY30 roadmap laid out on the Q1 FY26 call (₹18,000 Cr revenue by FY30, split ₹12,000 Cr organic/₹6,000 Cr inorganic, 10%+ EBITDA margins). No formal quarterly guidance figure or a confirmed published Street consensus for this specific print could be found — brokerage previews (CompoundingAI) flagged the 2S Brazil contribution and working-capital normalization as the quarter's watch items rather than giving point estimates, so vsStreet is unknown. No separate management press release commentary was captured alongside this filing; the notes instead flag FEMA-related remittance delays (₹20.95 Cr consolidated, procedural per the auditor) and confirm the New Labour Code impact already booked in FY26. The Board also fixed August 28, 2026 as the record date for the ₹1/share final FY26 dividend and set the 40th AGM for September 16, 2026.
Going into Q2 FY27, the print sets up two things to track: whether the full-quarter contribution from 2S Brazil proves margin-accretive as management has indicated, and whether finance costs stabilize once acquisition funding normalizes — both will decide whether NPM recovers toward last year's 3.4-3.8% range or stays compressed near 3.25%.