CESC's consolidated revenue came in at ₹5,607 Cr for Q2 FY27, up 6.5% YoY (₹5,267 Cr) and 2.2% QoQ (₹5,485 Cr), but consolidated PAT of ₹438 Cr slipped ~2% YoY against our on-file base of ₹445 Cr (the filing's own restated comparative shows ₹448 Cr) even as it rose 4.5% QoQ from ₹419 Cr. Owners' share of profit was ₹423 Cr (EPS ₹3.20, versus ₹3.21 a year ago and ₹3.03 in Q1 FY27); non-controlling interest took ₹15 Cr. On the standalone (core generation-distribution) book, PAT was ₹256 Cr on revenue of ₹2,854 Cr, EPS ₹1.93 — no standalone baseline is on file to compute its own YoY/QoQ trend.
The gap between revenue and profit growth sits squarely in the cost line: consolidated cost of energy purchased rose 14.2% YoY to ₹2,566 Cr (from ₹2,246 Cr), well ahead of the 6.5% revenue increase, pulling operating profit margin down to roughly 15.0% (PBT + finance cost − other income, over revenue) from about 20.1% a year ago and 16.3% in Q1 FY27. Net profit margin followed the same YoY pattern — 7.70% versus 8.21% a year ago — though it did tick up sequentially from 7.30% in Q1 FY27, a QoQ improvement that does not offset the YoY squeeze and should not be read as a trend reversal. Regulatory income (net) added ₹99 Cr to PBT this quarter versus ₹72 Cr a year ago and ₹180 Cr in Q1 FY27; these FPPAS-linked true-ups under the WBERC tariff mechanism (notes 3 and 7) are a recurring, not one-off, swing factor in CESC's quarterly PBT bridge.
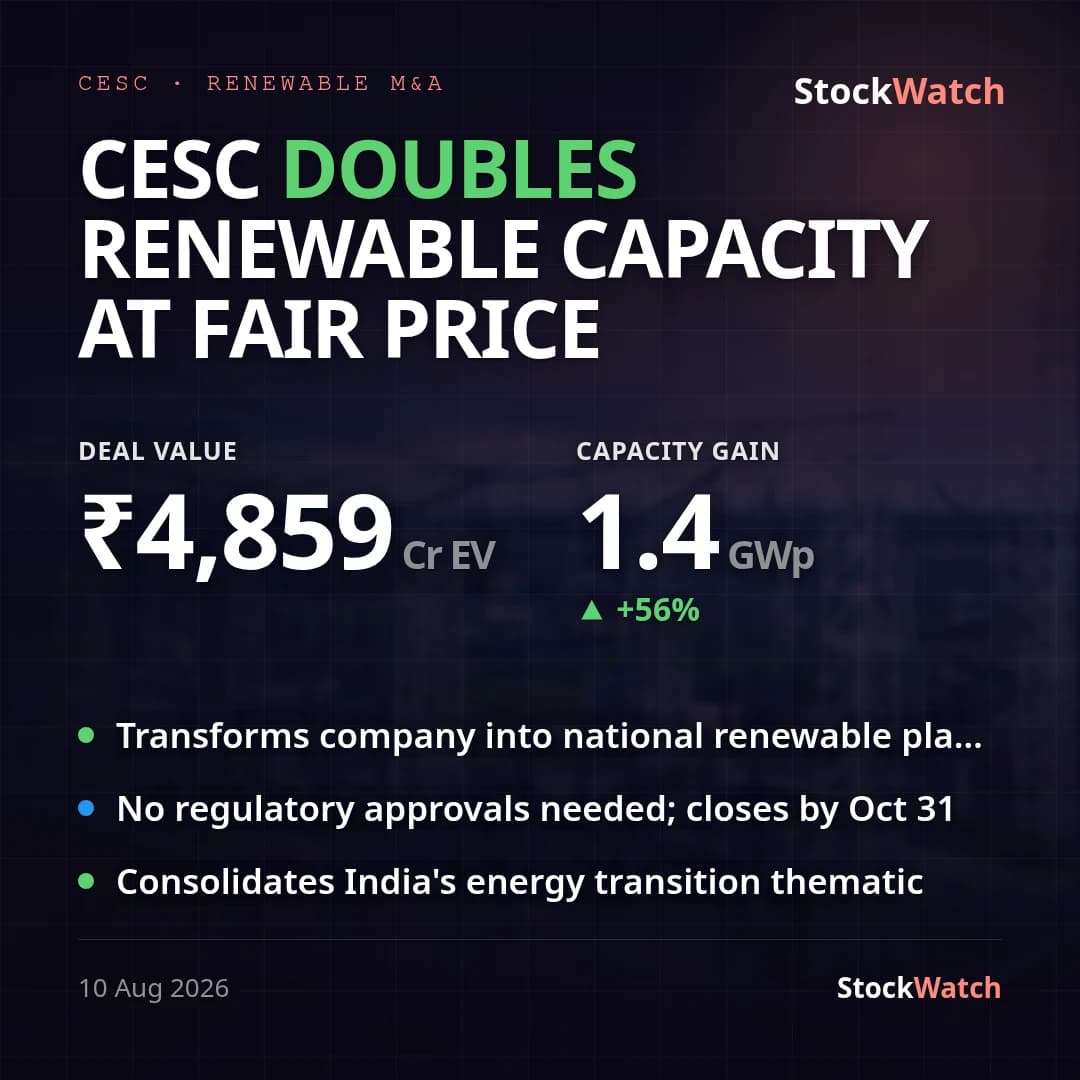
No analyst consensus or brokerage preview specific to this quarter turned up in a web search — coverage found was limited to Q1 FY27 commentary — so vsStreet is unknown; management has also not placed any formal forward guidance on record, and no separate press-release commentary beyond the board-outcome letter was available to reconcile against the print. On the corporate-action side, the company allotted ₹190 Cr of debt securities to Kotak Mahindra Bank on 24 September (following board approval on 22 September), consistent with ₹1,241 Cr of fresh non-current borrowings raised across H1 FY27 per the cash-flow statement; a subsidiary signed a power deal and invested in a wind project (25 September), and PGPPL's share-purchase agreement to acquire 100% of several ReNew renewable entities (note 13) saw its subsidiary's acquisition timeline pushed to 21 November. An interim dividend of ₹6 per share was paid during the quarter (note 10).
Consolidated non-current borrowings rose to ₹16,183 Cr from ₹15,292 Cr at FY26-end, while other equity dipped to ₹12,335 Cr from ₹12,397 Cr. H1 FY27 operating cash flow of ₹1,384 Cr was outpaced by ₹1,973 Cr of investing outflow (₹2,010 Cr capex) and ₹855 Cr of financing outflow, leaving cash down ₹1,444 Cr to ₹2,764 Cr at half-year close — a funding profile that sets up continued reliance on fresh borrowings alongside the pending renewable-asset acquisition.