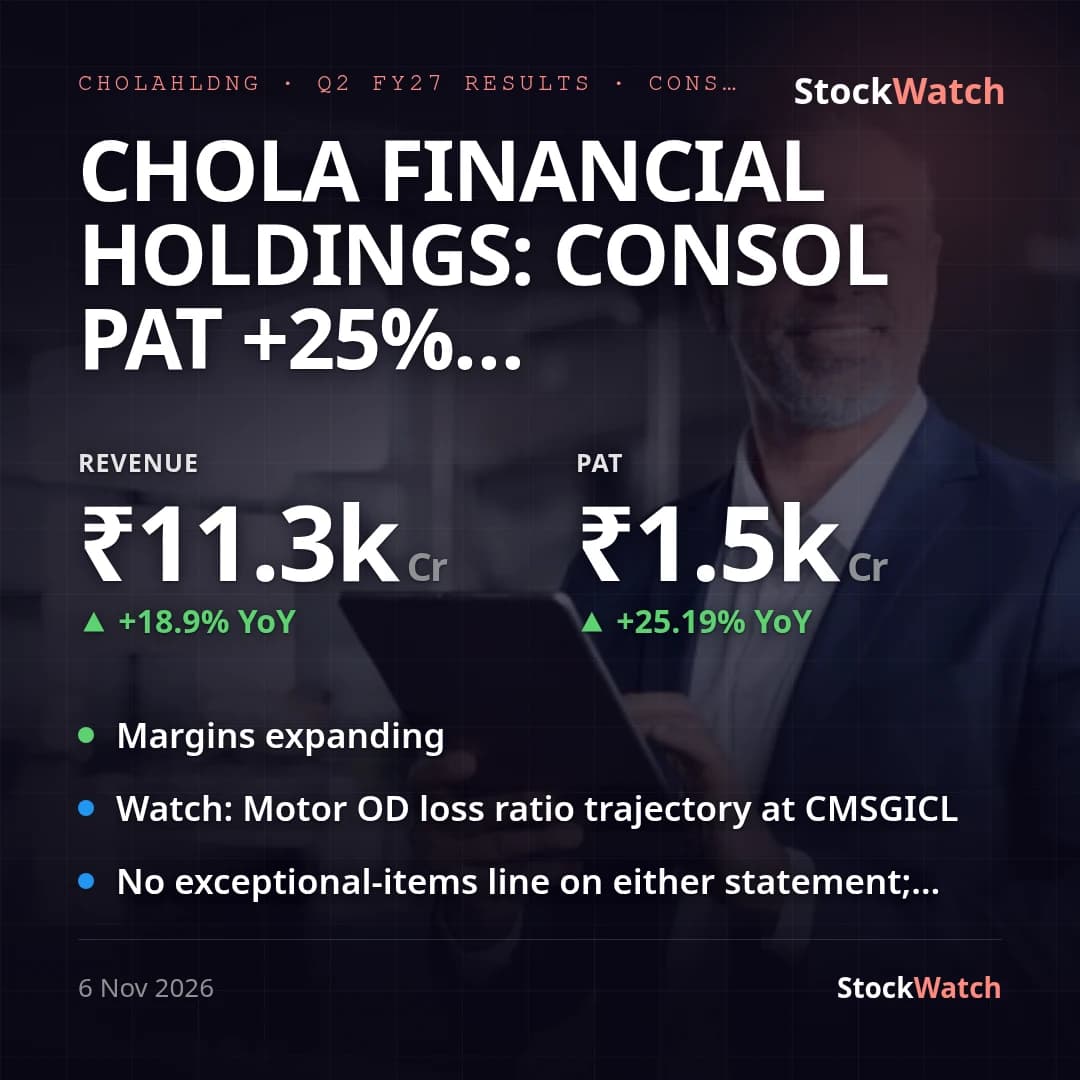
Chola Financial Holdings: consol PAT +25% YoY to ₹1,520 Cr, NBFC offsets insurer loss
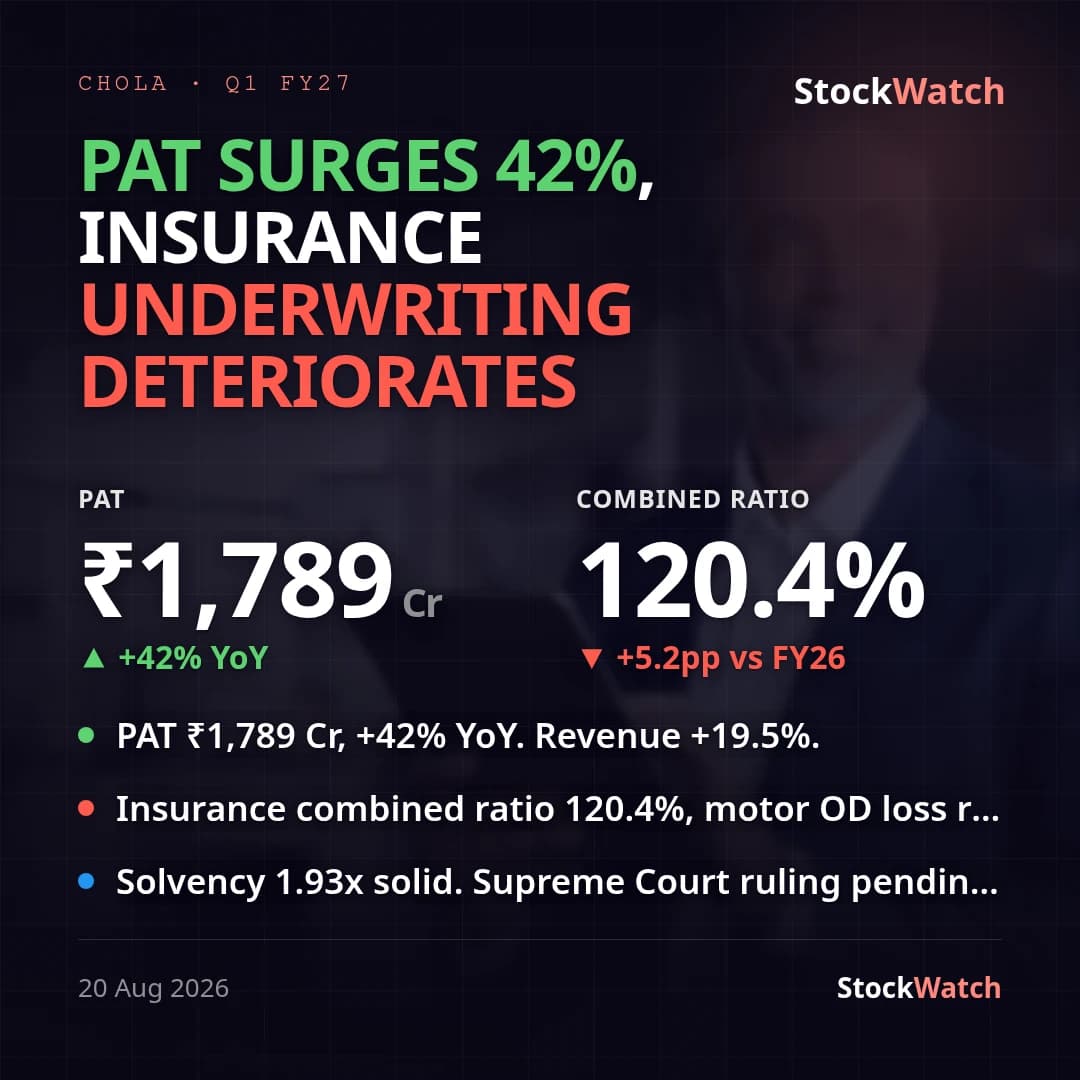
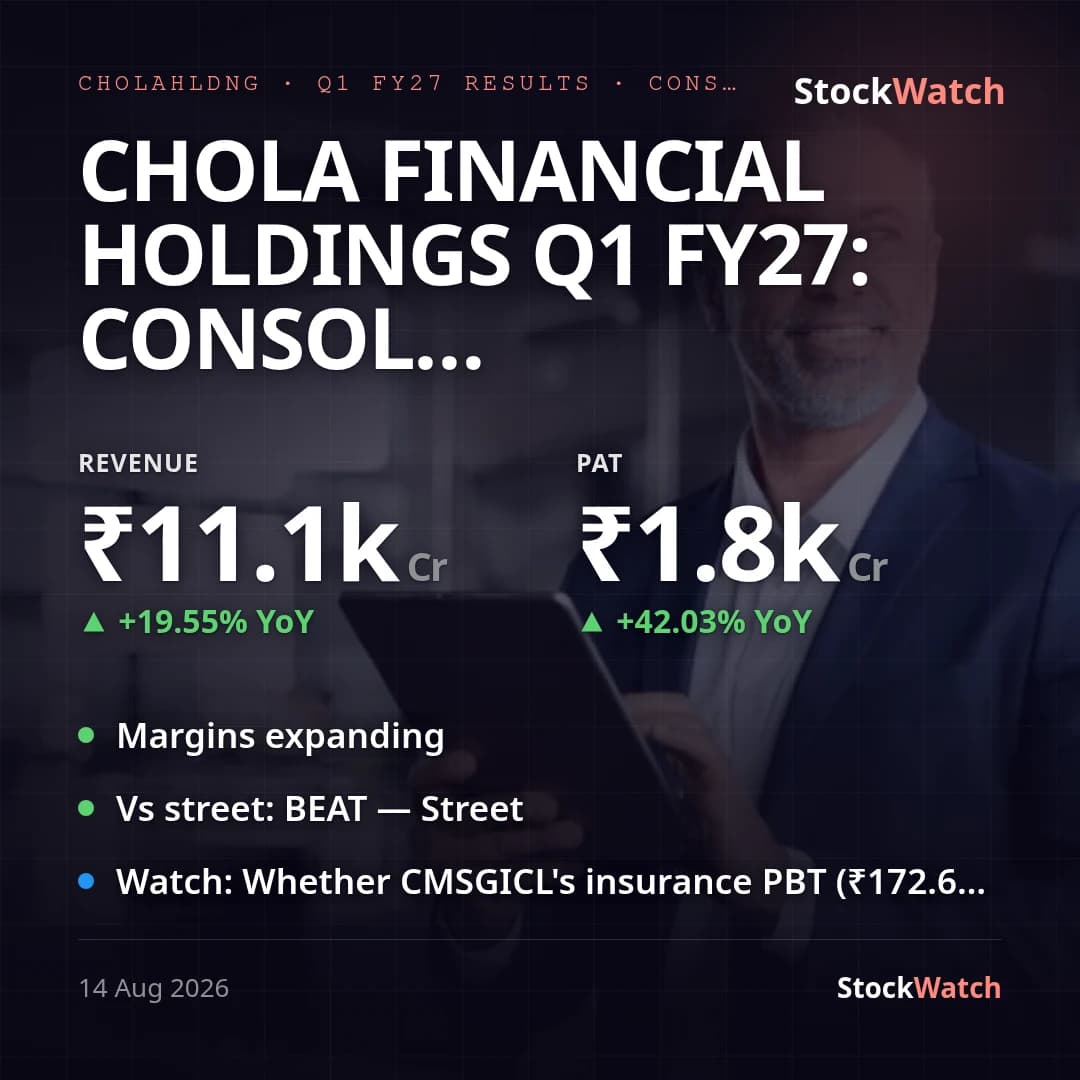
On a consolidated basis (primary, per CFHL's group structure), Cholamandalam Financial Holdings reported PAT of ₹1,520 Cr for Q2 FY27, up 25% YoY from ₹1,214 Cr, on consolidated total income of ₹11,388 Cr, up 19% YoY from ₹9,578 Cr. Sequentially PAT fell 15% from Q1 FY27's ₹1,789 Cr — a reversal driven almost entirely by the insurance subsidiary, not the core lending franchise. Standalone (holdco-only) PAT was ₹27.89 Cr versus ₹27.16 Cr a year ago, essentially flat, as expected for a dividend/service-fee-driven parent entity; the consolidated print is what matters for the group story. No exceptional item appears on the face of either P&L this quarter or last, so no formal adjusted-growth figure applies.
NBFC subsidiary CIFCL (CFHL holds ~43.48%) remained the growth engine: standalone PAT rose 41% YoY to ₹1,630 Cr on disbursements up 47% YoY to ₹35,872 Cr and AUM up 23% YoY to ₹2,68,009 Cr, with Financing segment PBT at ₹2,187 Cr (+40% YoY). That strength was partly offset by CMSGICL (general insurance, ~60% stake), which swung to a ₹120 Cr post-tax loss versus a ₹46 Cr profit a year ago — H1 FY27 PAT collapsed to ₹8 Cr from ₹165 Cr — on NATCAT (natural catastrophe) claims in H1 FY27 and elevated Motor OD claims experience; segment PBT for Insurance moved to a ₹169 Cr loss from a ₹62 Cr profit a year ago. Consolidated NPM was 13.35%, up modestly from 12.68% a year ago but down sharply from ~16.0% in Q1 FY27 — the sequential compression is the insurance loss flowing into the group number.
Against management's own prior guidance (Aug 2026 call), CFHL/CIFCL had targeted bringing the Motor OD loss ratio down to the high-70s "over a couple of quarters," with no firm date; this quarter's elevated claims and the insurer's swing to a loss indicate that improvement has not yet shown up, an early miss against the guided direction even allowing for the open timeline. Management had also flagged that clarity on the IFRS transition (effective April 1, 2027) was expected this quarter; this filing and the accompanying press release carry no update on that front. No specific pre-result street consensus for CFHL's or CIFCL's Q2 FY27 PAT could be located, so vsStreet is unknown; available post-result brokerage coverage (e.g., PL) confirms the reported numbers rather than a prior estimate. Among the quarter's other developments, CMSGICL's own press release disclosed an investment book of ₹18,937 Cr and 7% YoY GWP growth to ₹2,429 Cr even as underwriting profitability fell; a 0.016% stake pickup by Bandhan MF and the routine trading-window closure are not financially material.
The quarter cements CIFCL as the dominant and still-accelerating profit driver within the group, while CMSGICL's insurance book has become the swing factor on consolidated profitability — its claims experience, not the NBFC franchise, pulled PAT down sequentially from Q1 FY27's record ₹1,789 Cr. The next checkpoints are whether CMSGICL's claims normalize in H2 FY27 and whether the previously guided Motor OD loss-ratio improvement becomes visible in Q3 FY27.