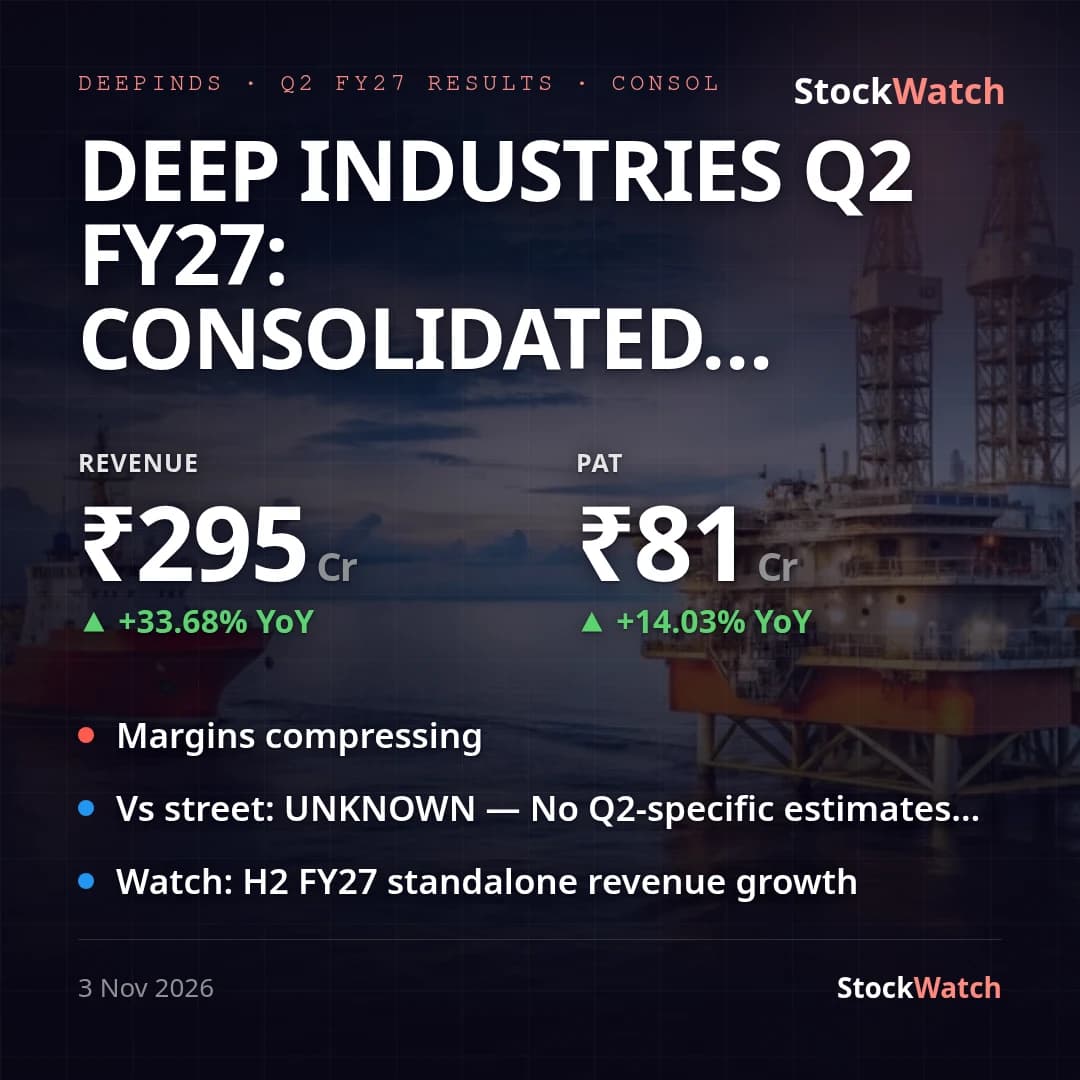
Deep Industries Q2 FY27: consolidated revenue +34% YoY outpaces 14% PAT growth as margins compress
Deep Industries' consolidated revenue rose 33.7% YoY to ₹295.43 Cr (+5.9% QoQ), comfortably ahead of management's FY27 guidance of >25% consolidated growth — H1 FY27 consolidated revenue is up 36.6% YoY, tracking well above plan. But consolidated net profit (₹81.22 Cr, including ₹4.73 Cr non-controlling interest) grew only 14.0% YoY and actually fell 8.9% QoQ from ₹89.14 Cr, meaning profit growth trailed revenue growth by a wide margin — this is a margin story, not a growth story. Operating margin (OPM) compressed to 36.0% from 41.5% a year ago and 38.8% last quarter; net margin fell to 25.9% from 29.4% on both counts. The squeeze sits on the cost-of-materials line: cost of materials consumed/purchase of stock-in-trade jumped to ₹151.66 Cr from ₹97.96 Cr a year ago, rising faster than revenue even as finance cost and depreciation stayed roughly flat.
On a standalone basis — secondary to consolidated per our basis convention — PAT grew 18.5% YoY to ₹59.37 Cr on revenue up 18.7% YoY, which actually sits within management's guided 18-20% standalone growth band for the quarter. The divergence is at the half-year level: standalone H1 revenue is up just 9.3% YoY against the 18-20% full-year guide, because Q1 FY27 standalone revenue was roughly flat YoY; Q2's in-band print is a partial catch-up, not a guidance beat, and H2 needs to accelerate meaningfully to close the gap. We found no quarter-specific Street estimates for Q2 FY27 (board meeting was only confirmed Oct 27 and results approved today); full-year FY27 consensus on aggregator data pegs revenue near ₹1,020 Cr and EPS near ₹48 (+53% YoY), but that is a full-year marker, not a Q2 beat/miss check, so vsStreet is marked unknown. Management's own Q2 press release was not available in our records to cross-check framing.
The quarter's one external catalyst was a ₹88.15 Cr gas compression order win from ONGC on September 8, 2026, which adds to the order book but had limited time to flow through Q2 revenue. H1 capex of ₹91.6 Cr is running behind the ₹250-300 Cr FY27 guided pace, leaving a steep back-half requirement if the full-year capex target is to be met. Against the FY28 PAT target of ₹500 Cr (vs ₹350 Cr expected FY27), H1 FY27 consolidated PAT of ₹170.37 Cr is roughly 49% of the FY27 expectation, which is on a plausible run-rate but will need H2 profit to outpace this quarter's QoQ dip to stay on track.