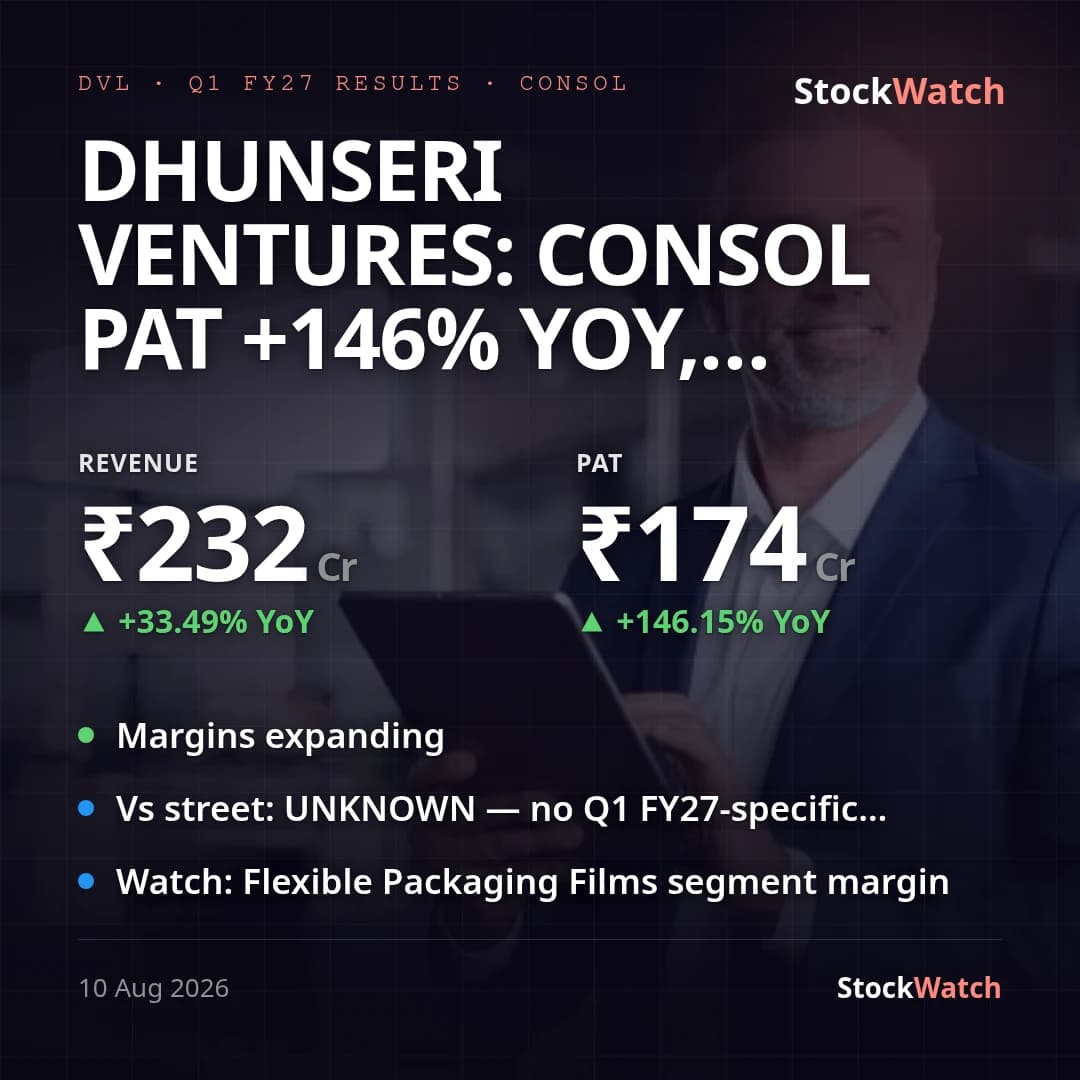
Dhunseri Ventures: Consol PAT +146% YoY, ~22% ex-JV surge; packaging margin thins
Dhunseri Ventures posted consolidated revenue of ₹231.59 Cr (+33.5% YoY, +226% QoQ) and consolidated PAT of ₹174.29 Cr for Q1 FY27, up 146% YoY from ₹70.81 Cr and over 6x QoQ from ₹24.36 Cr. The QoQ jump isn't comparable — Q4 FY26's base was depressed by a treasury mark-to-market loss. But even the YoY headline overstates underlying momentum: nearly the entire profit increase came from a jump in the share of profit from equity-accounted petrochemical JV associates (₹120.59 Cr this quarter vs ₹26.81 Cr a year ago, +350%), a line that sits below segment operating profit and is inherently lumpy. Stripped of that swing, core consolidated PAT grew a steadier ~22% YoY (₹53.70 Cr vs ₹44.00 Cr).
The margin picture is mixed once JV income is set aside. Reported net margin (PAT/total income) expanded to 68.0%, from 36.6% a year ago and 26.3% last quarter — but that ratio is inflated by associate income sitting outside 'total income' in the P&L presentation. The core Flexible Packaging Films segment, the company's actual manufacturing operation, tells the opposite story: segment revenue grew 72% YoY to ₹137.91 Cr, but segment profit fell 17% YoY to ₹4.12 Cr as margin compressed to 3.0%, down from 6.2% a year ago and 14.9% last quarter — a real cost/realization squeeze even as the topline grew. Treasury operations, the company's investment book, swung from a ₹66.55 Cr loss in Q4 FY26 to a ₹93.68 Cr gain this quarter (+17.4% YoY), adding further volatility to the consolidated bottom line.
Standalone and consolidated diverge materially, as expected for a holding company: standalone PAT rose just 5.8% YoY to ₹109.03 Cr (revenue +21.4% YoY to ₹154.93 Cr), while consolidated PAT surged 146% YoY — the gap sits entirely in subsidiary (Flexible Packaging Films) and associate-JV performance that standalone accounts don't capture. There is no formal management guidance on record and no analyst consensus estimate specific to this quarter could be found; the only broker commentary located frames a 3-6 month price target of ₹255 as contingent on Q1 FY27 'meeting expectations,' without a numerical estimate — so vsStreet is unknown. No management press release accompanying this filing was available to cross-check against the numbers. The FY26 full-year results (announced 27 July 2026) had carried the Twelve Cupcakes impairment and a discontinued-operations drag; both are fully absent this quarter.
Going into Q2 FY27, the Flexible Packaging Films margin trajectory is the key operating signal — whether the compression to 3.0% is a one-quarter cost/mix issue or a more durable squeeze. The associate JV income line, having swung from ₹26.8 Cr to ₹120.6 Cr YoY, is unlikely to repeat at this scale and should be watched for normalization. Treasury/investment gains, similarly mark-to-market driven, remain a source of quarter-to-quarter swing independent of the operating businesses.