DLF Q2 FY27: Headline PAT Up 10% on One-Off CCD Gain, Core Realty Profit Craters 73% YoY
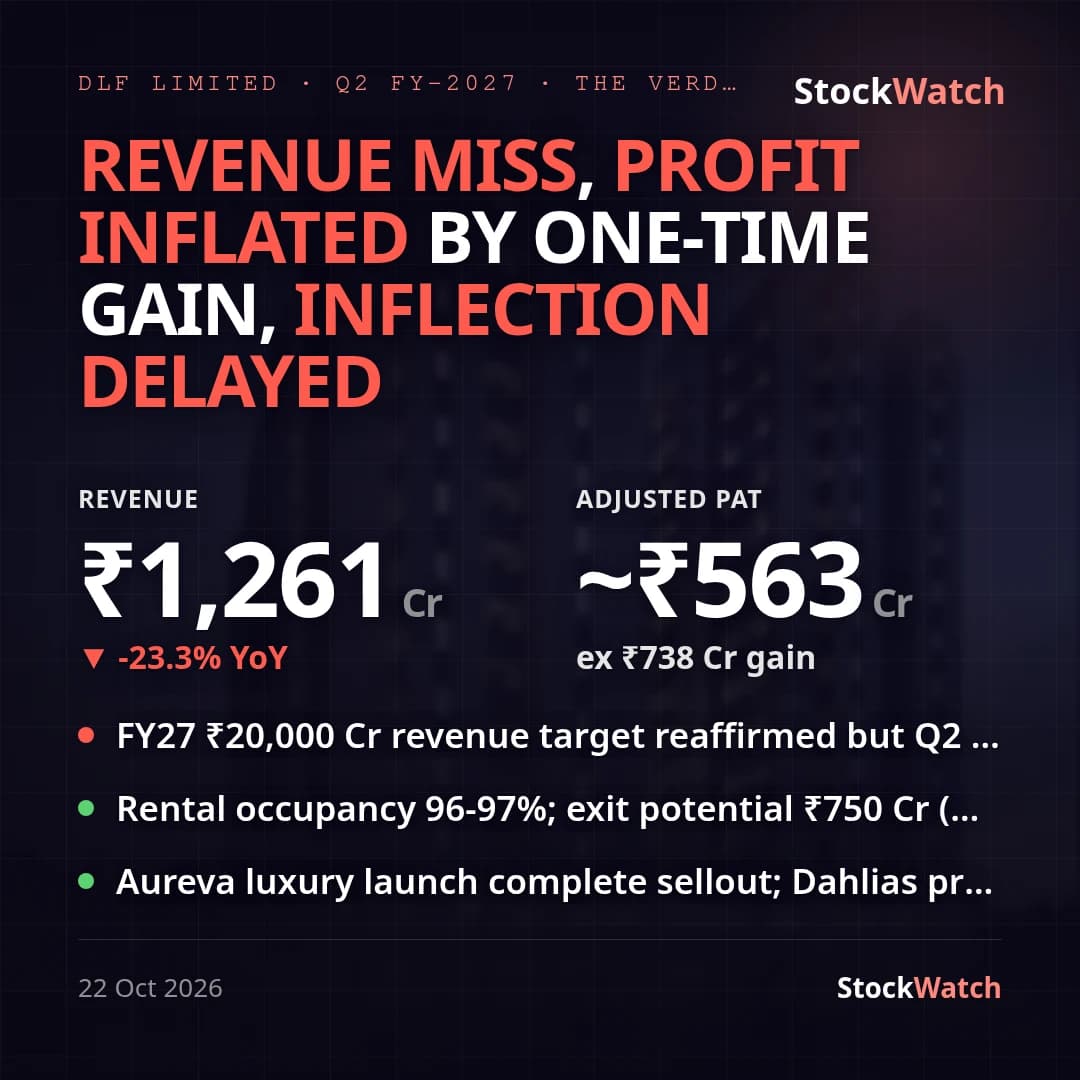
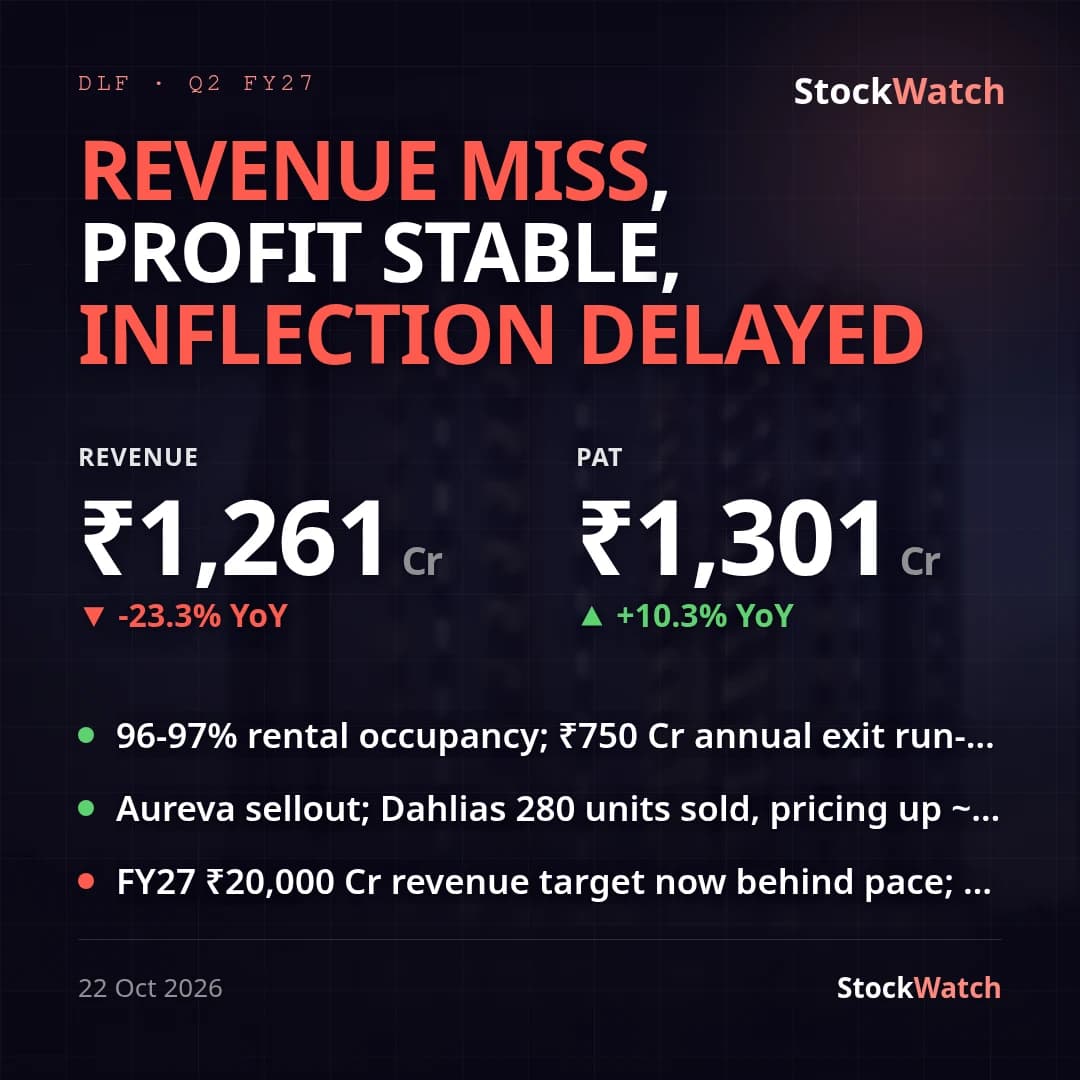
DLF's Q2 FY27 consolidated net profit was ₹1,301.35 Cr, up 10.3% YoY from ₹1,180.09 Cr and up 63.9% QoQ from ₹793.90 Cr, on revenue from operations of ₹1,260.58 Cr, down 23.3% YoY from ₹1,643.04 Cr and roughly flat QoQ (-1.5%) versus ₹1,280.34 Cr. The revenue print missed the Street's pre-result range of ₹1,400-1,500 Cr for the quarter. The headline profit beat is misleading: roughly ₹738.71 Cr of the ₹1,036.72 Cr consolidated other income is a one-off, non-cash fair-value gain on compulsorily convertible debentures that crossed their moratorium period (note 10), not operating earnings. Netting that out — and the year-ago quarter's own ₹235.19 Cr exceptional-item gain from an impairment reversal (notes 5/8) — adjusted PAT is down roughly 40% YoY rather than up 10%, a materially weaker picture than the reported number suggests.
The weakness sits squarely in the core Real Estate development segment: segment profit fell to ₹244.67 Cr from ₹899.47 Cr a year ago (-72.8%), far outpacing the 26.9% YoY drop in segment revenue (₹1,102.98 Cr vs ₹1,509.06 Cr), implying real margin compression on the completed-project mix. The Rental segment's reported profit of ₹854.04 Cr (vs ₹80.65 Cr YoY) is almost entirely the CCD fair-value gain flowing through that segment rather than underlying rental economics. Reported net margin of 56.7% (vs 52.2% YoY, 49.4% QoQ) is therefore a headline artifact, not an operating-margin improvement — on an adjusted basis, margins compressed.
Jefferies had cautioned ahead of this print that FY27 profitability would stay weak on low-margin legacy project completions, with recovery only from FY28; this quarter's core-segment collapse is consistent with that call, even as the broader Street consensus (23 analysts, Strong Buy, ₹815.30 average target) had modeled 27.6% full-year revenue growth to ₹10.45k Cr. Management gives no quarter-specific revenue or profit guidance in this filing; the only outlook on record is the prior concall's reaffirmed FY27 sales-bookings target of ₹20,000 Cr and an exit group-rental run-rate of ₹7,300-7,500 Cr — neither is checkable from this P&L, since bookings aren't disclosed here and DCCDL/JV rental income sits inside the ₹499.28 Cr share-of-JV-profit line (up from ₹411.56 Cr YoY) rather than segment revenue. This quarter's corporate activity — the ₹1,985 Cr sellout of the Aureva luxury retirement project (Oct 4) and a promoter reclassification request (Oct 7) — doesn't show up in this P&L given real estate revenue recognition lags bookings. Standalone PAT of ₹800.32 Cr (EPS ₹3.24) was driven mainly by ₹947.11 Cr of other income (dividend/interest from subsidiaries), so the standalone and consolidated prints tell different stories this quarter given the scale of the one-off gain at the group level.
Going into Q3, the key markers are whether core Real Estate segment profit recovers from this quarter's ₹244.67 Cr trough or stays depressed near it, and whether management reconciles H1 FY27's ₹2,540.92 Cr P&L revenue run-rate with the ₹20,000 Cr full-year bookings guidance on the next call.