Dr Lal PathLabs Q2 FY27: consolidated PAT +27% YoY, margins expand, beats growth guidance
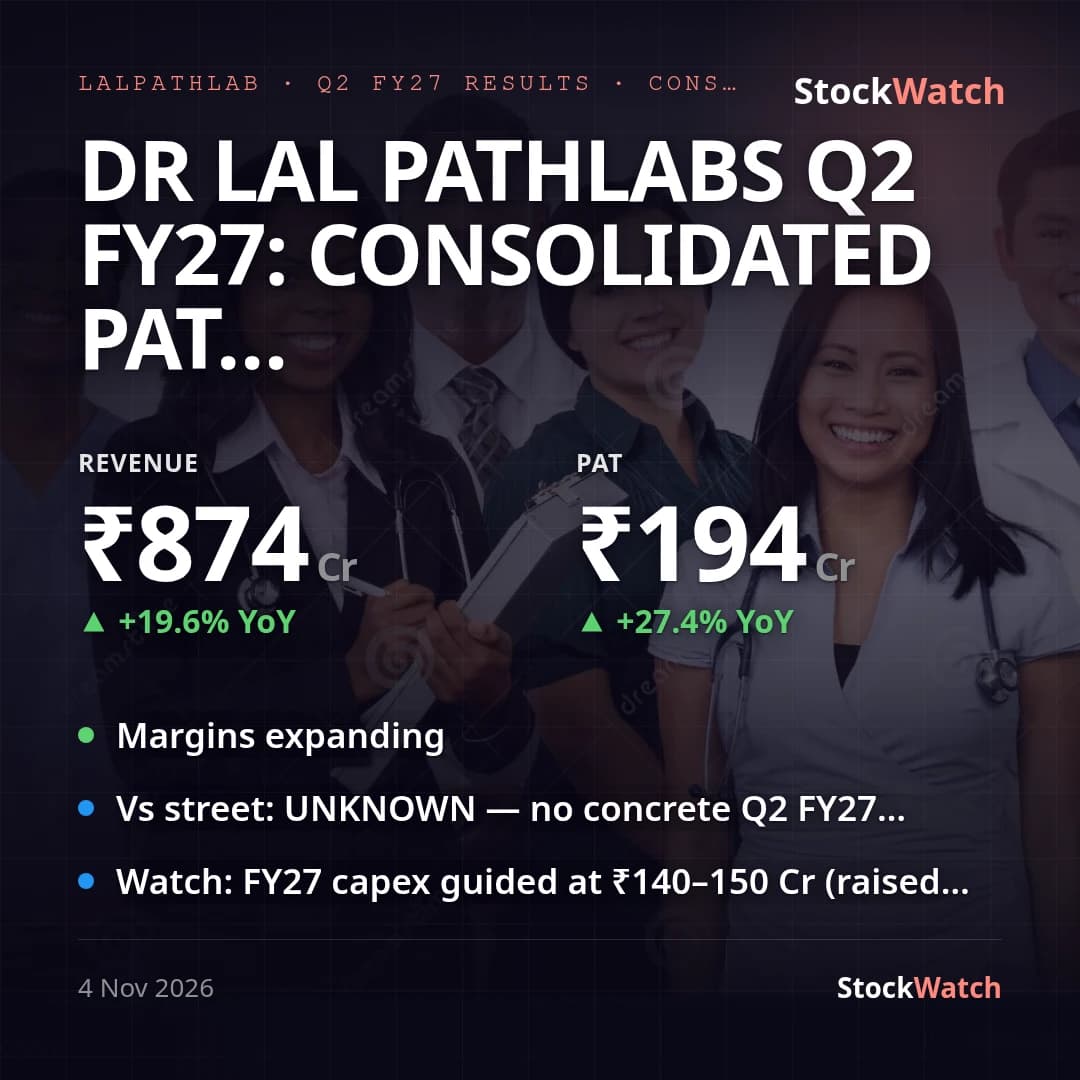
Dr. Lal PathLabs' consolidated revenue rose 19.6% YoY (9.5% QoQ) to ₹873.9 Cr in Q2 FY27, with consolidated PAT up 27.4% YoY (13.7% QoQ) to ₹193.9 Cr. There were no exceptional items in either this quarter or the year-ago quarter, so reported and underlying growth are identical — unlike FY26's full year, which carried a ₹30.1 Cr one-off Labour Codes charge. The print runs ahead of management's own guidance from the Q1 FY27 call, where revenue growth was informally upgraded to "trending mid-teens"; at 19.6% YoY, this quarter clears that bar comfortably and also accelerated from Q1's 19.1% YoY pace.
Margins expanded on both lines: operating margin (EBITDA excluding other income, over revenue) came in at 32.1%, up ~140 bps YoY and ~100 bps QoQ, while net margin rose to 21.4%, up 120 bps YoY and 80 bps QoQ. That expansion is notable because management had flagged no formal EBITDA margin upgrade last quarter, saying it would reinvest topline upside into expansion rather than bank it as margin — operating leverage from the higher revenue base evidently outpaced that reinvestment spend. Standalone PAT grew a slower 23.1% YoY to ₹179.7 Cr versus consolidated's 27.4%, a ~4-point gap pointing to a stronger contribution from subsidiaries this quarter (newly consolidated Shahbazkers Diagnostic Centre and the Ghana-based Sunshine Healthcare stake). Basic EPS was ₹11.51, on a post-bonus base of roughly 16.78 Cr shares following the December 2025 1:1 bonus issue.
No specific Street consensus estimate for this quarter could be located in available previews or brokerage notes, so this print cannot be benchmarked against a published number; full-year FY27 consensus EPS stood at ₹37.00 (+15.6%) ahead of this result, for context only. Management's own framing wasn't available beyond the procedural board-outcome letter — no press release commentary was furnished with this filing. The quarter was accompanied by continued inorganic activity: the Board approved up to ₹49.5 Cr of further investment in Dubai subsidiary LPL Dubai (which itself holds the Ghana stake); the company completed a 70% acquisition of SN Genelab for up to ₹168 Cr plus a ₹31.5 Cr earn-out (effective October 1); and a subsidiary spent ₹30.3 Cr to buy out the remaining 30% of Centrapath Labs, making it wholly owned. The Board also declared a second interim dividend of ₹5/share (record date November 11), taking FY27 interim payouts to ₹10/share so far. Separately, the Income Tax Department has filed an ITAT appeal against the company; no financial impact was quantified in the filing.
Going into H2 FY27, management's FY27 capex guidance of ₹140–150 Cr (raised from ₹100–120 Cr) and plans for 12–15 new labs and 3–4 radiology centers remain the stated roadmap, alongside its promise to reassess revenue/margin guidance from Q2 onward — a formal update, given this quarter's outperformance, is a logical next checkpoint. SN Gene and the Ghana business will also start contributing to consolidated numbers from Q3 FY27.