Edelweiss Q1 FY27: consolidated PAT (post-MI) jumps 83% YoY to ₹122 Cr as margins expand
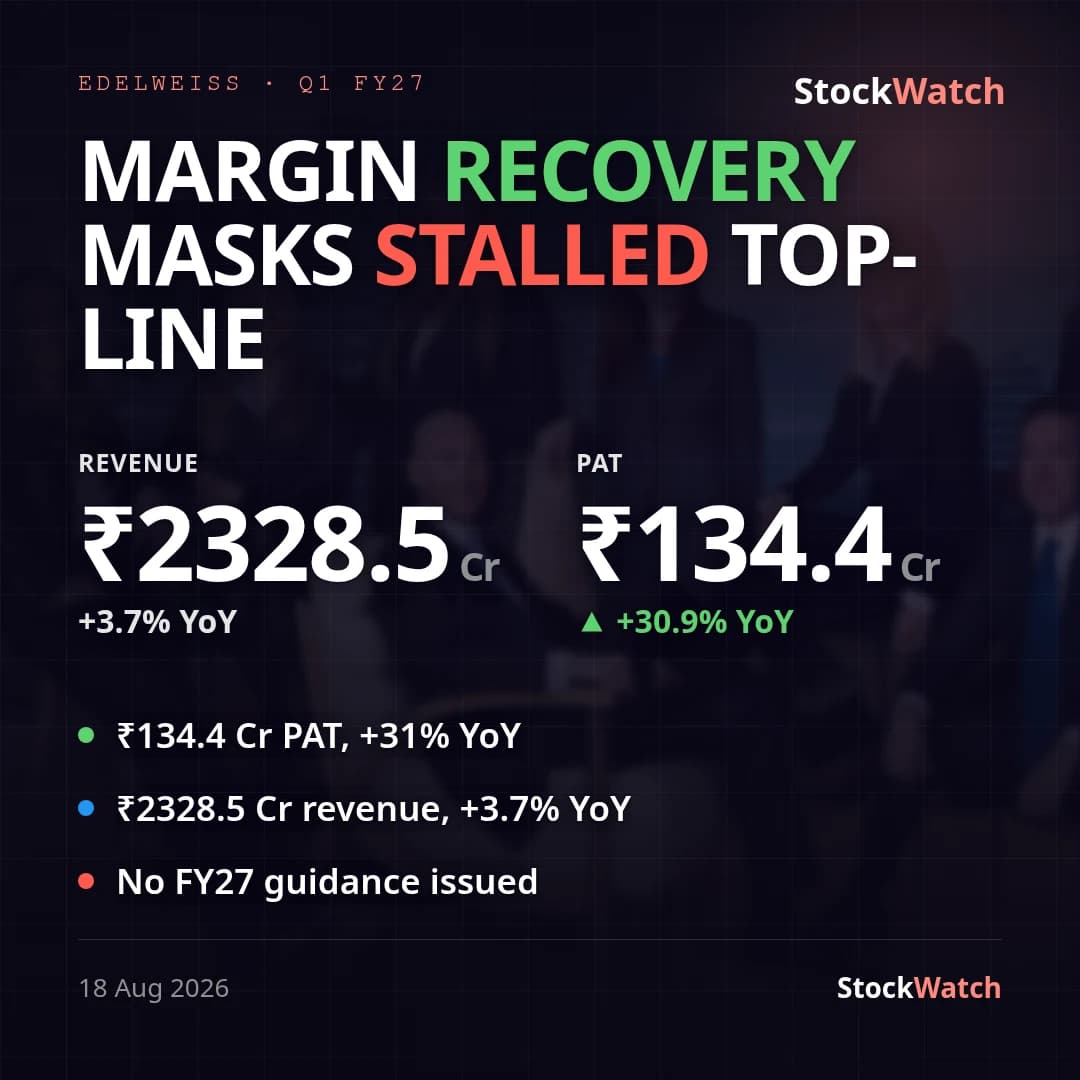
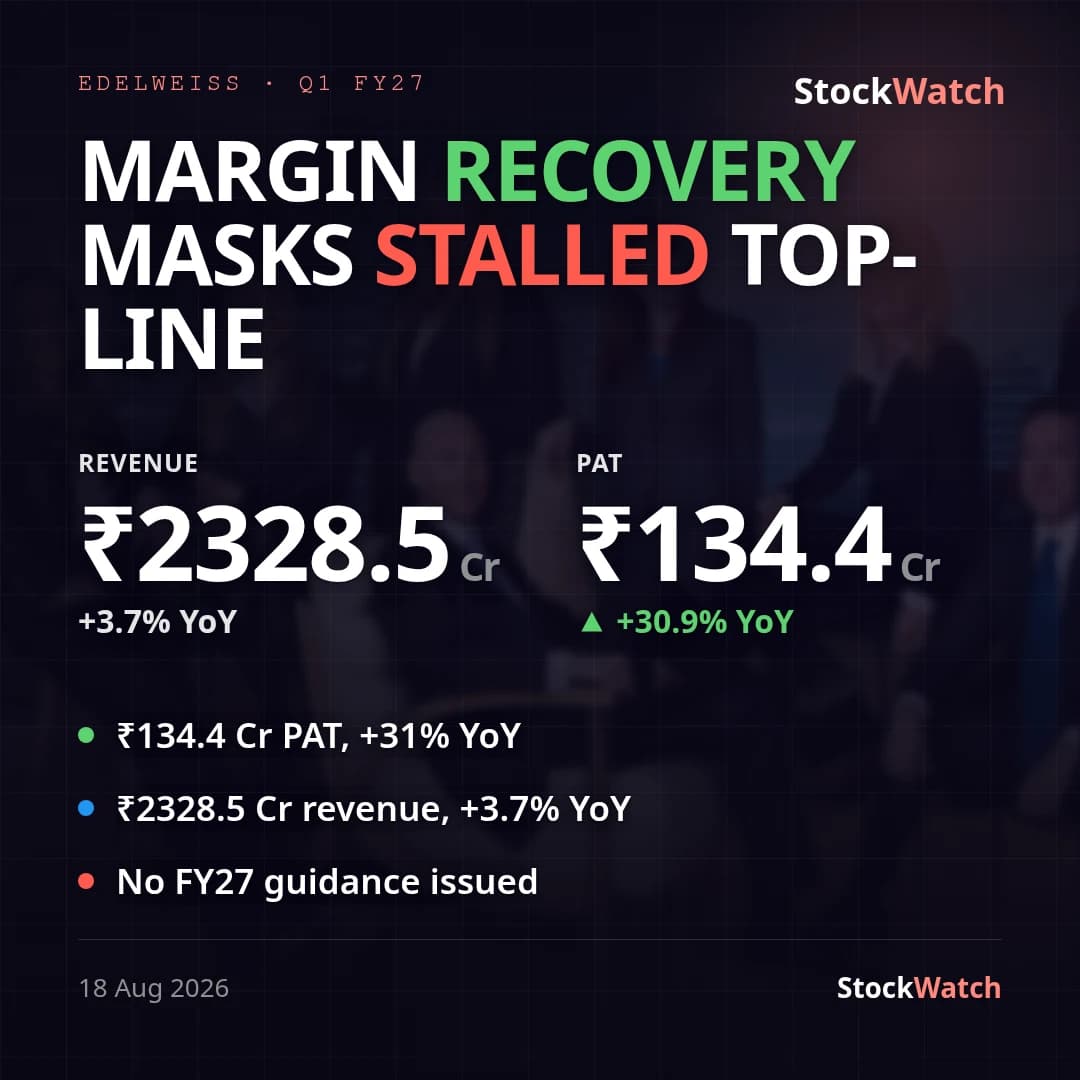
Edelweiss Financial Services' consolidated PAT attributable to owners (post minority interest) rose 83% YoY to ₹122.22 Cr in Q1 FY27 (quarter ended June 30, 2026), while the pre-minority 'net profit for the period' grew a more modest 31% YoY to ₹134.37 Cr — the gap reflects non-controlling interests shrinking to ₹12.15 Cr from ₹35.92 Cr a year ago as minority stakes in subsidiaries were pared down. Revenue from operations grew just 3.9% YoY to ₹2,328.50 Cr (₹2,241.51 Cr in Q1 FY26), so the profit jump was overwhelmingly a margin story rather than a topline one: consolidated net profit margin expanded to 5.56% from 4.50% YoY. There is no formal management guidance on record for this quarter, and no reliable street/consensus PAT estimate could be sourced for Q1 FY27 — Edelweiss does not appear to carry broad brokerage preview coverage — so vsStreet is marked unknown rather than inferred.
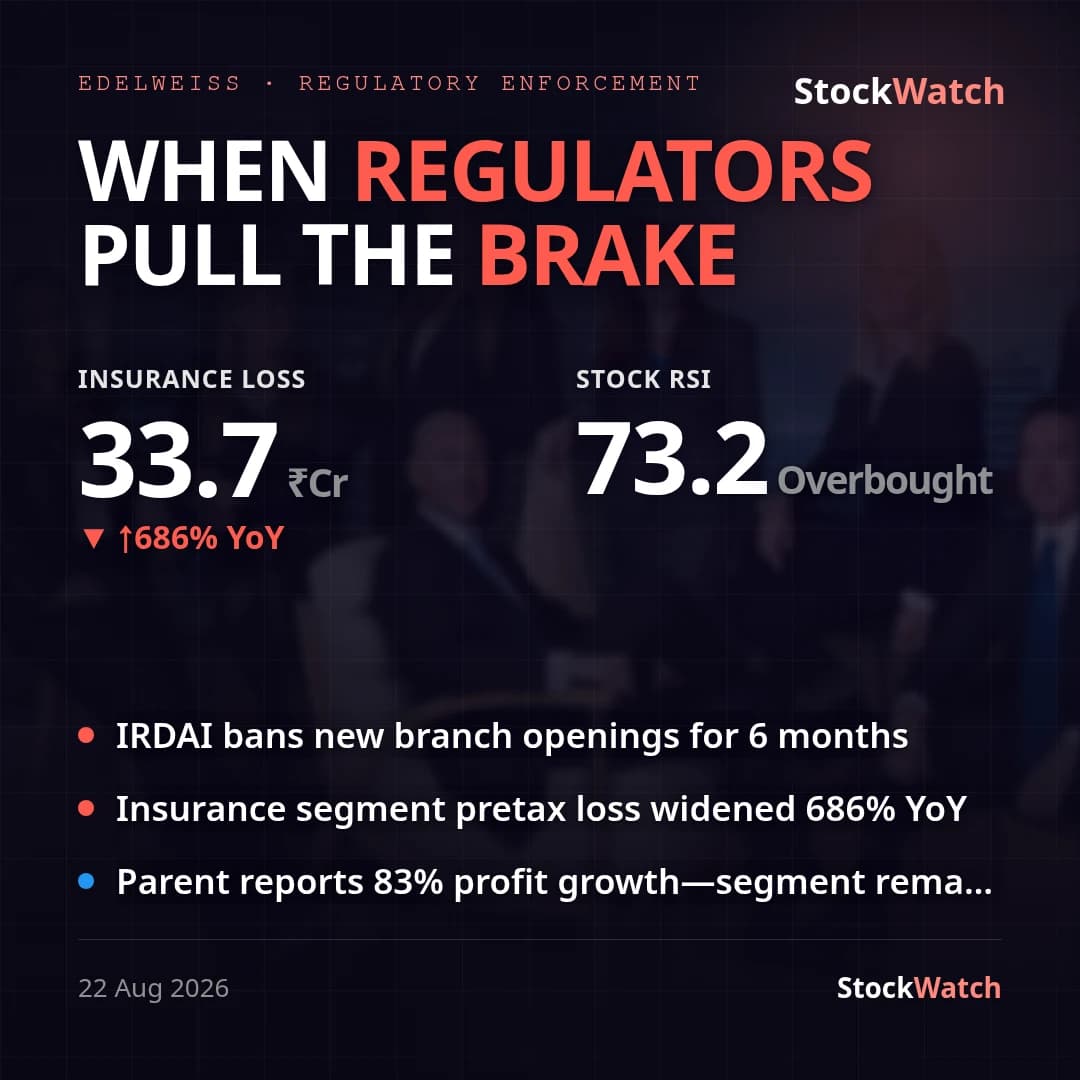
The PBT bridge shows the growth is partly structural. Pretax profit before share of associates was ₹89.11 Cr, down from ₹110.39 Cr a year ago, but the Group added ₹33.46 Cr of 'share of profit of associates' this quarter from Edelweiss Asset Management and Edelweiss Trusteeship — entities that moved to the equity method after the Group completed the sale of its remaining 5% stake in EAML & ETCL on June 29, 2026 (following an earlier 10% divestment in FY26). A year ago the same Mutual Fund business was still fully consolidated and contributed ₹33.80 Cr of segment PBT directly, so stripping out this reclassification, the core operating segments grew PBT roughly 16% YoY. Within segments, Alternative Asset Management was the standout — PBT up 36% YoY to ₹105.80 Cr on Fee Paying AUM up 27% YoY to ₹48,623 Cr — while the Insurance segment's pretax loss widened to ₹33.68 Cr from ₹4.28 Cr YoY even as General Insurance GWP grew 58% YoY, and the Capital business loss narrowed to ₹58.98 Cr from ₹122.46 Cr YoY. Sequentially, the Group swung from a ₹29.02 Cr consolidated pretax loss in Q4 FY26 to this quarter's ₹122.57 Cr profit, but that QoQ move is largely a mark-to-market artifact — Q4 carried a ₹235.05 Cr fair-value markdown on the proprietary book versus an ₹879.97 Cr fair-value gain this quarter — not an underlying operating turnaround.
At the standalone level, the holding company posted PAT of ₹69.88 Cr, up 6.9% YoY from ₹65.34 Cr, aided by a one-off ₹83.86 Cr dividend from Bonus Redeemable Preference Shares allotted by Edelweiss Asset Reconstruction Company, partly offset by a one-time ₹21.50 Cr employee incentive charge — neither figure recurs, so standalone growth should be read as noisy. The same board meeting that approved these results also cleared a fresh ₹1,000 Cr NCD public-issue plan, on top of a ₹300 Cr NCD tranche already raised in June 2026; consolidated debt-equity ticked up to 3.34x from 3.11x at FY26-end. Chairman Rashesh Shah's press-release framing — 'steady growth' anchored by Alternative Asset Management and Mutual Fund AUM expansion, Insurance 'on track' for breakeven, and Credit businesses on a 'calibrated scale up' — is broadly consistent with the numbers: AAM and MF grew fastest, the NBFC wholesale book kept shrinking (to ₹600 Cr from an ₹18,000 Cr March-2019 peak) while MSME disbursals rose 3x YoY to ₹353 Cr. One area the press release doesn't dwell on — the Insurance segment's PBT loss nearly doubling in absolute terms YoY — is the main unresolved item heading into Q2.