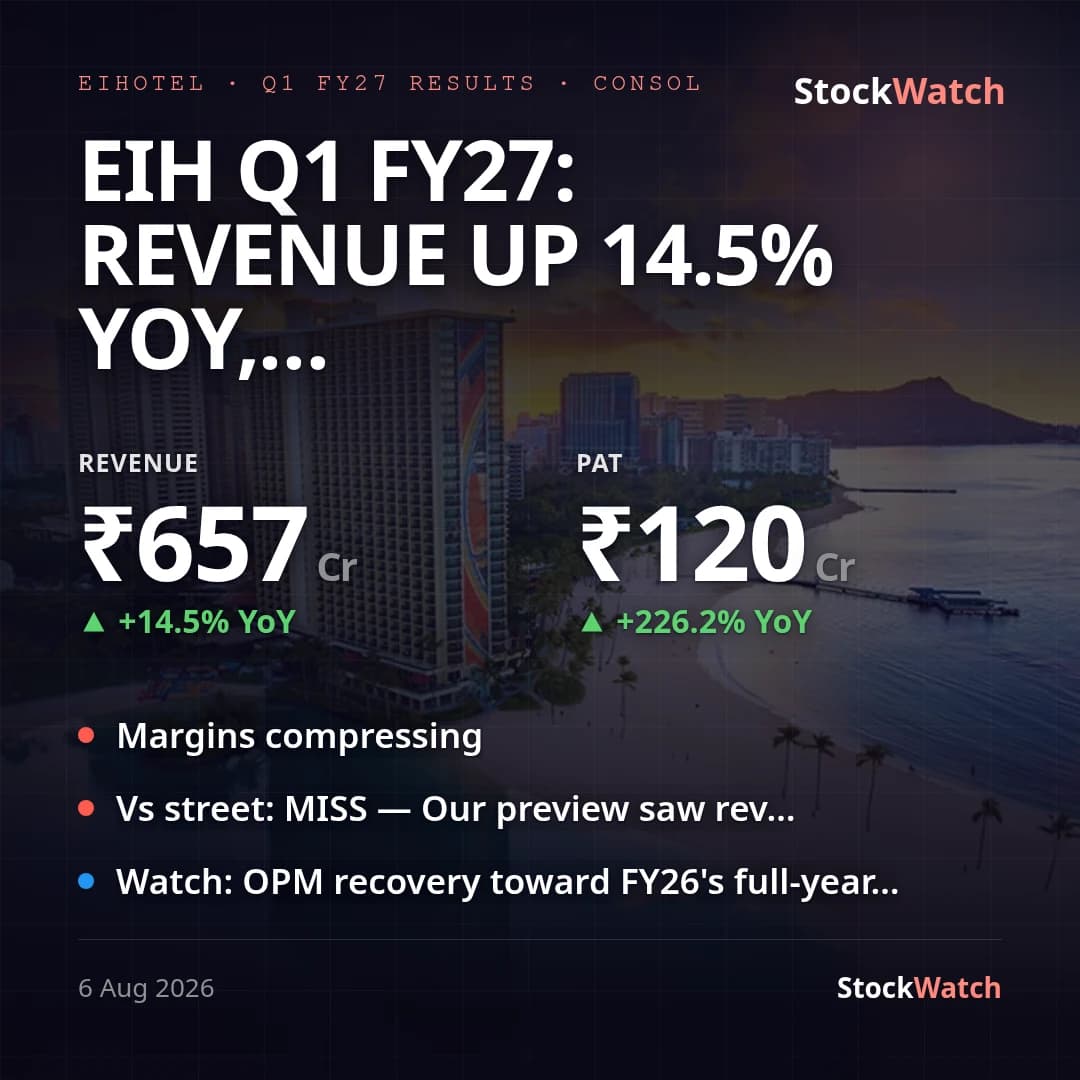
EIH's consolidated revenue for the quarter ended June 30, 2026 rose 14.5% YoY to ₹656.96 Cr, beating our own pre-result preview range of ₹590-610 Cr and matching management's own release headlined "15% Revenue Growth." Reported consolidated PAT (before minority interest) jumped to ₹120.31 Cr from ₹36.88 Cr a year ago (+226% YoY), but that comparison is distorted: Q1 FY26 carried a ₹110.49 Cr one-off exceptional charge tied to the Mashobra Resort/Wildflower Hall litigation settlement, while this quarter has zero exceptional items. Stripping the one-off from the base, adjusted PAT was ~₹147 Cr a year ago versus ₹120.31 Cr now — an adjusted YoY decline of roughly 18%. Profit attributable to owners was ₹117.14 Cr (EPS ₹1.87). Sequentially, revenue fell 26.6% and PAT fell 51.7% QoQ against Q4 FY26 (₹895.22 Cr / ₹249.10 Cr) — expected seasonal softness, since January-March is peak season for Indian hotels and April-June runs into the monsoon lull, exactly the dynamic our pre-result preview flagged.
The adjusted YoY profit decline traces to cost growth outrunning revenue: employee benefits expense rose 15.9% YoY (₹161.03 Cr vs ₹138.87 Cr) and other expenses rose 20.5% YoY (₹260.69 Cr vs ₹216.37 Cr), both ahead of the 14.5% topline growth. Operating margin (EBITDA/revenue from operations) came in at 25.35% this quarter, down from an adjusted 27.86% in Q1 FY26 (stripping that quarter's exceptional charge) and well below Q4 FY26's seasonally strong 37.30% — and materially below our preview's 37-38% expectation band, which appears to have anchored on the peak-season print rather than Q1 seasonality. Net margin (PAT/total income) was 17.24% versus an adjusted ~24.2% base a year ago.
Management's Q4 FY26 concall guidance centered on ARR-led growth and cost efficiencies, with strong domestic demand offsetting geopolitical drag on international travel — this quarter's revenue growth is broadly consistent with that framing, though the filing discloses no RevPAR, occupancy or domestic/international mix data, so the ARR-versus-occupancy and mix questions flagged in our pre-result preview remain unresolved by this print. Management's own release strikes a bullish tone on India's long-term travel and tourism opportunity and an "ambitious development programme," but doesn't address the margin compression visible in the numbers. One concrete capex-related update this quarter: the Oberoi Grand Kolkata renovation has been pushed to September 2028, signalling the staggered capex/expansion programme (guided at ₹600-700 Cr annually) is running slower than originally scheduled, though the filing gives no updated capex figure for the quarter. Standalone results mirror the pattern — revenue ₹599.80 Cr (+15.6% YoY) and reported PAT ₹127.09 Cr, which adjusts to roughly -13.4% YoY after stripping the ₹110.32 Cr prior-year exceptional item.
With no operational disclosures in this filing and no updated FY27 numeric guidance, the next checkpoints are whether margins recover toward FY26's full-year ~34.8% OPM level as the seasonally stronger Q3/Q4 quarters approach, and whether the delayed Oberoi Grand renovation affects near-term Kolkata capacity or FY27 capex pacing.