Escorts Kubota Q2 FY27: consolidated PAT falls 21% YoY as cost pressure squeezes margins
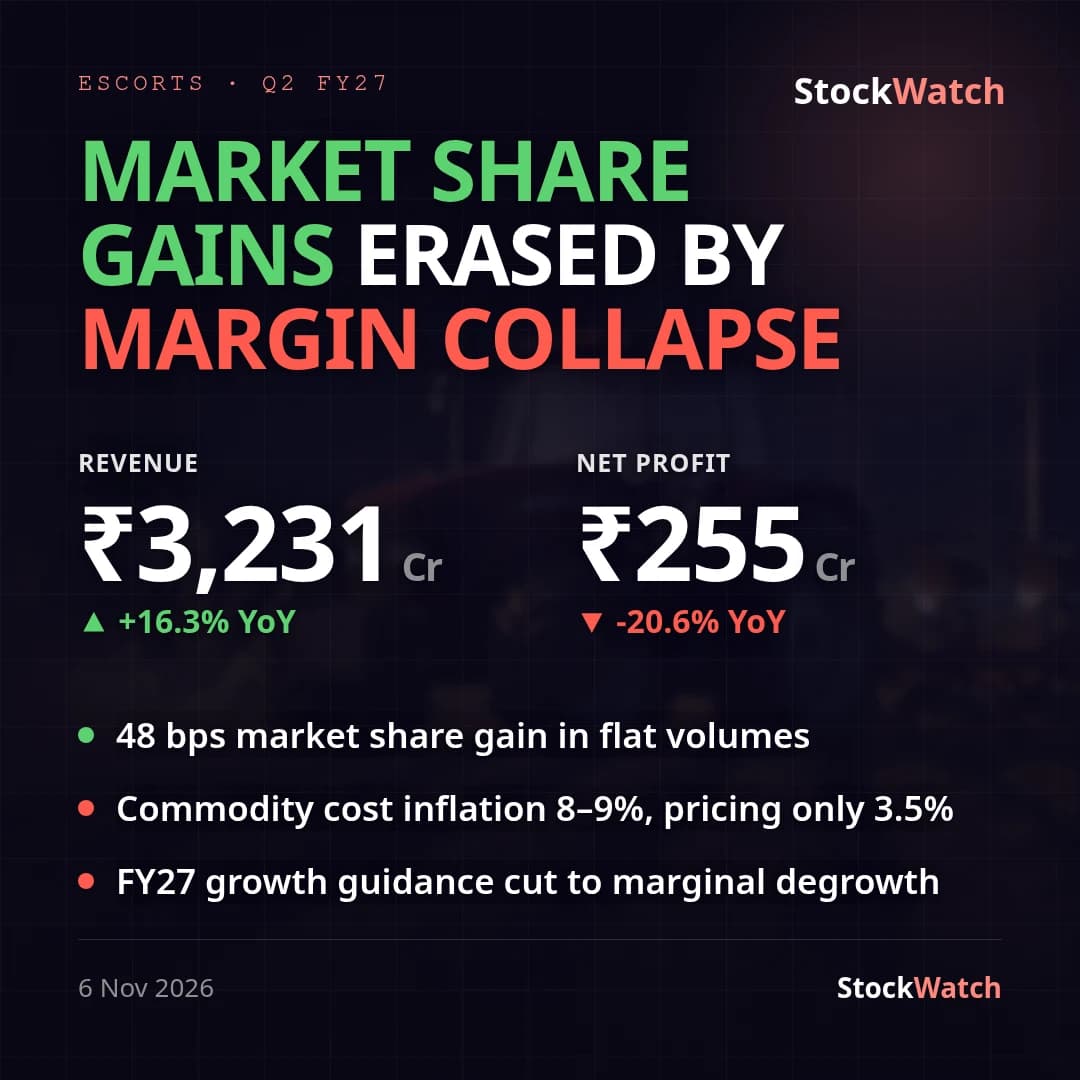
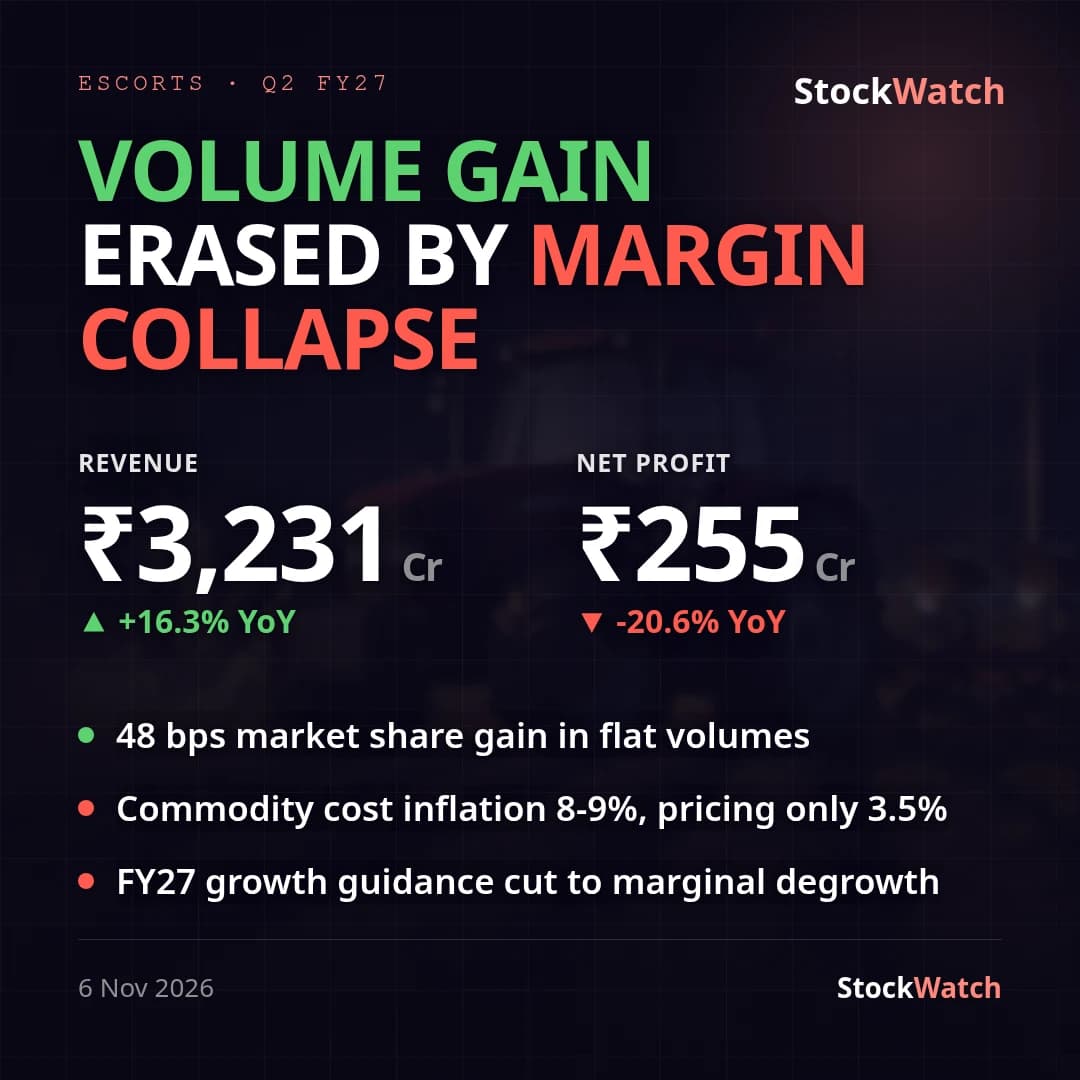
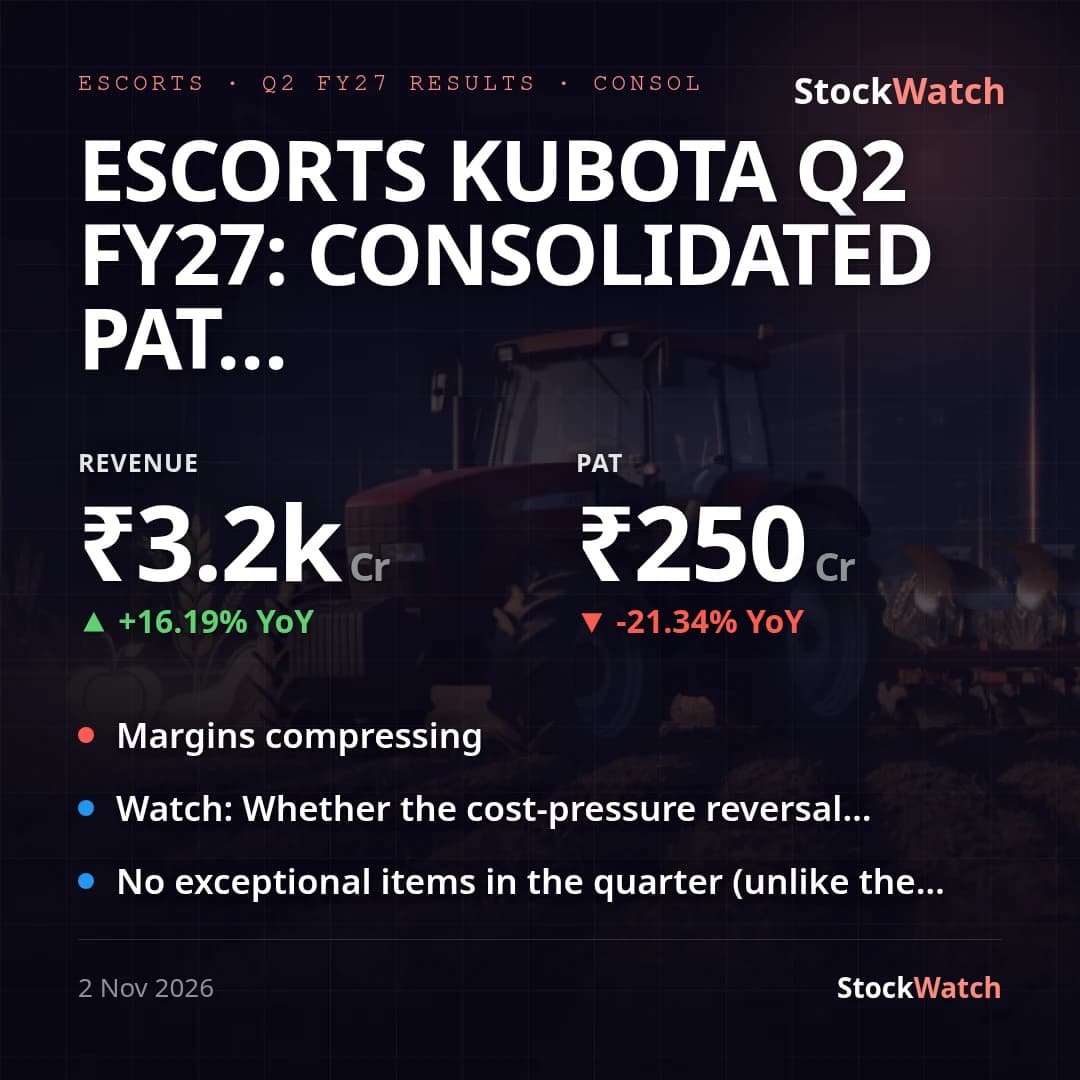
Escorts Kubota's consolidated PAT fell 21.3% YoY to ₹250.2 Cr (and 35.2% QoQ from ₹385.9 Cr) even as revenue grew 16.2% YoY to ₹3,243.4 Cr — a clean profit decline on an operating basis, since neither this quarter nor the year-ago quarter carried any exceptional item. Consolidated net margin compressed to 7.4% from 10.9% a year ago and 11.3% last quarter; operating margin fell to 8.9% from 12.9% YoY. Standalone PBT of ₹344.0 Cr missed our pre-result preview's ₹450-480 Cr expectation band by roughly a quarter, even though standalone revenue of ₹3,231.4 Cr came in slightly ahead of the ~₹3,150 Cr the preview flagged — so the quarter was a revenue beat and a margin/profit miss against our own bar.
The squeeze sits on the cost line: cost of materials plus stock-in-trade purchases rose 21.2% YoY, outpacing the 16.2% revenue growth, pushing the consolidated expense ratio to 93.4% of revenue from 89.5% a year ago. This is exactly what management flagged on the Q1 FY27 call — "additional 1.5-2% cost pressure expected in Q2, reversal hoped from Q4" — so the compression confirms rather than contradicts the prior guidance, even if the magnitude of the profit hit is larger than the preview's on-plan numbers assumed. Segment data shows where it bit: Agri machinery revenue grew 10.6% YoY to ₹2,690.1 Cr (industry guidance was mid-single-digit growth, so Escorts is tracking ahead, consistent with management's market-share claim) but segment profit fell 33% YoY to ₹209.1 Cr. Construction equipment was the bright spot — revenue up 58.6% YoY to ₹536.2 Cr and segment profit up 231% YoY to ₹42.3 Cr — partially offsetting agri weakness, though it remains a small base relative to the ₹2,690 Cr agri segment.
The quarter's events corroborate the demand picture: tractor sales were down 16.7% YoY in September and 10% YoY in October (per our monthly updates), while construction equipment sales were up 41.6% YoY in October — the same divergence visible in the segment P&L. The company hiked tractor prices effective November 2026, a lever against the commodity cost pressure, and management held media interactions on Nov 2-3 around the results. We found no specific external analyst consensus figure for this quarter (a published preview citing only prior-period actuals, no Q2 FY27 PAT/revenue estimate), so the comparison above rests on our own pre-result preview and management's own guidance rather than a street number. Motilal Oswal's standing Neutral call (target ₹3,348, ~25x FY27E EPS) had already flagged near-term margin pressure from commodities as the key swing factor — this print is consistent with that thesis playing out.
Going into Q3, the key test is whether the cost-pressure reversal management "hoped" for from Q4 FY27 shows up on schedule, and whether October's narrower 10% YoY tractor decline (versus September's 16.7%) marks a bottoming or just a smaller base effect. Construction equipment's scale-up, if sustained, is the more visible near-term offset to agri margin pressure.