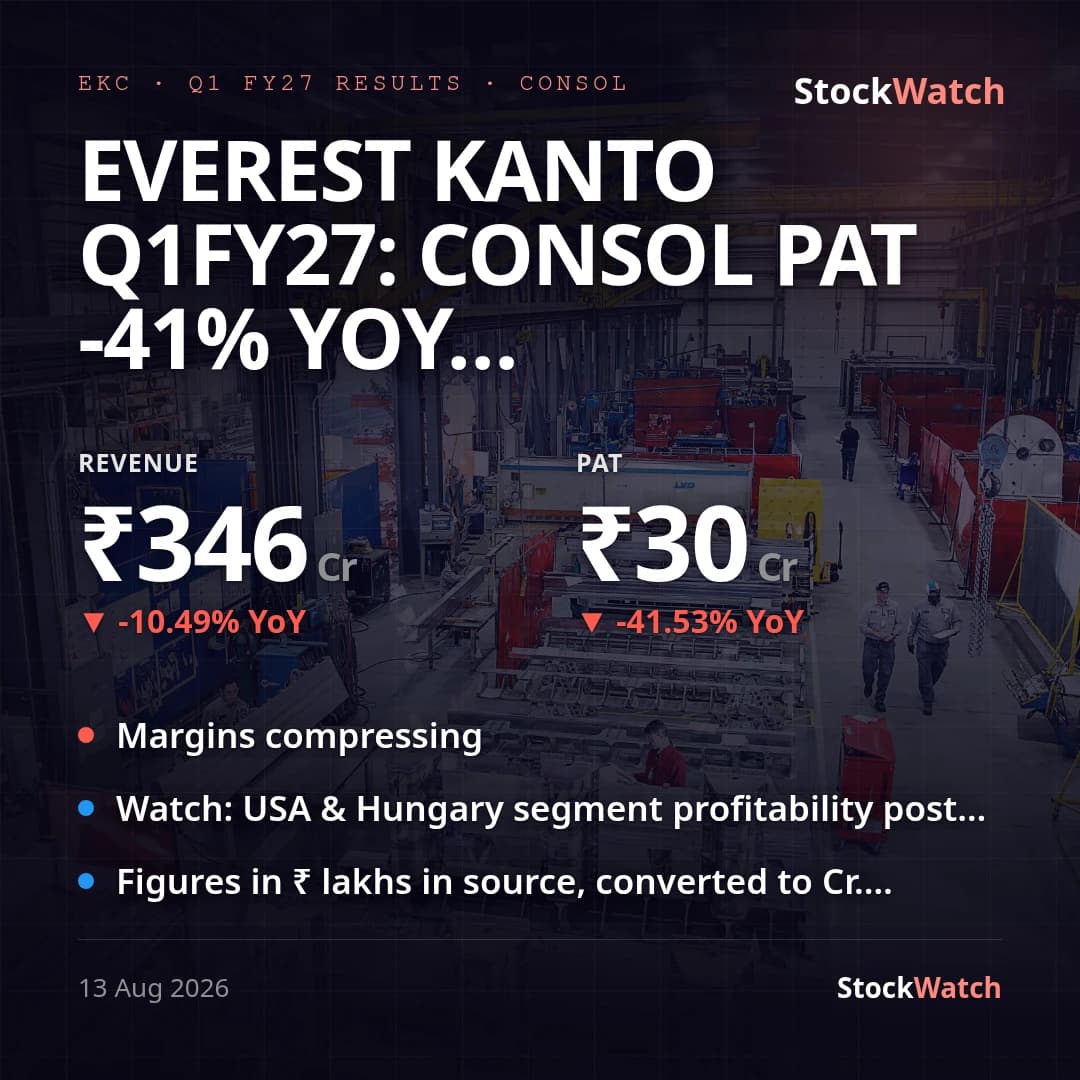
Everest Kanto Q1FY27: consol PAT -41% YoY (-23% adj), US-Hungary slump hits margins
Everest Kanto Cylinder's consolidated revenue fell to ₹346.31 Cr, down 10.5% YoY and 3.3% QoQ, while consolidated PAT came in at ₹30.16 Cr, down 41.5% YoY as reported and 34.0% QoQ. The YoY comparison is distorted by a one-off: Q1 FY26's base included a ₹12.63 Cr exceptional gain from an employee-retention-credit tax refund at US subsidiary CP Industries Holdings. Stripping that out, adjusted YoY PAT decline is closer to 23% — still a clear deterioration, not the headline-implied collapse, but a real one nonetheless. There is no street consensus available for this quarter (no analyst previews found), so vsStreet is unknown.
The drag is concentrated overseas. Segment results (pre-forex/finance/tax) show USA & Hungary collapsing to ₹4.84 Cr from ₹26.85 Cr a year ago (-82%), while India, the largest segment, held up comparatively better at ₹28.71 Cr vs ₹34.05 Cr (-15.7%). Standalone (India-only) PAT of ₹21.93 Cr was down just 15.9% YoY, underscoring that the consolidated miss is an international-segment story, not a domestic one. Group NPM compressed to 8.46% of total income from 13.13% a year ago; OPM (EBITDA-based) fell to 13.68% from 19.11% YoY, though it improved sequentially from 11.49% in Q4 FY26. Part of the USA/Hungary distortion traces to the April 2026 completion of the sale of EKC's 80% stake in EKC Europe Zrt, Hungary — this quarter reflects a changed consolidation scope for that entity versus the year-ago period.
Management's prior (June 2026) commentary pointed to "continued strong demand" for CNG and industrial gas applications in India and touted the Mundra facility and upcoming Egypt operations as growth drivers; against that, India segment revenue actually declined 14.4% YoY to ₹202.74 Cr this quarter, running counter to the stated demand outlook — call it missed rather than met, though management gave no quantified guidance to test against precisely. The quarter's other developments — a new CEO (Narender Gupta, appointed July 2026) and a board-meeting reschedule from August 14 to August 13 — are governance-level items with no direct read on these numbers. No fresh press release commentary from management was available in the context to cross-check against the print.
Going into Q2 FY27, the key markers are whether the USA & Hungary segment stabilizes now that the Hungary divestment is behind it, whether India segment revenue reverses its YoY decline to validate the standing demand guidance, and whether NPM holds near or above the 8-9% mark seen this quarter rather than slipping further from the 12-13% run-rate of the trailing two quarters.