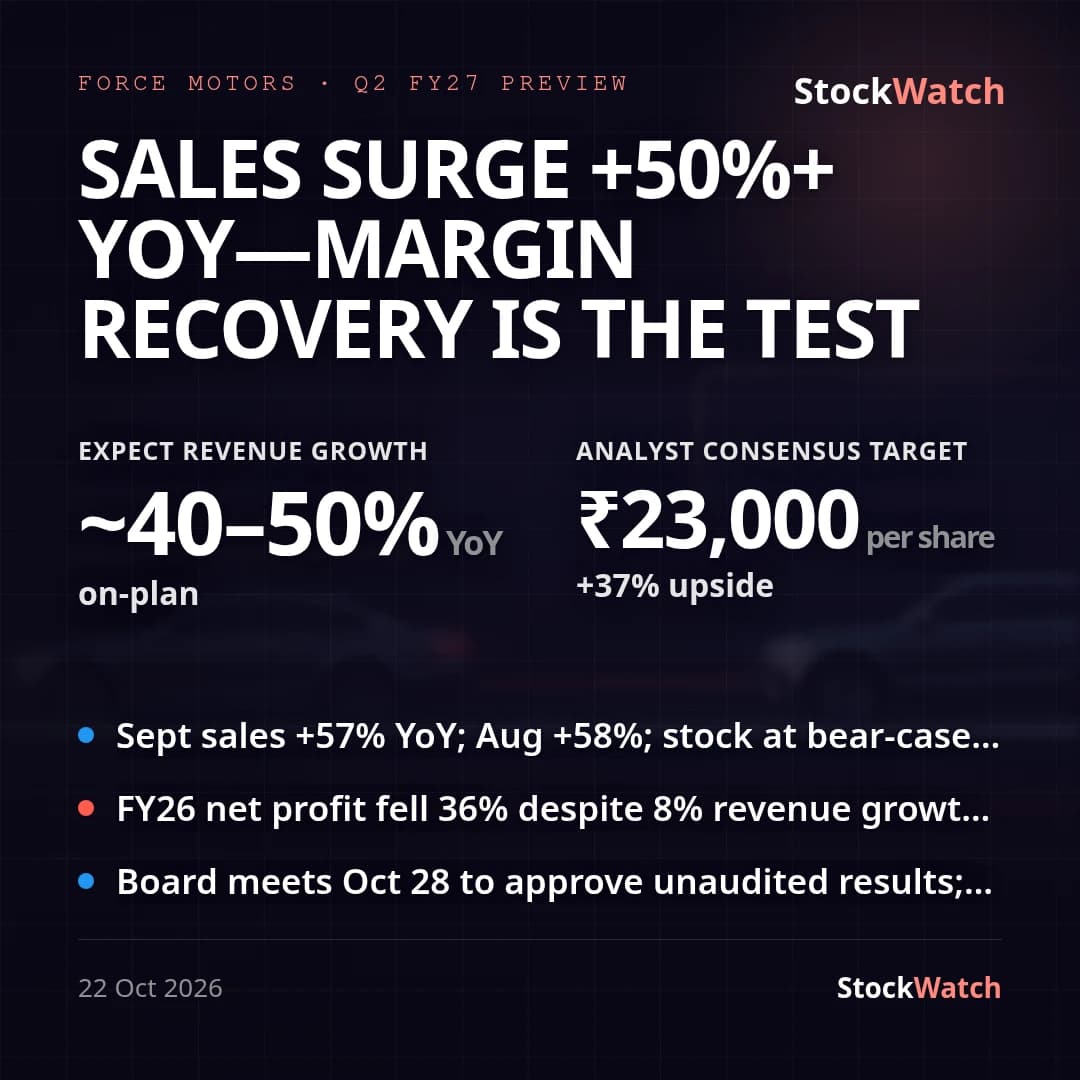
Force Motors Q2 FY27: revenue up 41% YoY, but margin recovery vs last year still partial
Force Motors' consolidated revenue from operations grew 40.5% YoY to ₹2,924.66 Cr in Q2 FY27 (quarter ended 30 Sept 2026) — within the 40–50% YoY range flagged going into the print — and rose 19.9% sequentially from ₹2,440.01 Cr in Q1 FY27. Consolidated PAT was ₹293.91 Cr, down 16.2% YoY from ₹350.70 Cr, but that headline comparison is distorted: Note 4 to the results states the year-ago quarter carried a one-time ₹85.46 Cr tax benefit (deferred tax/MAT credit recognised on opting into the Section 115BAA regime), making Q2 and H1 FY26 tax, PAT and EPS explicitly "not comparable" to the current period. Stripping that one-off out, adjusted PAT rose roughly 11% YoY — a real but modest recovery that still trails the 40%+ revenue growth. Sequentially PAT rose 35.7% QoQ from ₹216.59 Cr.
Operating margin (EBITDA/revenue) was 14.83% this quarter, up from 13.43% in Q1 FY27 — a sequential improvement — but still below the 17.43% posted in Q2 FY26, so the margin-delivery pivot flagged pre-result has only partly played out. The YoY gap doesn't trace to raw material cost, which was roughly flat (74.4% of revenue vs 74.6% a year ago); the bigger swing was a smaller favourable movement in finished-goods inventory (a ₹48.46 Cr credit to expenses this quarter versus ₹109.18 Cr a year ago), which more than offset improved employee-cost (6.8% of revenue vs 8.2%) and depreciation (2.8% vs 3.4%) ratios. Net profit margin was 9.91% of total income versus 16.65% a year ago (also inflated by the tax one-off) and 8.74% last quarter. The company has no formal management guidance on record, so this recovery is being judged against its own FY26 margin compression rather than a stated target, and management's own framing of the quarter was not available to cross-check, as no press release had been extracted at review time.
Street coverage is thin: no formal consensus revenue or PAT estimate could be found for this quarter, consistent with the pre-result read that the stock — trading at the bear end of a ₹16,000/₹23,000/₹28,000 bear-base-bull target band — sits in a "show me" posture rather than being actively modelled by brokerages. On the corporate side, the quarter included the completed acquisition of Veera Tanneries Pvt Ltd (share purchase agreement dated 23 April 2026, now a wholly owned subsidiary) and two EGMs (1 and 26 October 2026) to approve removing transfer restrictions on 1,15,748 'Second A' equity shares — both procedural rather than numbers-moving. Standalone PAT of ₹291.44 Cr tracked closely with the consolidated figure (0.8% divergence), with the Force MTU Power Systems JV contributing ₹2.94 Cr of the gap.
Domestic volumes stayed strong into the current quarter — September 2026 sales were up 57% YoY per the company's own monthly update — supporting continued topline momentum. But with H1 FY27 PAT still down 3.1% YoY (₹510.50 Cr vs ₹527.06 Cr, unadjusted for the prior-year tax one-off) against H1 revenue up 22.5% YoY (₹5,364.67 Cr vs ₹4,378.65 Cr), the gap between volume-led revenue growth and full margin recovery is the thing to track into H2 FY27.