StockWatch
·

Globe Civil Projects Ltd

BSE: 544424

P/L Snapshot

Q1 FY27 · standalone

vs Q3 FY26·vs Q1 FY26
Revenue
92.46
-1.4%+41.2%
Expenditure
82.45
-3.9%+40.5%
Net Profit
7.16
+9.7%+41.6%
OPM %
16.54%
+1.35pp-1.14pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.0028.0056.0184.01112.01Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q1 FY27
Price Chart
Reports

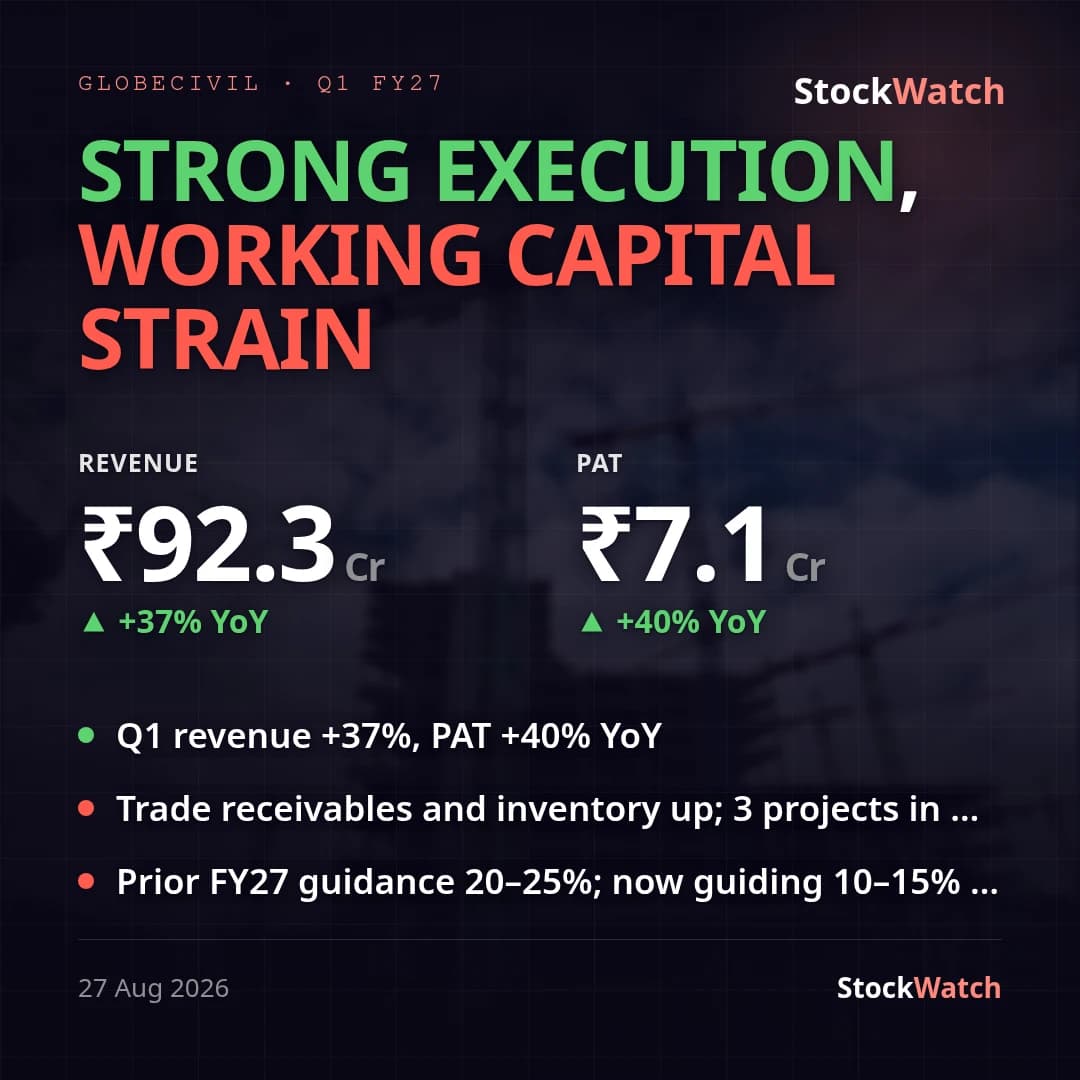
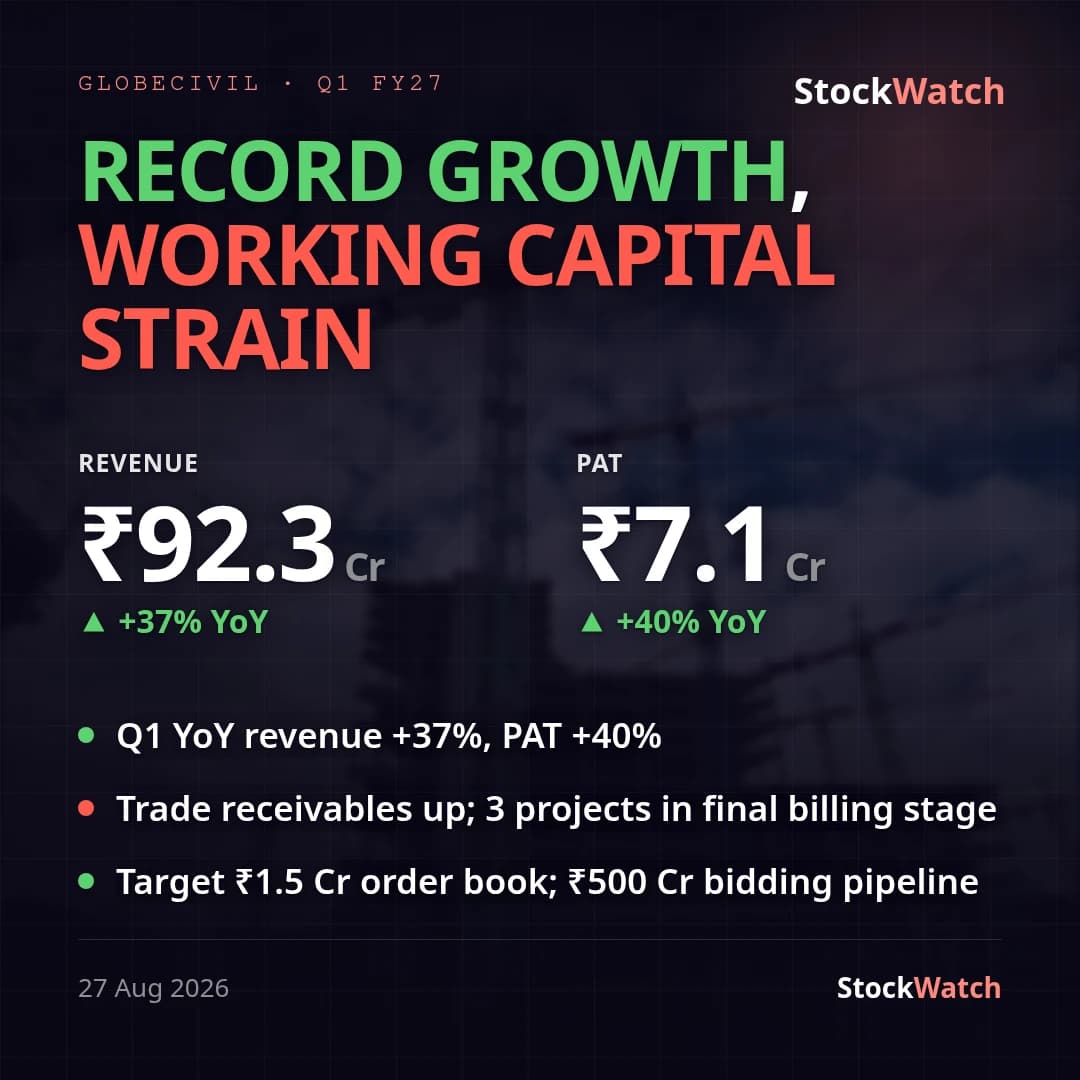
Strong Execution, but Guidance Softened and Working Capital Strained

order book expansion · working capital intensity · government concentration
Result verdictFollow-upQ1 FY2727 Aug 20266 minIndustrials & Infra

Strong Q1 beat, but order book guidance softens vs prior 20-25% target

order book expansion · working capital intensity · government concentration
TranscriptDeep diveQ1 FY2727 Aug 20266 minIndustrials & Infra

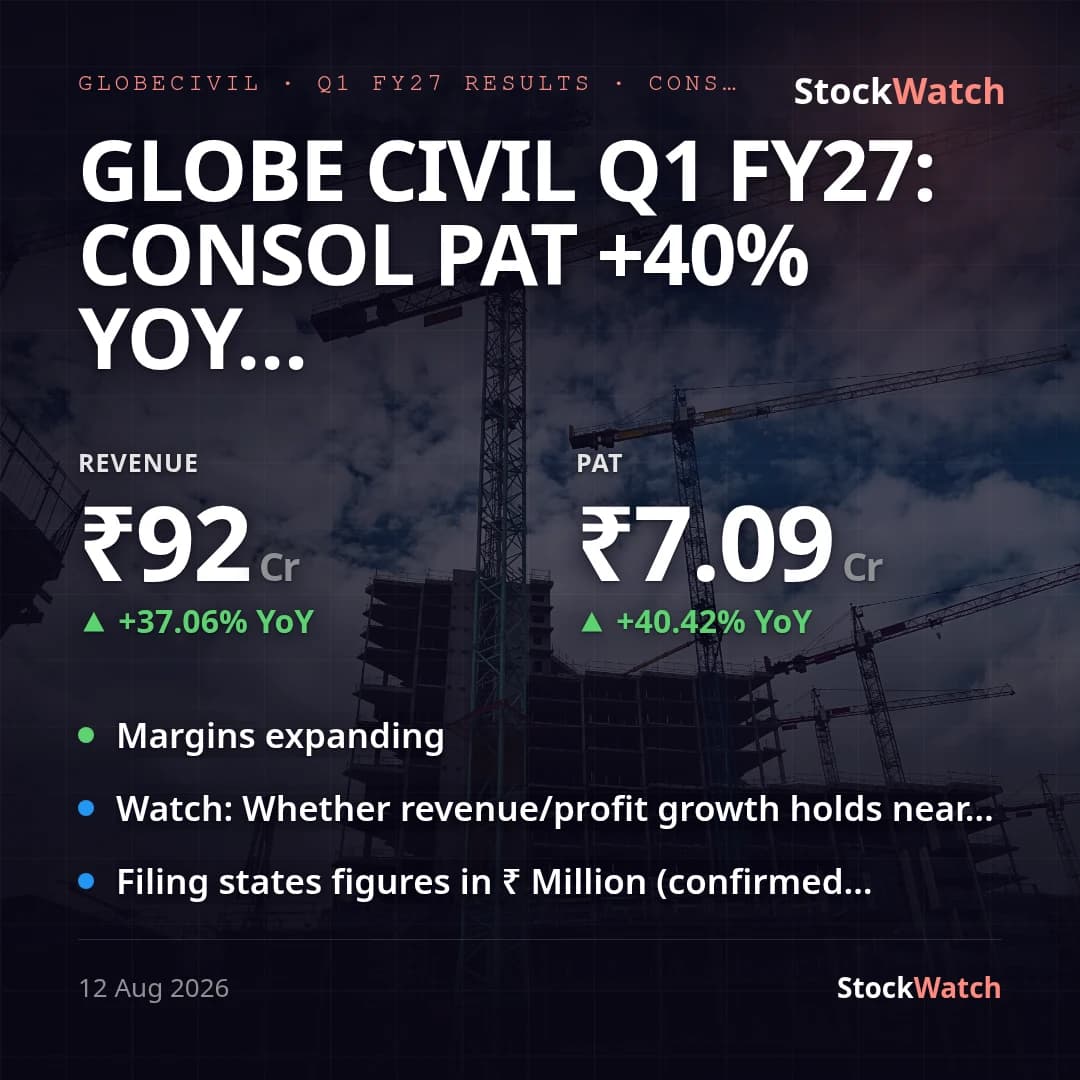
Globe Civil Q1 FY27: consol PAT +40% YoY to ₹7.1 Cr, revenue +37% ahead of FY27 guidance

epc · construction · revenue growth

ResultsQ1 FY2712 Aug 20263 minIndustrials & Infra
Latest
Board Meeting12 Aug, 8:21 pm

Globe Civil Q1 FY27: consol PAT +40% YoY to ₹7.1 Cr, revenue +37% ahead of FY27 guidance

Globe Civil Projects posted consolidated revenue of ₹92.30 Cr (+37.1% YoY from ₹67.35 Cr) and consolidated PAT of ₹7.09 Cr (+40.4% YoY from ₹5.05 Cr) for the quarter ended June 30, 2026 — comfortably ahead of the 20-25% revenue-and-profitability growth management reiterated for FY27 onward at its February 2026 concall, even though that same call cut the near-term FY26 growth guide to 15-20% on Delhi NCR execution delays. Consolidated EPS was ₹1.19 versus ₹1.16 a year ago. Standalone PAT of ₹7.16 Cr sits within 1% of the consolidated number, so the two tell the same story. No street consensus estimates could be located for this print — Globe Civil (~₹285 Cr market cap) carries no visible brokerage coverage — so vsStreet is unknown rather than a miss, and the company did not issue a separate press release to reconcile against. Net margin improved to 7.68% from 7.46% YoY, but operating margin (revenue less cost of construction, materials and employee costs, excluding finance and depreciation) compressed to roughly 16.4% from 17.1% as cost of construction and wages/subcontractor costs scaled with revenue. The NPM gain despite that operating squeeze came from finance costs, which fell in absolute terms (₹4.03 Cr standalone vs ₹4.29 Cr a year ago) even as revenue grew — consistent with lower working-capital leverage after IPO proceeds (₹114.3 Cr of ₹119 Cr net proceeds now utilised, including the full ₹75 Cr earmarked for working capital). Sequentially, revenue fell 35.5% QoQ from Q4 FY26's ₹143.18 Cr while PAT rose 23.1% QoQ to ₹5.76 Cr — Q4 is the seasonally heaviest billing quarter for EPC contractors on fiscal year-end completions, so this sequential drop reads as normal seasonality and should not be weighed against the YoY growth story. The quarter's only disclosed business update was a small ₹1.2 Cr contract win from Central University of Punjab (July 4) — immaterial next to the ₹850 Cr order book and ₹1,000+ Cr bidding pipeline management cited as the basis for its FY27 growth confidence. This is the first quarterly print against that reiterated FY27 target, and it clears the bar on both revenue and profit growth; the open question is whether operating margin stabilizes as construction and wage costs keep climbing in line with volumes.

12 Aug 2026, 08:21 pm

Corporate Events

Board MeetingGLOBECIVIL
2026
25Sep

Board Meeting

The 24th Annual General Meeting (AGM) of the Company will be…

BSE Filing
Board MeetingGLOBECIVIL
2026
12Aug

Board Meeting

The Board of Directors meeting is scheduled to consider and …

BSE Filing
Board MeetingGLOBECIVIL
2026
30May

Board Meeting

The board meeting is scheduled to consider and approve the S…

BSE Filing