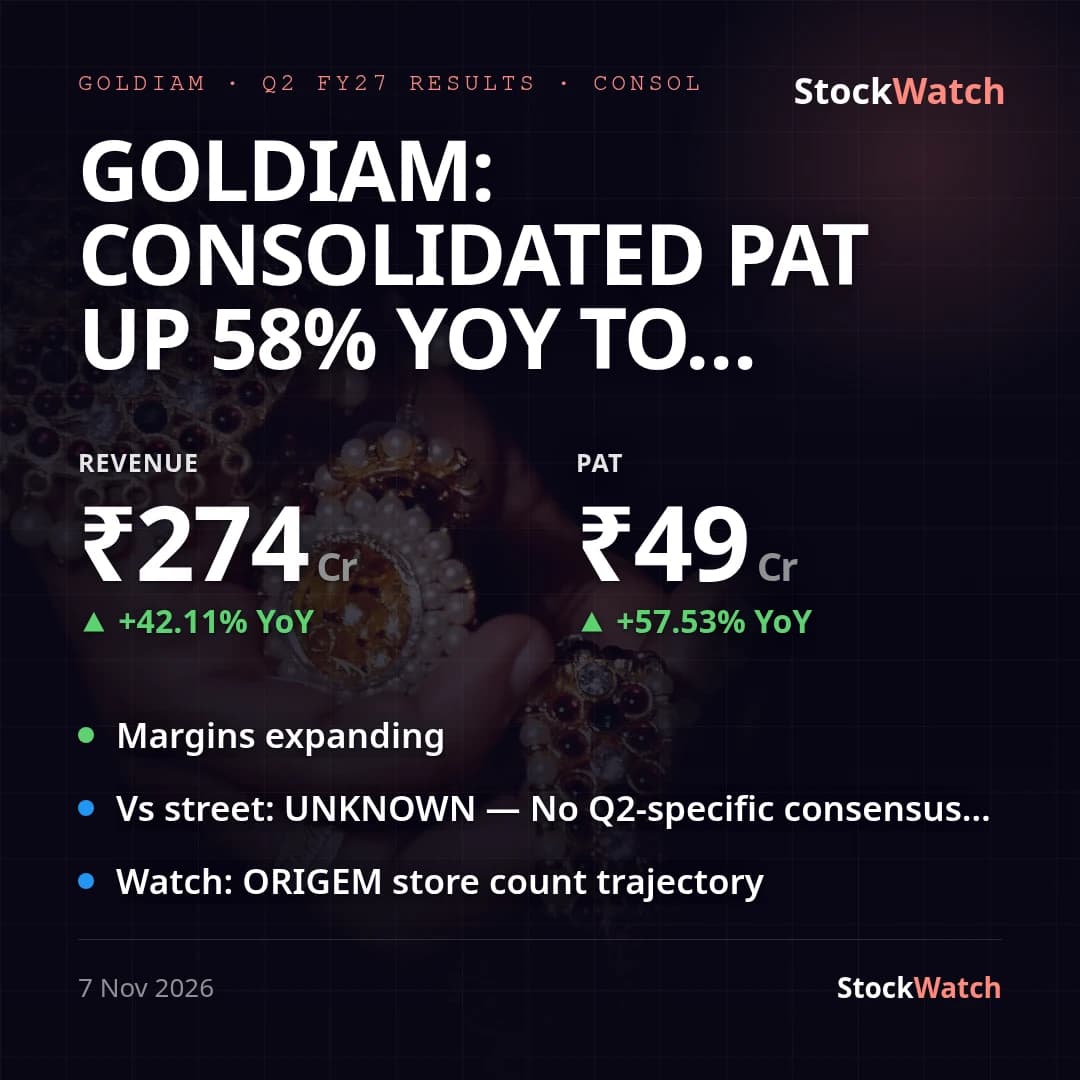
Goldiam: consolidated PAT up 58% YoY to ₹49.4 Cr on B2B strength, but Origem rollout trails plan
Goldiam International's consolidated (primary) PAT rose 58% YoY to ₹49.40 Cr on revenue from operations of ₹274.00 Cr, up 42% YoY — a record Q2 on both counts, with no exceptional items on either side of the comparison so the growth is clean. NPM expanded 141 bps YoY to 16.94% and EBITDA margin (OPM) expanded 176 bps YoY to 25.24%, driven by the continued mix shift toward lab-grown diamond (LGD) jewellery, which held at 91.2% of export sales versus 90% a year ago. Sequentially, revenue fell 16% and PAT fell 33% from an unusually strong Q1 FY27 (₹326.03 Cr revenue, ₹73.97 Cr PAT); both margins also compressed QoQ (NPM -340 bps, OPM -333 bps). Management has flagged order-based revenue visibility running into Q2, so this reads as quarter-to-quarter order lumpiness in a B2B exporter rather than a demand reversal — YoY is the number that matters here.
Against the company's own February 2026 outlook, the B2B export engine is tracking ahead: segment (jewellery) revenue grew 43.7% YoY to ₹283.08 Cr, consistent with management's stated confidence in doubling the B2B business over 3-5 years and gaining wallet share as large US retailers consolidate vendors — a claim Executive Chairman Rashesh Bhansali repeated in today's press release, tying it directly to the >40% topline growth and the LGD mix. The B2C ORIGEM chain is a different story: management had guided to 24-26 stores by FY26-end plus 50 more in H1 FY27, implying roughly 74-76 stores by now; the company instead had 29 operational ORIGEM stores as of November 7, 2026, with only three added in the September quarter (27th-29th stores, per company announcements). MD Anmol Bhansali's press-release framing that ORIGEM is 'expanding as planned' does not square with that numeric target, so the store-rollout guidance reads as missed even as the B2B segment outperforms. No brokerage-specific consensus estimate for this quarter could be located; the one external FY27 reference found (sharpely.in) pegs full-year street PAT growth at 15-20%, a bar H1 FY27's 90% consolidated PAT growth has already cleared.
Standalone (parent-only) numbers grew faster than consolidated — PAT +93% YoY to ₹25.43 Cr on revenue +56% YoY to ₹163.26 Cr — a gap wide enough to flag: it suggests the overseas subsidiaries (Goldiam USA, Diagold Designs, Eco-Friendly Diamond LLP) grew slower than the parent this quarter. Corporate actions alongside the results: a 1st interim FY27 dividend of ₹2/share (100%, ₹30.11 Cr total) and a bonus share issue that lifted paid-up capital from ₹22.58 Cr to ₹30.11 Cr during the quarter, which is why diluted EPS (₹2.96, +3.9% YoY) lagged basic EPS (₹4.38) and PAT growth so sharply — a per-share dilution effect, not an earnings-quality issue. Order book stood at ₹225 Cr as of September 30, 2026, and cash & equivalents (including investments) at ₹457.83 Cr.