StockWatch
·

GOODRICKE GROUP LTD.

BSE: 500166

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27·vs Q2 FY26
Revenue
259.03
+20.0%+17.5%
Expenditure
215.96
+21.0%+13.4%
Net Profit
46.57
+13.9%+7.0%
OPM %
22.11%
+1.46pp+2.29pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
-79.2531.00141.25251.51361.76Q2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

Goodricke standalone Q2 PAT +7% YoY to ₹46.6 Cr; prior-year tax credit skews comparison

tea · crop recovery · exceptional items

ResultsQ2 FY2713 Nov 20263 minFMCG

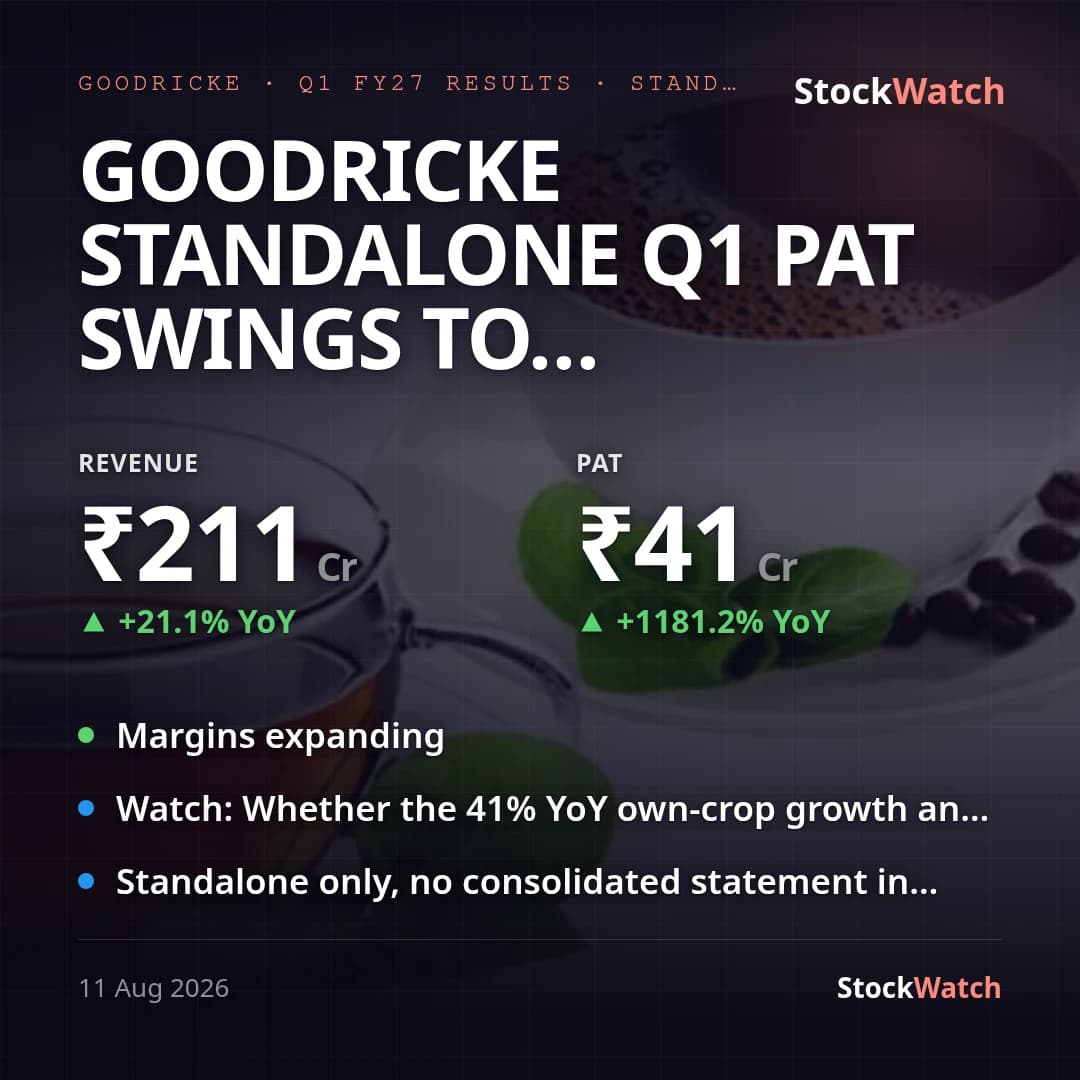
Goodricke standalone Q1 PAT swings to ₹40.9 Cr as 41% crop recovery lifts OPM to 17.9%

tea · agri seasonal · standalone results

ResultsQ1 FY2711 Aug 20263 minFMCG
Latest
Quarterly Result13 Nov, 6:05 pm

Goodricke standalone Q2 PAT +7% YoY to ₹46.6 Cr; prior-year tax credit skews comparison

Goodricke Group's standalone Q2 FY27 revenue rose 17.96% YoY to ₹255.45 Cr (+20.89% QoQ) on tea price and volume recovery, but reported PAT of ₹46.57 Cr grew just 6.98% YoY (+13.95% QoQ) — trailing the topline. Stripping the exceptional gains on both sides (₹12.06 Cr this quarter from an artwork sale vs ₹10.14 Cr a year ago from the Leshriver Tea Estate asset sale), adjusted PAT growth is even softer at ~3.35% YoY, since this year's one-off was larger in absolute terms than last year's. The muted bottom line understates the operating story. Pre-tax, pre-exceptional profit (the cleanest operating read) was ₹43.07 Cr versus ₹29.96 Cr a year ago — up ~43.8% YoY, a genuine expansion in core operating margin (to 16.63% of total income from 13.59%). The gap to reported PAT growth is a tax-base effect: this quarter's effective tax rate is a normal ~15.5% (₹8.56 Cr tax on ₹55.13 Cr PBT), while the year-ago quarter carried a net tax credit (-8.6% effective rate, as a ₹3.59 Cr deferred tax credit outweighed ₹0.16 Cr current tax), artificially lifting that quarter's PAT above its own PBT. On an adjusted-PAT basis margin is therefore recorded as compressing (~15.15% to ~13.32% of total income), even though the underlying, pre-tax business got more efficient — a case where reported numbers and operating reality diverge mainly because of a base-quarter tax anomaly rather than genuine margin pressure. Management's own commentary attributes H1 profitability improvement (own crop up 31% YoY ex the effect of estates already sold) to higher crop and cost-control initiatives, consistent with the operating-margin expansion seen here. No consensus estimates or formal management guidance exist on record for this print (vsStreet and vsGuidance are both unknown), so the result is judged purely against its own trend. Corporate activity this quarter continued a non-core asset monetisation theme: beyond the artwork sale booked as this quarter's exceptional item, the company signed a non-binding MoU on 30 October 2026 (after quarter-end) to sell/assign leasehold rights on the Barnesbeg Tea Estate for ₹5 Cr, pending due diligence — a fourth such land/asset disposal disclosed across recent quarters (Chalouni in Q1 FY27, Leshriver in FY26). The auditor's limited-review report again flagged a qualified conclusion on tea stock valuation (cost based on full-year estimated production/expenditure rather than actual quarter cost), a recurring, non-cash accounting matter unrelated to this quarter's operating performance. Going into Q3 FY27 — typically the peak tea season — the read-through is that volume/crop-driven operating improvement is real, but reported PAT comparisons will likely stay noisy until the exceptional items and tax-rate base effects wash out.

13 Nov 2026, 06:05 pm

Quarterly Result11 Aug, 7:30 pm

Goodricke standalone Q1 PAT swings to ₹40.9 Cr as 41% crop recovery lifts OPM to 17.9%

Goodricke Group's standalone Q1 FY27 (quarter ended 30 June 2026) revenue rose 21.1% YoY to ₹211.30 Cr from ₹174.51 Cr, and the company swung to a net profit of ₹40.87 Cr (EPS ₹18.92) against a thin ₹3.19 Cr profit (EPS ₹1.48) a year earlier — nominally a >12x jump, but almost entirely a base effect since Q1 FY26 profit was near-breakeven. PAT includes a ₹5.80 Cr exceptional gain on the sale of specified assets and leasehold rights at a tea estate (₹19.00 Cr consideration, board-approved 3 April 2026, transacted May 2026); stripping this out, PBT before exceptional was ₹37.35 Cr and adjusted PAT is roughly ₹35.4 Cr — still up sharply YoY, but the triple-digit percentage move is a function of the tiny year-ago base rather than a repeatable growth rate. Sequentially, revenue more than doubled (+103.5% QoQ) and PAT reversed a ₹29.21 Cr Q4 FY26 loss (EPS -₹13.52); this QoQ swing is a seasonality artifact typical of the tea business — Q4 (Jan-Mar) is the lean off-season with heavy fixed-cost drag, while Q1 picks up with the new crop — and should not be read as sequential momentum. Margins expanded materially on both bases: net margin was 18.94% versus -27.86% last quarter and 1.77% a year ago, and OPM (EBITDA/revenue) was 17.90% versus -23.65% QoQ and 1.67% YoY. Management's own note in the filing attributes the improvement to the company's own tea crop volume being 41% higher than the year-ago period (excluding the estate sold) combined with better price realisations and a cost/quality focus — this framing is directly consistent with both the revenue growth and the margin expansion this quarter. Total expenses were roughly flat YoY (₹178.50 Cr vs ₹178.39 Cr) even as employee costs rose to ₹99.14 Cr from ₹95.86 Cr, indicating the margin gain came from operating leverage on higher volumes/realisations rather than cost cutting. There is no prior management guidance or concall commentary on record for this stock, and no broker/consensus estimates could be located (Goodricke is a micro-cap, ~₹407 Cr market cap, with negligible analyst coverage) — so this print cannot be benchmarked against a street number or a prior outlook; both are being reported as unknown/none rather than assumed. Separately, the auditor's qualification that applied a year ago recurs this quarter: the statutory auditor (MSKA & Associates, newly reappointed for a five-year term from 4 August 2026) issued a qualified review conclusion because the company values quarterly tea stock at estimated full-year production/cost rather than actual cost for the quarter — a methodology caveat rather than a restated number, but one that limits comparability of the quarterly P&L construct itself. The board also approved Grant Thornton Bharat LLP as internal auditor for FY27-FY29 at the same meeting, unrelated to the P&L print.

11 Aug 2026, 07:30 pm

Corporate Events

Board MeetingGOODRICKE
2026
13Nov

Board Meeting

The meeting of the Board of Directors is scheduled to consid…

BSE Filing ↗
Board MeetingGOODRICKE
2026
11Aug

Board Meeting

The meeting of the Board of Directors of the Company is sche…

BSE Filing ↗
Board MeetingGOODRICKE
2026
29Jul

Board Meeting

The Fiftieth (50th) Annual General Meeting of the Company is…

BSE Filing ↗
DividendGOODRICKE
2026
22Jul

₹2 / share

BSE Filing ↗
Board MeetingGOODRICKE
2026
27May

Board Meeting

The board meeting is scheduled to consider and approve the A…

BSE Filing ↗
Board MeetingGOODRICKE
2024
13Nov

Board Meeting

Consider and approve Unaudited Financial Results

BSE Filing ↗
Board MeetingGOODRICKE
2024
21May

Board Meeting

Consider and approve Audited Financial Results

BSE Filing ↗
Board MeetingGOODRICKE
2024
8Feb

Board Meeting

Consider and approve Unaudited Financial Results for Q3 and …

BSE Filing ↗
Board MeetingGOODRICKE
2023
9Nov

Board Meeting

Consider and approve Unaudited Financial Results of the Comp…

BSE Filing ↗