StockWatch
·

Happy Forgings Ltd

BSE: 544057

P/L Snapshot

Q1 FY27 · standalone

vs Q4 FY26·vs Q1 FY26
Revenue
460.51
+7.1%+26.5%
Expenditure
337.87
+6.0%+22.6%
Net Profit
91.46
+9.5%+39.2%
OPM %
31.34%
-0.12pp+2.75pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.00128.94257.88386.82515.77Q2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27
Price Chart
Reports

Order Book Validated, But Margin Durability Hangs on Freight Pass-Through

order book · freight costs · pricing power
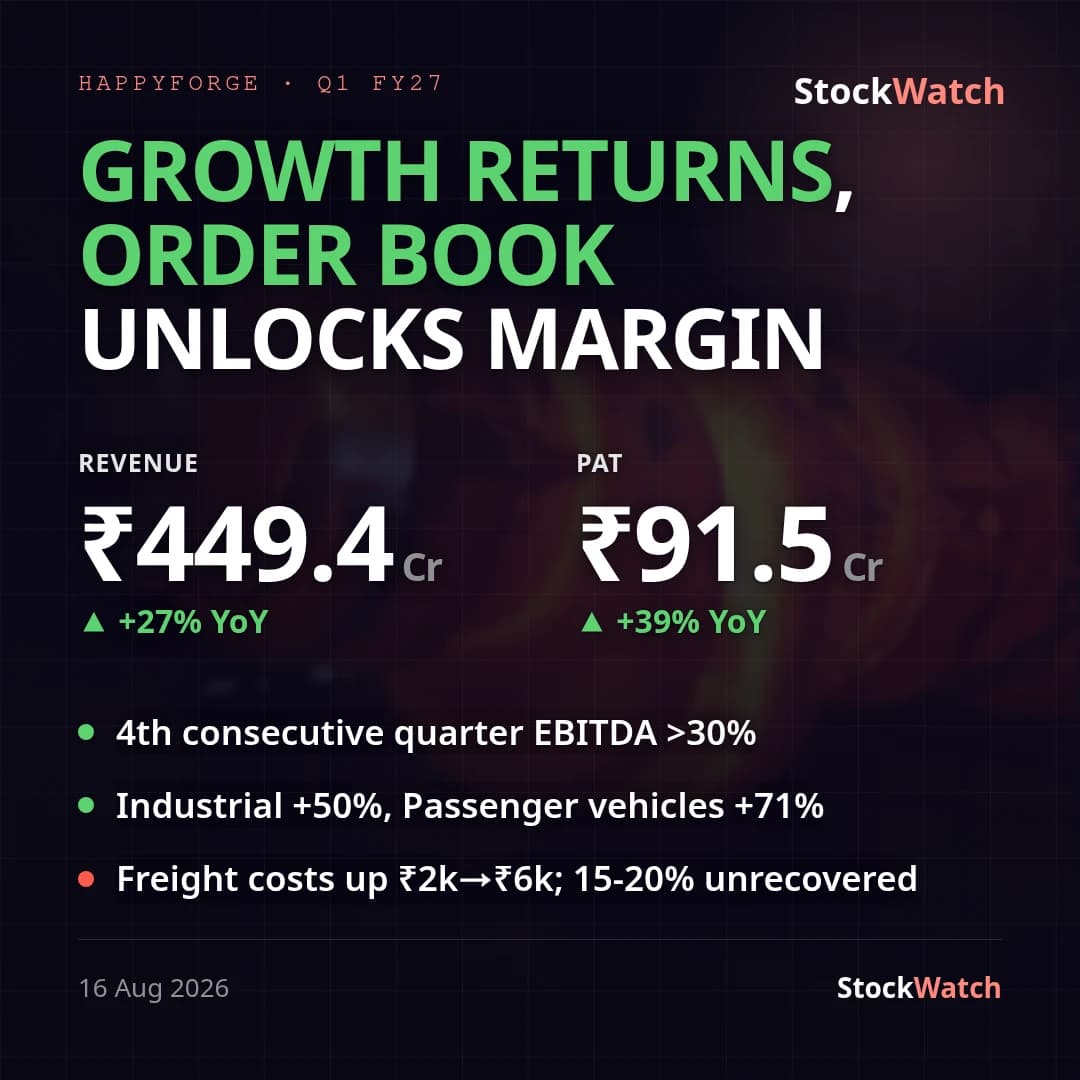
Result verdictFollow-upQ1 FY2716 Aug 20266 minIndustrials & Infra

Strong growth, margin durability, freight headwinds temper near-term

pricing power · industrial doubling · order book strength
TranscriptDeep diveQ1 FY2716 Aug 20266 minIndustrials & Infra

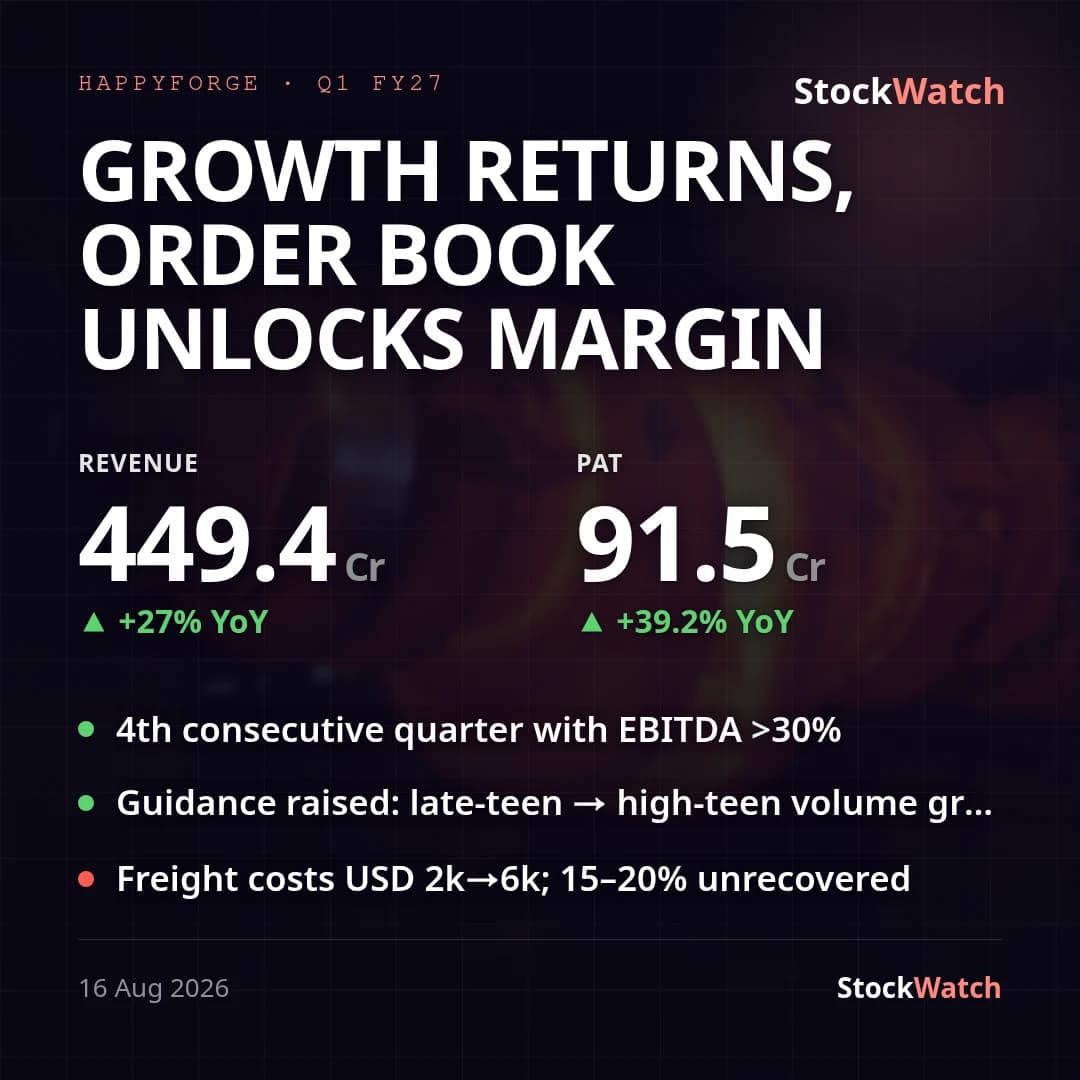
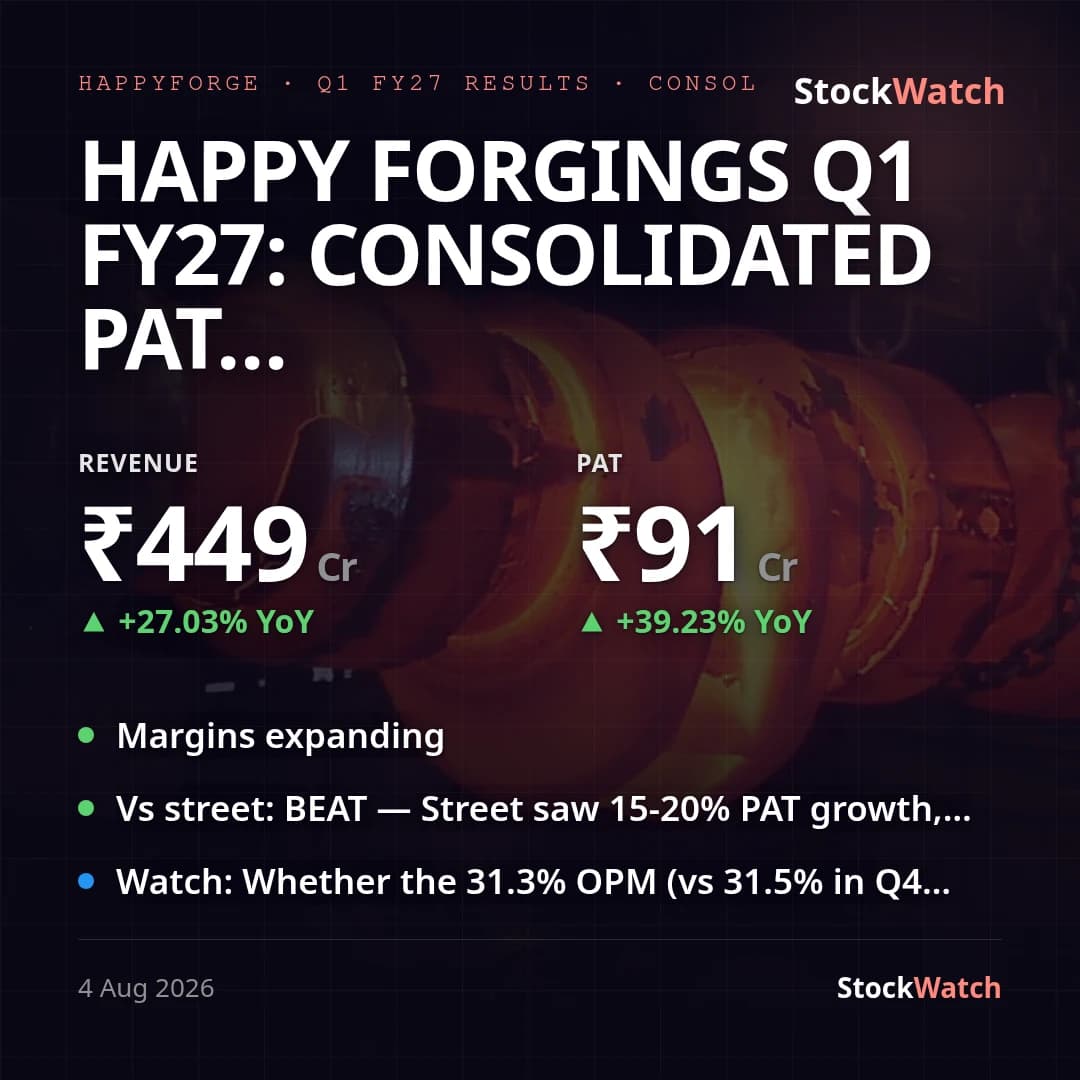
Happy Forgings Q1 FY27: consolidated PAT +39% YoY to ₹91.5 Cr as margins expand

auto components · forgings · margin expansion

ResultsQ1 FY2704 Aug 20263 minIndustrials & Infra
Latest
Board Meeting4 Aug, 3:02 pm

Happy Forgings Q1 FY27: consolidated PAT +39% YoY to ₹91.5 Cr as margins expand

Happy Forgings posted consolidated PAT of ₹91.46 Cr for Q1 FY27, up 39.2% YoY (₹65.69 Cr) and 9.5% QoQ (₹83.56 Cr), on revenue from operations of ₹449.42 Cr, up 27.0% YoY and 6.0% QoQ. Basic EPS came in at ₹9.70 versus ₹6.97 a year ago. Standalone and consolidated figures are effectively identical this quarter, with the sole subsidiary, HFL Technologies, contributing nil revenue. This is well ahead of the Street's pre-result expectation of 15-20% YoY PAT growth on revenue of roughly ₹400-420 Cr (per Motilal Oswal, ICICI Securities and other brokerage previews) — a clear beat on both the top and bottom line. Operating margin (EBITDA proxy: PBT − other income + finance costs + depreciation, over revenue from operations) was 31.3%, up ~275 bps YoY from 28.6% but essentially flat against Q4 FY26's 31.5% — resolving the pre-result question of whether 31.5% was a floor or a one-off: it held, without extending further this quarter. Net profit margin improved to 19.9% of total income, from 19.4% in Q4 FY26 and 18.0% a year ago. The expansion is coming mainly from operating leverage on employee costs (8.6% of revenue versus 9.1% a year ago) as volumes scaled, while the raw-material-to-revenue ratio stayed broadly stable (41.8% versus 41.2% YoY) — cost discipline held but wasn't the driver of the margin gain. Against management's own FY27 guidance from the Q4 FY26 concall — late-teen volume growth with EBITDA margins broadly in line with FY26 — the quarter tracks ahead: 27% revenue growth outpaces the "late-teens" framing even allowing for price/mix, and margins expanded rather than merely held. No press release or management commentary accompanied this filing beyond the standard board-outcome letter, so there is no fresh management framing to reconcile against this quarter. The period's other corporate activity — the 47th AGM (Jul 27), the FY26 BRSR filing, and the annual report dispatch to non-email shareholders — was routine governance with no bearing on the operating numbers; no new capex tranches or order-book wins were disclosed alongside this result.

4 Aug 2026, 03:02 pm

Corporate Events

Board MeetingHAPPYFORGE
2026
4Aug

Board Meeting

The meeting of the Board of Directors will be held to consid…

BSE Filing
Board MeetingHAPPYFORGE
2026
27Jul

Board Meeting

The 47th AGM will be held via Video Conferencing. Sharehold…

BSE Filing
DividendHAPPYFORGE
2026
20Jul

₹4 / share

BSE Filing
Board MeetingHAPPYFORGE
2025
6Nov

Board Meeting

approve unaudited financial results for the quarter and half…

BSE Filing
DividendHAPPYFORGE
2025
22Jul

₹3 / share

BSE Filing
Board MeetingHAPPYFORGE
2024
7Nov

Board Meeting

Consider, examine and approve Un-audited Standalone & Consol…

BSE Filing