StockWatch
·

HBL POWER SYSTEMS LTD.-$

BSE: 517271

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27
Revenue
877.70
+37.2%
Expenditure
654.51
+31.6%
Net Profit
178.46
+69.2%
OPM %
27.84%
+5.40pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.00245.76491.51737.27983.02Q1 FY25Q2 FY25Q3 FY25Q4 FY25Q1 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

HBL Engineering: Consolidated PAT Halves YoY to ₹193 Cr as Signalling Base Fades

rail signalling · kavach · high base effect

ResultsQ2 FY2707 Nov 20263 minIndustrials & Infra

Margin Recovery Test: Can HBL Engineering Stabilize Kavach Mix Pressure?

margins · Kavach · order intake

Result previewQ2 FY2707 Nov 20263 minIndustrials & Infra

HBL Engineering Q1FY27: consolidated PAT down 24% YoY as margins compress on Kavach mix

kavach orders · railway signalling · margin compression

ResultsQ1 FY2708 Aug 20263 minIndustrials & Infra
Latest
Board Meeting7 Nov, 2:01 pm

HBL Engineering: Consolidated PAT Halves YoY to ₹193 Cr as Signalling Base Fades

Consolidated PAT fell 50.2% YoY to ₹192.75 Cr (~₹193 Cr) on a 28.7% YoY revenue decline to ₹871.56 Cr, as the year-ago quarter's exceptionally strong Electronics-segment execution (rail-signalling/Kavach-linked) normalizes off a high base. Sequentially the picture is very different: revenue rose 36.6% QoQ and PAT 76.6% QoQ, comfortably clearing our own pre-result expected consolidated revenue range of ₹650–700 Cr by roughly 25–34%. The Electronics segment is the entire swing factor: revenue there fell to ₹363.23 Cr from ₹793.58 Cr YoY, and segment result to ₹145.67 Cr from ₹461.49 Cr, dragging consolidated OPM (profit before exceptional items/revenue) to 26.66% from 44.50% YoY and NPM (PAT/total income) to 21.57% from 31.26% — both nonetheless expanded QoQ from 23.42%/16.57%, pointing to sequential stabilization even as the YoY base effect dominates. The quarter also carried a ₹13.16 Cr exceptional gain (Telangana government compensation for compulsory land acquisition) against a ₹23.85 Cr exceptional expense a year ago; stripping both out, adjusted YoY PAT decline widens to roughly -56%, so the one-offs flatter rather than inflate the headline -50% print. Away from Electronics, the core franchise kept growing — Industrial Batteries revenue +11.1% YoY to ₹411.62 Cr, Defence & Aviation Batteries +176.6% YoY to ₹82.47 Cr. Management issued no formal guidance or outlook on record, and no press release commentary accompanied this filing, so there is no management framing to reconcile the numbers against. Analyst coverage remains sparse to the point of no tracked consensus, consistent with what our pre-result preview flagged, so there is no street estimate to grade this against either — the only available yardstick is our own pre-result range, which revenue cleared well. Separately, the Board's filing notes that associate Tonbo Imaging India Ltd listed on the main boards effective October 23, 2026, with the investment impact to flow into next quarter's consolidated numbers. With the Electronics high base now largely cycled through, the open question is whether that segment's revenue (₹363 Cr this quarter) stabilizes or re-accelerates on fresh order execution, and whether NPM/OPM keep climbing from this quarter's 21.6%/26.7% — neither resolved absent a concall or guidance on record this quarter.

7 Nov 2026, 02:01 pm

Board Meeting8 Aug, 4:20 pm

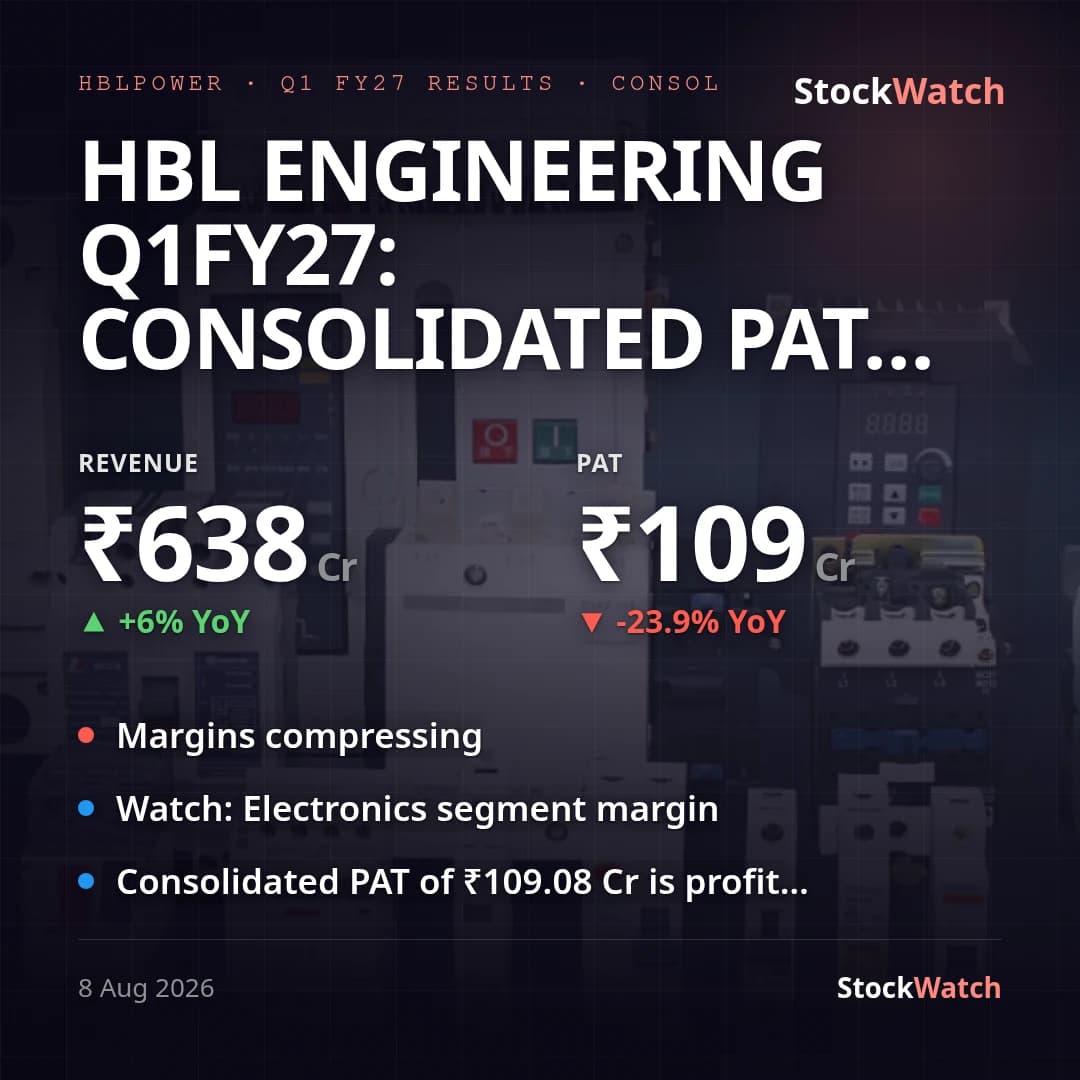
HBL Engineering Q1FY27: consolidated PAT down 24% YoY as margins compress on Kavach mix

HBL Engineering (formerly HBL Power Systems) reported consolidated revenue of ₹638.03 Cr for Q1 FY27 (quarter ended June 30, 2026), up 6.0% YoY from ₹601.77 Cr, but consolidated PAT attributable to shareholders fell 23.9% YoY to ₹109.08 Cr from ₹143.27 Cr a year ago. Exceptional items were negligible in both periods (a ₹0.01 Cr expense this quarter versus ₹3.11 Cr a year ago), so the decline is essentially like-for-like, not a one-off distortion. Standalone told the same story — PAT down 24.5% YoY to ₹105.47 Cr (EPS ₹3.81) on revenue of ₹619.54 Cr (+5.4% YoY) — confirming the compression is company-wide rather than a consolidation artefact. The gap between revenue growth and profit decline sits on margins: consolidated operating margin (profit before exceptional items/revenue) compressed to ~23.4% from ~31% a year ago, and net margin to 16.6% from 23.1%. Segment data shows this wasn't broad dilution but two specific pockets: Defence & Aviation Batteries revenue fell 48.5% YoY to ₹37.93 Cr and its segment result dropped 72% to ₹9.10 Cr (margin 24.0% vs 44.7%), while Electronics revenue actually grew 26.0% YoY to ₹227.31 Cr but its result fell 20.7% to ₹70.73 Cr (margin 31.1% vs 49.4%) — consistent with Kavach milestone billing carrying a lower-margin mix than the batteries-heavy volumes booked a year ago. Industrial Batteries, the largest segment, was comparatively steady (revenue +7.3% to ₹361.94 Cr, result -1.0% to ₹82.71 Cr). Unallocated costs also widened to a ₹17.46 Cr drag from ₹5.51 Cr, adding pressure below the segment line. No specific consensus PAT or revenue estimate for this quarter surfaced in a search, so the print can't be graded against street numbers. Against management's own commentary, though, this result tracks rather than misses expectations: following FY26 results, management guided that FY27 sales and profit would be significantly higher than FY26 but flagged that quarterly profitability would vary mainly because of the Kavach business — exactly the lumpiness visible in this quarter's Electronics and Defence & Aviation margins. No separate press release accompanied this filing; the only management commentary on record is the outcome-of-board-meeting letter, which adds no colour beyond the approved figures. Below the segment line, the Group's share of associates' results swung to a ₹1.77 Cr loss from a ₹1.51 Cr profit a year ago — a modest ₹3.3 Cr incremental drag against the ~₹34 Cr YoY PAT decline, and not the primary driver. Order momentum continued: a ₹31.49 Cr Kavach loco-equipment order from ICF (Aug 3) and a ₹24 Cr order from ICF Chennai (Jul 15), on top of the ₹1,714 Cr Kavach loco-equipment order from CLW won May 28 — orders feeding a reported ~₹1,900 Cr FY27 Kavach revenue target (₹1,000 Cr loco, ₹900 Cr station). The company also appointed Kavita Prasad Aluru as an Executive Director effective July 1. Sequentially, consolidated revenue rose 5.6% and PAT rose 71.1% QoQ off a soft Q4FY26 base (₹604.12 Cr revenue, ₹63.75 Cr PAT) — useful confirmation that the March quarter's dip wasn't a new trend, but with YoY as the primary lens, the QoQ jump doesn't offset the year-on-year margin story. Heading into Q2 FY27, the swing factor is whether Kavach loco and station billing normalizes Electronics and Defence & Aviation margins back toward last year's ~45-49% range as the CLW and ICF orders execute, or whether the mix stays margin-dilutive through the year as management's own caution suggests.

8 Aug 2026, 04:20 pm

Corporate Events

Board MeetingHBLENGINE
2026
7Nov

Board Meeting

The Board of Directors meeting is scheduled to consider and …

BSE Filing ↗
Board MeetingHBLENGINE
2026
26Sep

Board Meeting

The 40th Annual General Meeting will be held on Saturday, Se…

BSE Filing ↗
DividendHBLENGINE
2026
11Sep

₹3 / share

BSE Filing ↗
DividendHBLENGINE
2026
11Sep

₹1 / share

BSE Filing ↗
Board MeetingHBLENGINE
2026
8Aug

Board Meeting

The Board of Directors meeting is scheduled to consider and …

BSE Filing ↗
Board MeetingHBLENGINE
2026
1Jul

Board Meeting

The Board of Directors approved the change in role of Mrs. …

BSE Filing ↗
DividendHBLENGINE
2024
13Sep

₹1 / share

BSE Filing ↗
Board MeetingHBLENGINE
2024
8Aug

Board Meeting

consider and approve the unaudited financial results (standa…

BSE Filing ↗
Board MeetingHBLENGINE
2024
7Feb

Board Meeting

consider and approve unaudited financial results (standalone…

BSE Filing ↗