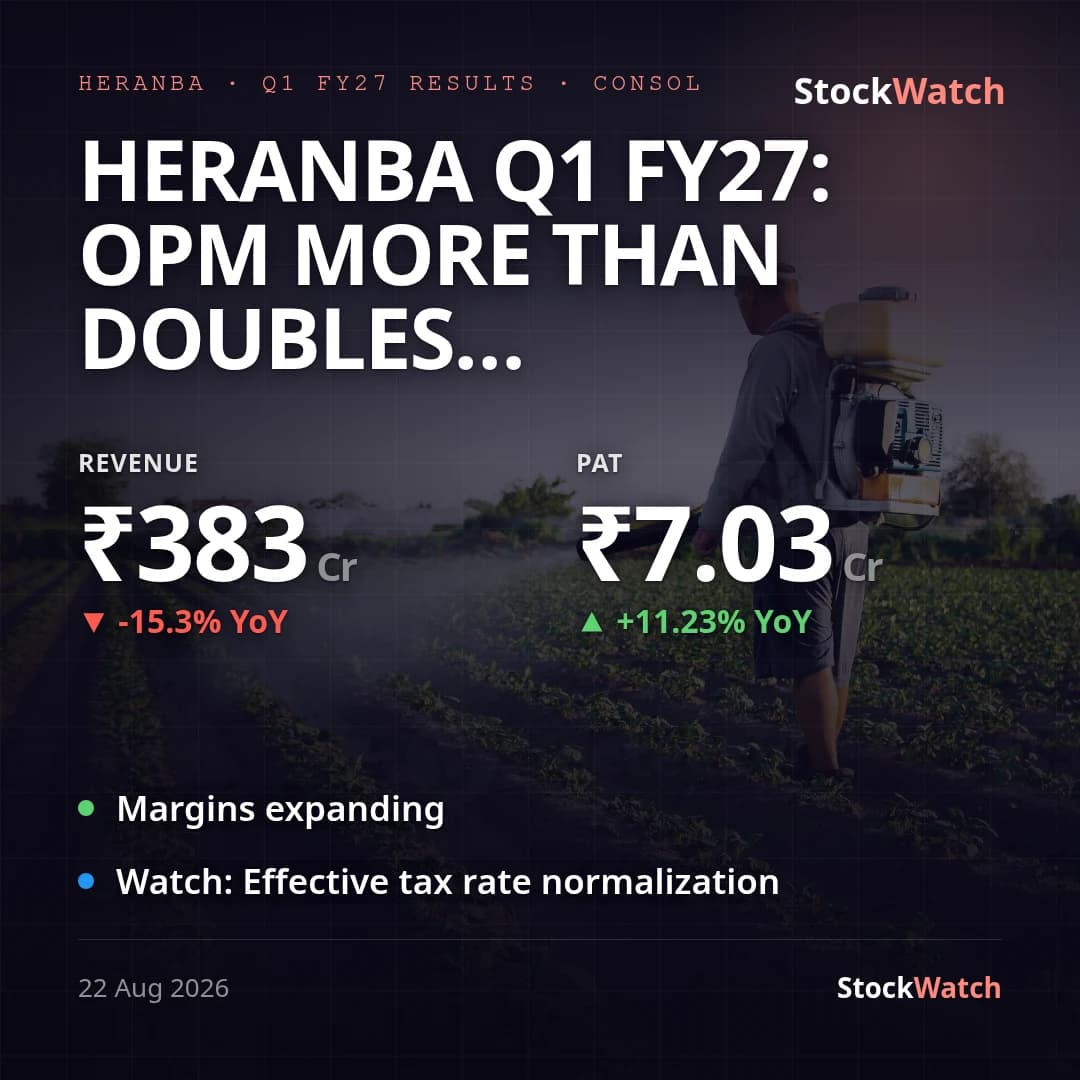
Heranba Q1 FY27: OPM more than doubles YoY, but revenue dip and tax spike cap PAT at +11%
Consolidated revenue came in at ₹383.20 Cr, down 15.3% YoY from ₹452.43 Cr, though up 19.9% QoQ from Q4 FY26's ₹319.48 Cr — the QoQ jump reflects the Kharif-season pickup typical for agrochemical makers and should be read as seasonality, not re-acceleration. Consolidated PAT was ₹7.03 Cr (owners' share ₹7.14 Cr), up 11.2% YoY from ₹6.32 Cr and a clean swing from Q4 FY26's ₹58.32 Cr consolidated loss. No brokerage previews or consensus estimates for this specific print turned up in a search — the results had already been postponed twice, most recently flagged on Aug 12 as an ERP-transition delay — so vs-street is unknown; management has no formal guidance on record either, so vs-guidance is also unknown.
The headline story is margin, not revenue: OPM (EBITDA/revenue) more than doubled YoY to 12.81% from 6.90%, and swung from -7.29% in Q4 FY26, driving PBT up 80.8% YoY to ₹20.10 Cr even as topline fell. That operating strength did not fully reach the bottom line, however — tax expense rose to ₹13.07 Cr from ₹4.80 Cr YoY, an effective rate of ~65% versus the standalone entity's 29.5%, driven by an ₹8.92 Cr deferred tax charge (against a ₹0.20 Cr credit in the standalone book). The gap between the 80.8% PBT jump and the 11.2% PAT growth is the main swing factor this quarter, and NPM improved only to 1.81% from 1.36% YoY as a result.
Segment mix shifted too: domestic sales rose to 79.95% of revenue (₹306.38 Cr) from 74.66% a year ago, while exports fell to 20.05% (₹76.82 Cr) from 25.34% YoY — the export decline is the chief driver of the YoY revenue fall. The standalone (parent-only) print is materially weaker than consolidated: standalone revenue fell 25.5% YoY to ₹364.99 Cr and standalone PAT fell 57% YoY to ₹9.46 Cr, a divergence from consolidated's 11.2% PAT growth that traces to subsidiary-level contribution. Alongside the results, the board approved a further ₹25 Cr investment in wholly-owned subsidiary Mikusu India Private Limited via rights issue; no management press release was available to cross-check against the print.
Going into Q2 FY27, the two swing factors to track are whether the elevated ~65% consolidated tax rate normalizes and whether export revenue recovers from its 20% share low — both currently offsetting an otherwise sharp operating-margin recovery.