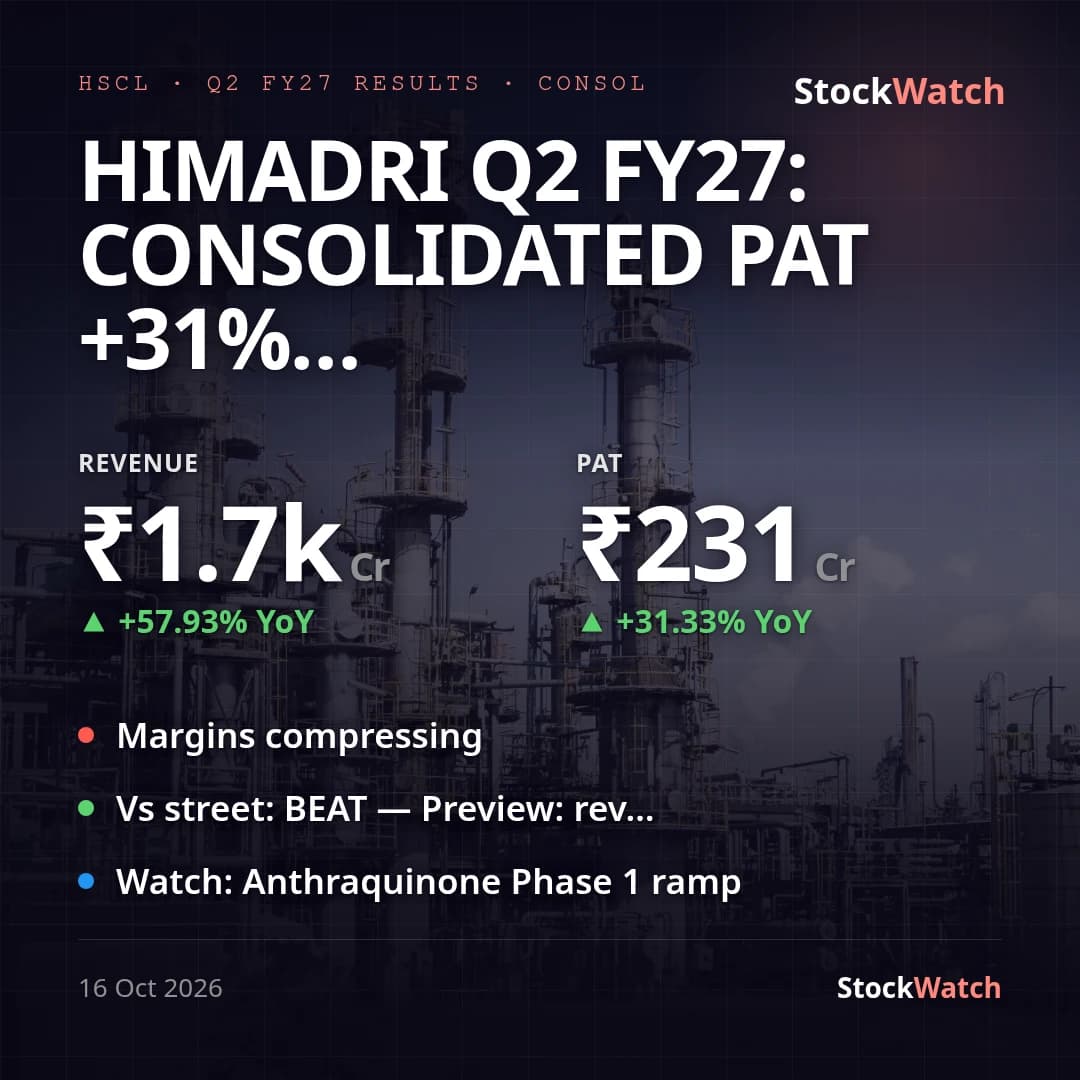
Himadri Q2 FY27: Consolidated PAT +31% YoY to ₹231 Cr, Margins Slip on 58% Revenue Jump
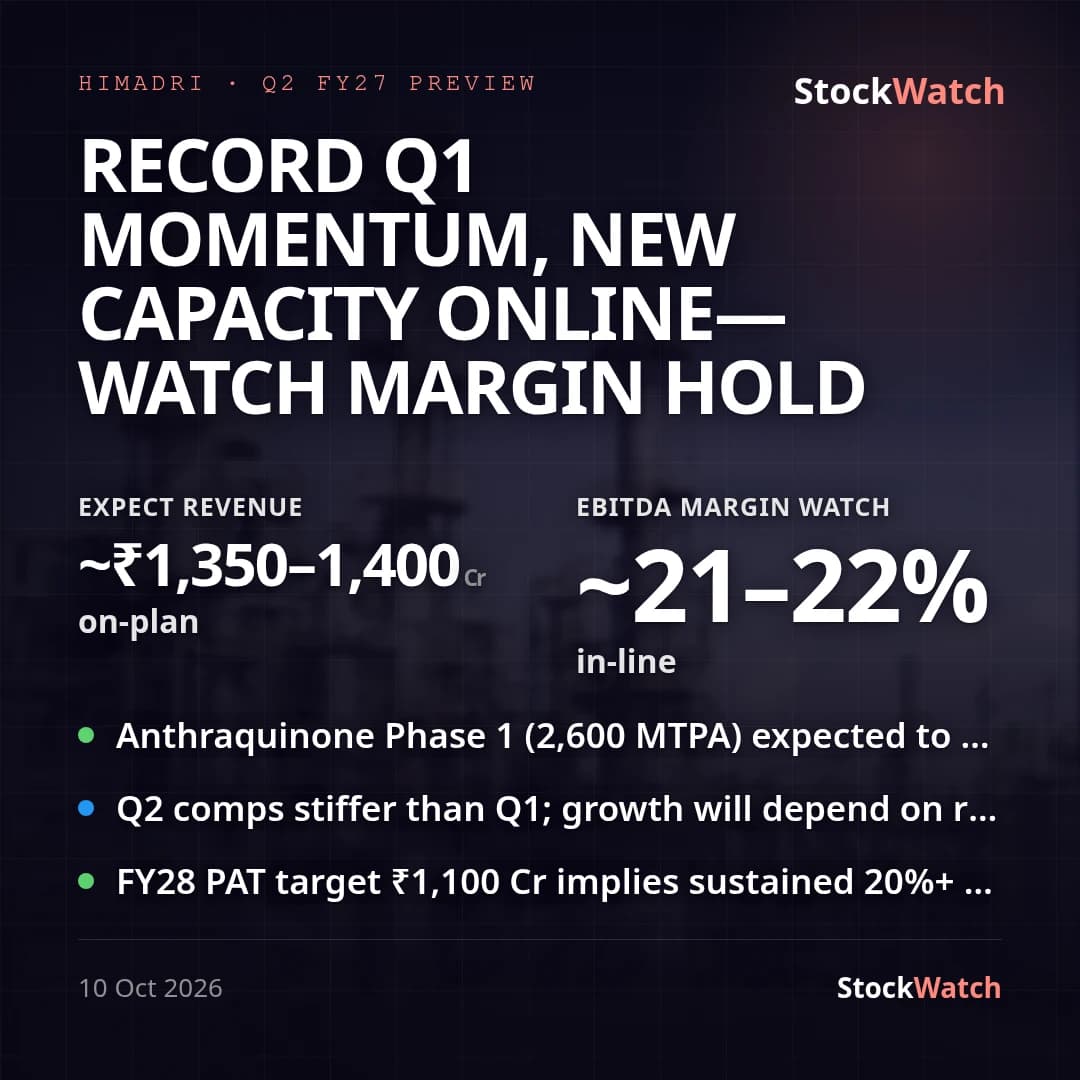
Himadri Speciality Chemical's consolidated PAT rose 31.3% YoY to ₹231.32 Cr (EPS ₹4.60 vs ₹3.58) on revenue of ₹1,691.43 Cr, up 57.9% YoY and 18.1% QoQ from ₹1,431.88 Cr in Q1 FY27. Against our pre-result preview (consolidated revenue ₹1,350–1,400 Cr, PAT ₹210–230 Cr), the top line beat by roughly 21% above the high end while PAT landed just above the top of the range — a clear revenue beat that only partially converted to the bottom line.
The gap is a margin story: operating margin (per the filing's own ratio, PBT + depreciation + finance costs − other income, over revenue) came in at 17.93%, down from 22.21% in the year-ago quarter and 21.87% last quarter; net profit margin fell to 13.68% from 16.45% YoY and 15.95% QoQ. In absolute terms that operating-profit measure works out to roughly ₹303 Cr — squarely inside the preview's ₹300–310 Cr EBITDA-band despite revenue running ~21% ahead of what the preview assumed, meaning the incremental revenue carried materially lower margin than the base business. Finance costs held flat YoY (₹27.72 Cr) and the tax rate was unremarkable (24.7% of PBT), so the squeeze sits upstream, in cost of materials and other expenses, consistent with a richer mix from newly consolidated, lower-margin units.
Standalone (parent-only) tells a milder version: revenue of ₹1,542.67 Cr grew 44.1% YoY and PAT of ₹239.77 Cr grew 28.3% YoY — both well short of the consolidated growth rates. The divergence traces to the "Others" segment (₹144.14 Cr this quarter, nil in the year-ago quarter), which reflects Himadri Integrated Minerals and Resources (consolidated from February 2026) and Ardent Impex Fzco, Dubai (from June 2026) — businesses with no footprint in the September-2025 base, so part of the headline consolidated growth is a consolidation effect rather than organic expansion. Street coverage remains thin, as flagged pre-result (effectively one analyst on record, Hold rating, targets split ₹480–720), so there is no independent quarterly consensus to check against beyond that FY27 full-year estimate (+34.8% revenue, +23.8% EPS, per Trendlyne) — this quarter's growth pace is broadly consistent with that trajectory. Management issued no press release alongside this filing (none available in our records), so there is no fresh management framing to reconcile against the numbers this quarter.
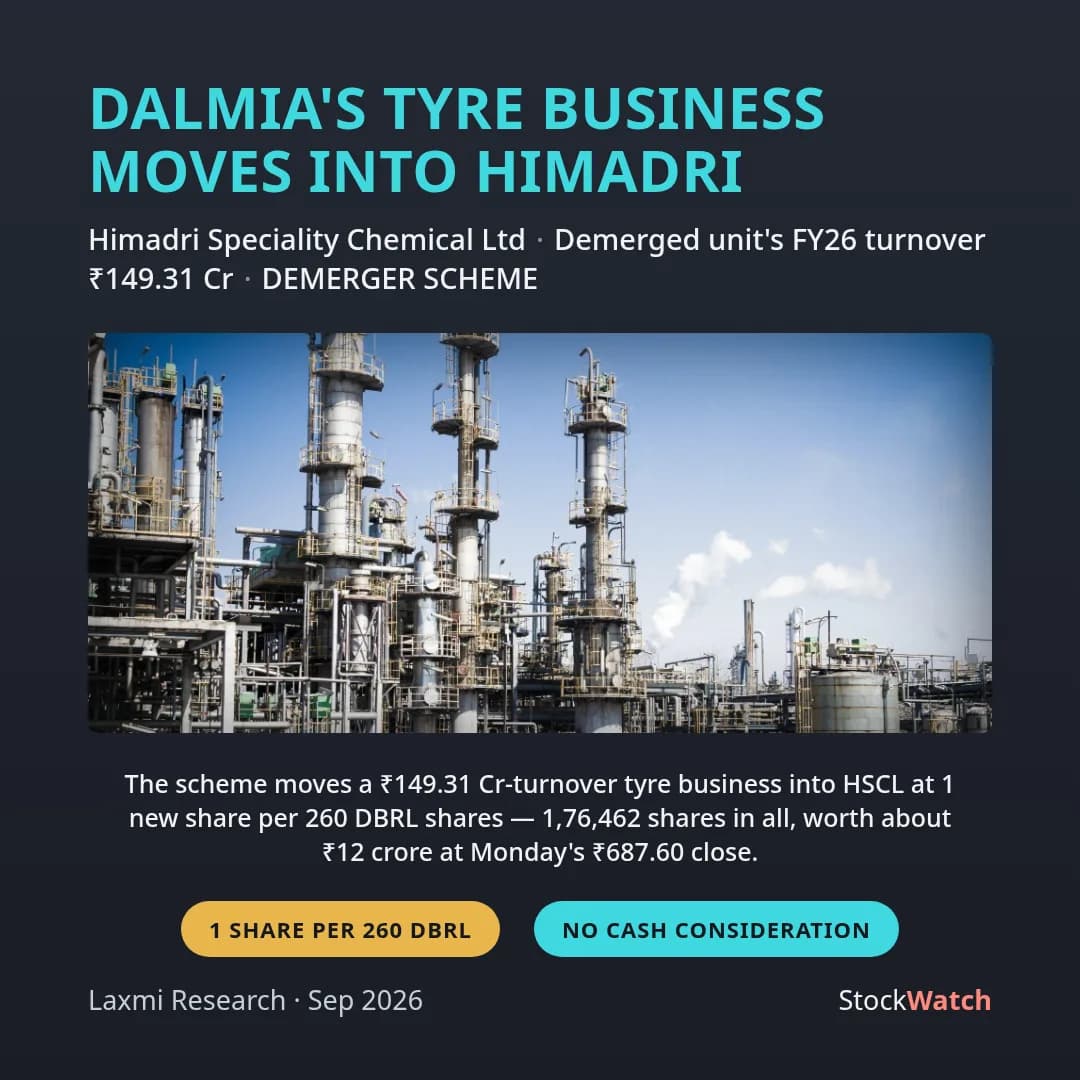
Against the FY28 targets set out on the last call (₹1,100 Cr PAT, ₹2,000 Cr self-funded capex over FY27-28, ₹3,000 Cr LFP cathode revenue potential, Birla Tyres EBITDA-positive in FY27), H1 FY27 consolidated PAT stands at ₹459.75 Cr and segment capex continues (₹173–215 Cr spent on property/plant in H1 per the cash-flow statement) — directionally on track but still shy of the run-rate needed to hit ₹1,100 Cr by FY28, so the targets stay "on-plan" rather than confirmed. In-quarter corporate actions — the board's approval of the DBRL tyre-business demerger into HSCL (Sept 21, 2026, scheme filed with exchanges), a ₹150 Cr commercial paper raised and repaid within the quarter, and a 34% stake sale in a step-down subsidiary — did not flow through this P&L in a material way but mark continued portfolio and balance-sheet activity around the capacity build-out.