HPL Electric: revenue jumps 35% YoY but consolidated PAT nearly flat as margins compress
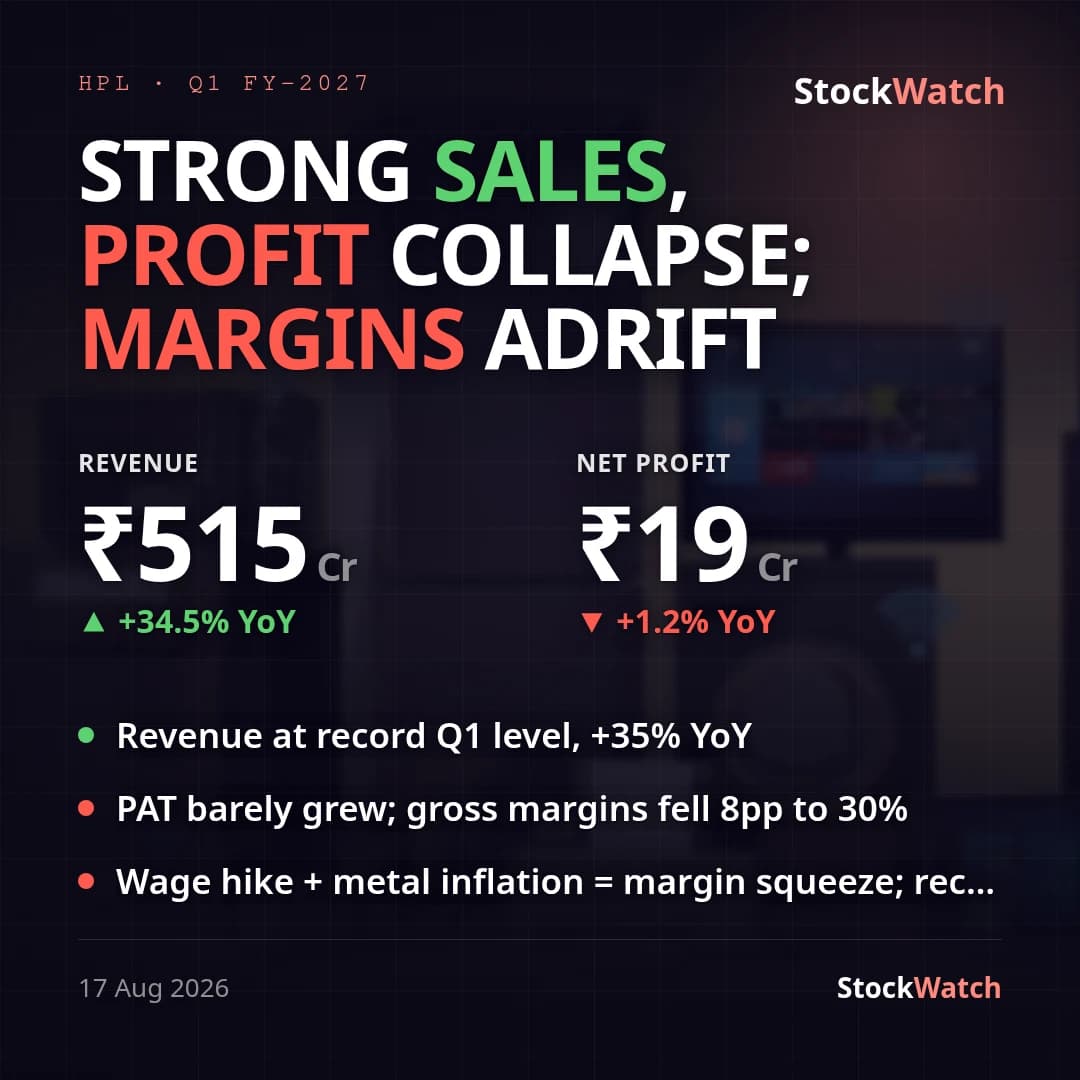
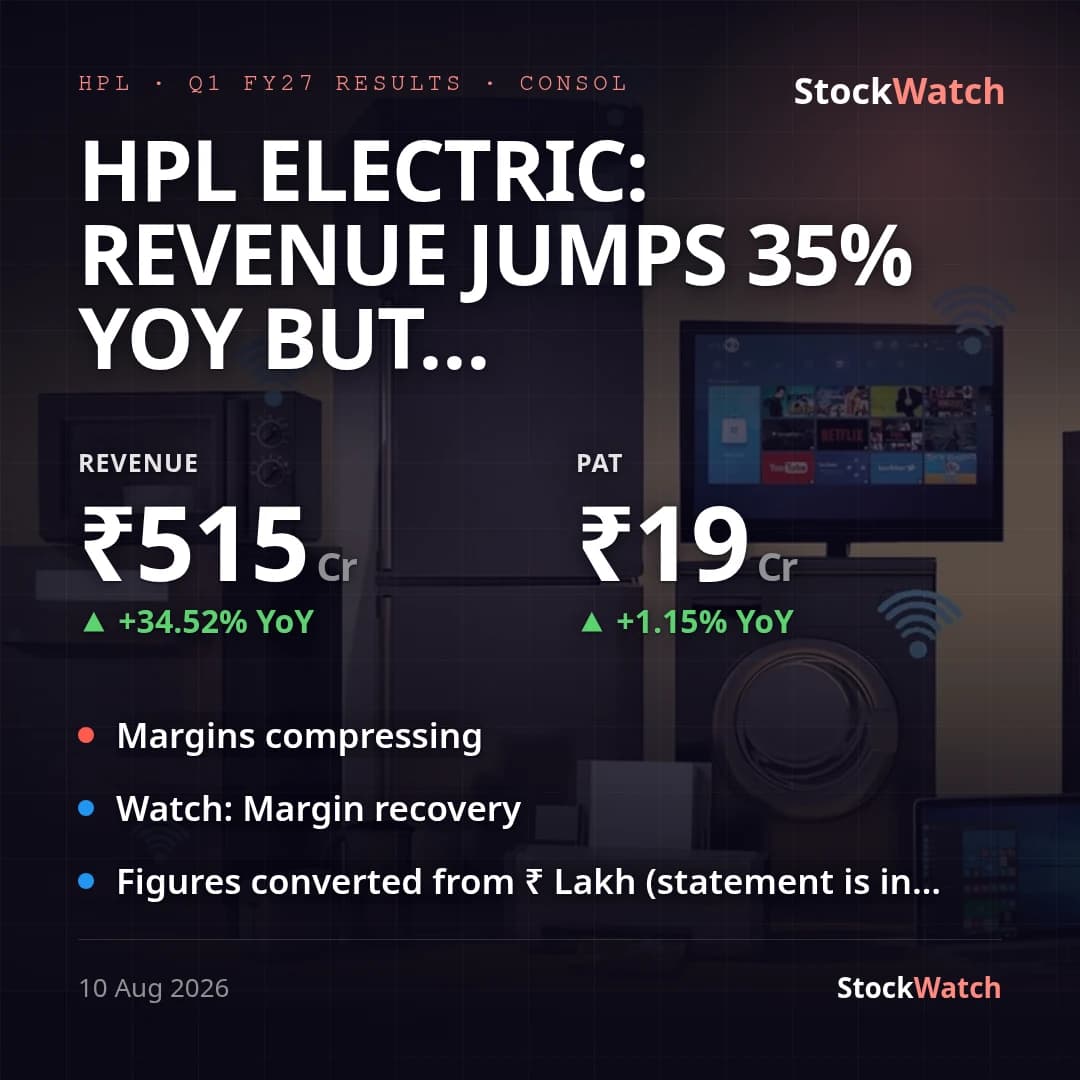
HPL Electric & Power posted consolidated Q1 FY27 revenue of ₹515.24 Cr, up 34.5% YoY (₹383.03 Cr) though down 0.9% sequentially from a seasonally strong Q4 FY26 (₹519.70 Cr). Consolidated PAT was ₹18.69 Cr, up just 1.2% YoY (₹18.48 Cr) — profit growth trailed revenue growth by a wide margin — and fell 39.5% QoQ from ₹30.90 Cr, though the QoQ drop is largely a seasonality artifact given Q4 is typically the strongest billing quarter for this business. Standalone PAT was slightly lower at ₹17.91 Cr on ₹512.86 Cr revenue.
The gap between revenue and profit growth traces to margin compression on both lines: OPM fell to 12.3% from 15.1% a year ago and 16.5% last quarter, while NPM slipped to 3.6% from 4.8% YoY. By segment, Consumer & Industrial (C&I) revenue surged 55.0% YoY to ₹277.59 Cr, but segment margin fell to 8.4% from 11.3% YoY (and from 9.1% in Q4 FY26), consistent with the higher-share wires-and-cables mix and elevated commodity costs management had flagged. The Metering, Systems & Services segment grew revenue a more modest 16.5% YoY to ₹237.65 Cr, but its segment result fell 6.5% YoY as margin compressed to 14.2% from 17.7%.
Management's June 2026 concall guidance had projected margin recovery in "coming quarters" as commodity inflation eased and price adjustments took hold — that recovery did not show up this quarter; C&I margin instead extended its decline, so the print reads as a miss against that specific guidance line even as the broader growth themes tracked. The C&I revenue run-rate (₹277.59 Cr in Q1, annualising above ₹1,000 Cr) remains consistent with management's FY27 target of crossing ₹1,000 Cr in that segment. No press release or analyst consensus for this specific quarter was available to benchmark against street expectations, and the filing carries no company-specific corporate developments this quarter beyond the routine board meeting, an unclaimed-dividend reminder and the insider trading window closure — none of which bear on the operating numbers.
Going into Q2 FY27, the key swing factor is whether the margin recovery management promised on the last call finally shows up, given Q1 moved in the opposite direction on both the OPM and C&I-margin metrics.