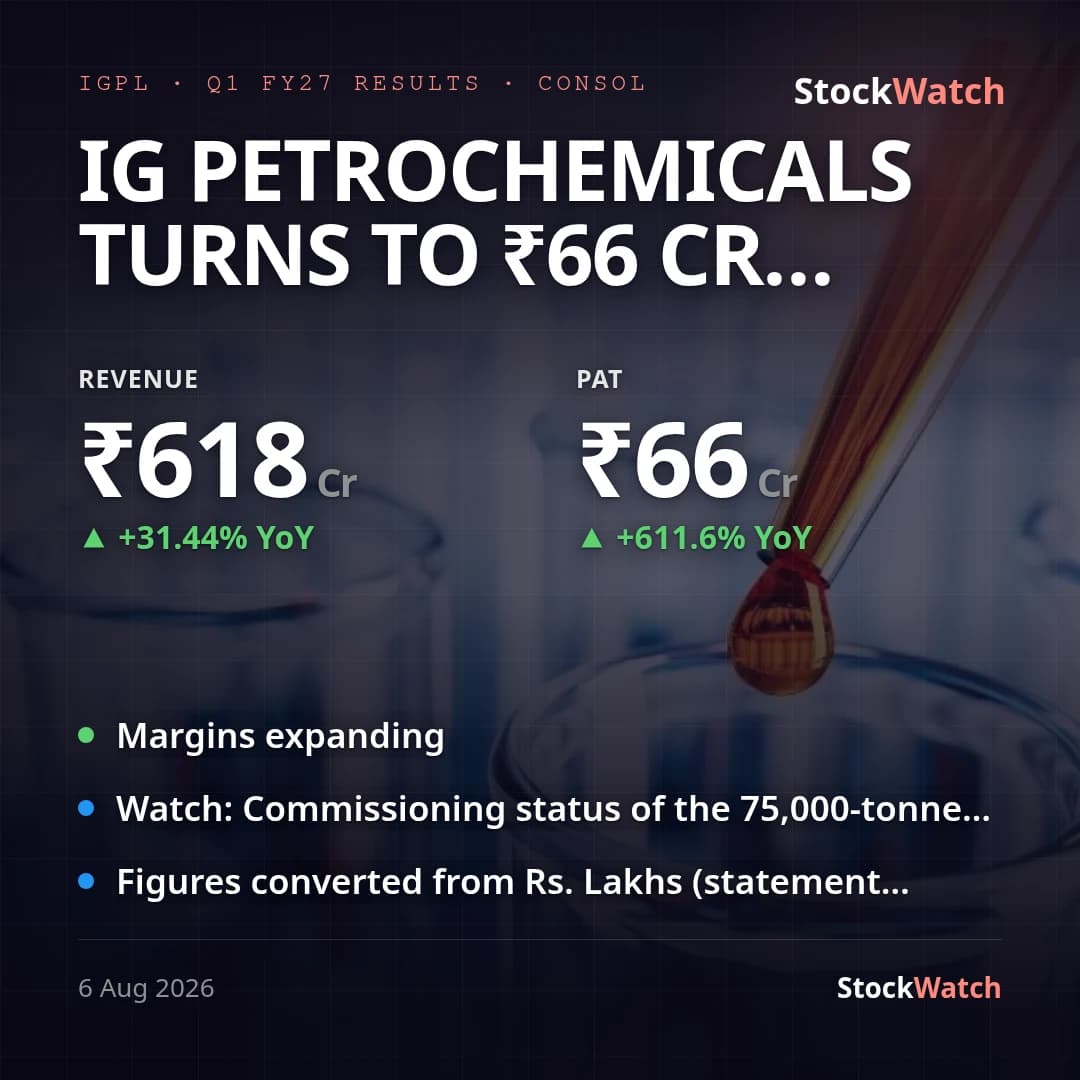
IG Petrochemicals turns to ₹66 Cr consolidated profit in Q1 FY27 as margins triple YoY
IG Petrochemicals (consolidated, primary basis) posted ₹66.44 Cr of net profit in Q1 FY27, a clean swing from a ₹12.99 Cr loss in the year-ago quarter and up 136.7% sequentially from ₹28.07 Cr in Q4 FY26. Revenue from operations rose 31.4% YoY and 17.8% QoQ to ₹617.80 Cr. The bigger move is on margins: OPM (EBITDA margin) expanded to roughly 18.2% from -0.15% a year ago and 12.71% last quarter, while NPM flipped to +10.7% from -2.7% YoY. There are no exceptional items in either statement, so both the revenue and profit swings are operating in nature and the reported YoY change needs no adjustment.
This lines up with what management told investors on the Q3 FY26 concall (Feb 2026) — that the period of subdued demand and compressed margins had "bottomed out," with a significant improvement expected from Q4 FY26 onward. Q1 FY27's numbers extend that recovery further, with OPM stepping up again from Q4 FY26's 12.71% to ~18.2%. Part of the expense relief came from a ₹65.14 Cr negative change in inventories (an inventory drawdown that reduces reported expense) — worth watching whether this recurs or was a one-off destocking benefit next quarter. Current tax jumped to ₹22.58 Cr from nil a year ago, consistent with the return to taxable profitability rather than any one-off tax item. Standalone PAT of ₹70.97 Cr ran about 6.8% above the consolidated ₹66.44 Cr, the gap coming from roughly ₹4.77 Cr of net losses at the Group's four subsidiaries (IGPL International, IGPL Energy — under liquidation, IG Biofuels, IGPL Charitable Foundation) that management certifies as not material to the group.
No formal analyst consensus for this specific quarter turned up in a web search; brokerages appear to be waiting on the August 7, 2026 earnings call rather than publishing a pre-result preview, so the print's standing versus Street is unknown rather than estimated. Against management's own prior guidance, the quarter reads as broadly met: the flagged margin recovery has materialized. What the filing and this quarter's corporate-action list (BRSR filing, 37th AGM notice, insider-trading window closure, the May 2026 reappointment of Sagar Jadhav as Executive Director) do not confirm is the commissioning status of the 75,000-tonne plasticizer plant management had targeted for March 2026 completion — that project was flagged to add ~₹1,000 Cr of revenue at full capacity, and its status needs verifying on the upcoming call since nothing in this quarter's numbers or disclosures speaks to it directly. Going into Q2 FY27, the read-through is that the sequential recovery from the FY26 trough is intact and broadening — both revenue and margins improving together — with the open questions being the plasticizer plant's progress and whether the current ~18% OPM holds once any inventory-drawdown effect normalizes.