StockWatch
·

IFB INDUSTRIES LTD.

BSE: 505726

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27·vs Q2 FY26
Revenue
1.5K
-1.1%+14.0%
Expenditure
1.5K
-1.3%+15.9%
Net Profit
39.56
+3.9%-20.5%
OPM %
5.56%
+0.12pp-1.70pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.00428.15856.291.3K1.7KQ2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

Operating leverage broke. Margins won't recover on the timeline management implied.

margin compression · cost initiatives · commodity headwinds

Result verdictFollow-upQ2 FY2710 Nov 20266 minConsumer & Retail

Margin squeeze deepens; growth aspirational, execution softer

margin compression · cost initiatives · commodity/forex headwinds

TranscriptDeep diveQ2 FY2710 Nov 20266 minConsumer & Retail

IFB Industries Q2 FY27: consolidated PAT falls 25% YoY to ₹38 Cr as appliance margins compress

home appliances · margin compression · consolidated results

ResultsQ2 FY2727 Oct 20263 minConsumer & Retail
Latest
Quarterly Result27 Oct, 7:10 pm

IFB Industries Q2 FY27: consolidated PAT falls 25% YoY to ₹38 Cr as appliance margins compress

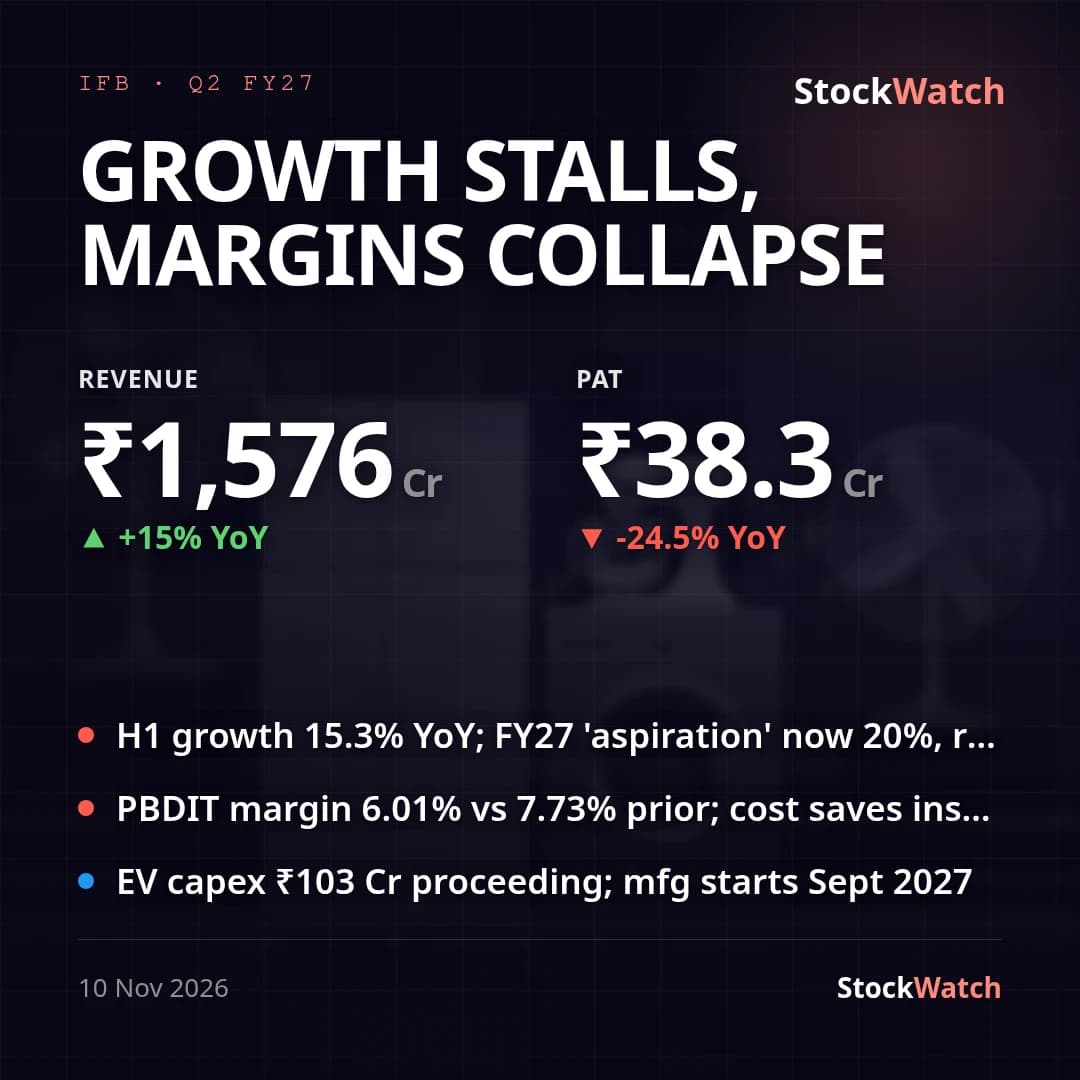
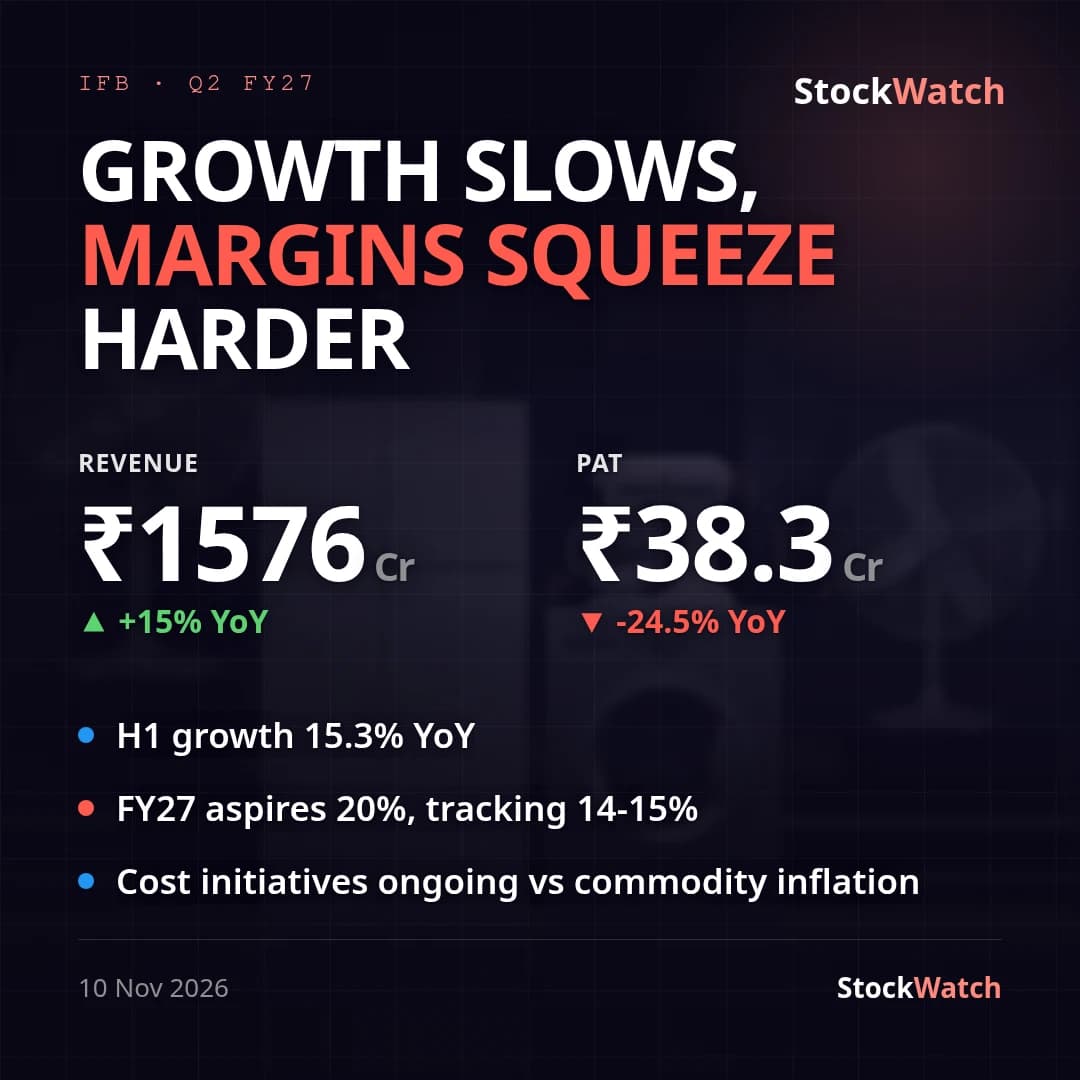
IFB Industries' consolidated revenue grew 15.0% YoY to ₹1,575.78 Cr (₹1,370.43 Cr) but was flat sequentially (-0.6% vs ₹1,584.74 Cr), while consolidated PAT fell 24.5% YoY to ₹38.34 Cr (₹50.79 Cr) and 10.9% QoQ (₹43.05 Cr), with EPS down to ₹9.47 from ₹12.53. There were no exceptional items in either period, so the decline is entirely operating — this is a margin-compression quarter, not a one-off. The squeeze sits in the core home appliances segment (77% of consolidated revenue): PBIT there fell 38.6% YoY to ₹33.32 Cr even as segment revenue grew 11.7% to ₹1,220.86 Cr, pulling segment PBIT margin down to roughly 2.7% from ~5.0% a year ago. That matches the "persistent commodity/forex strain" management flagged on the Q1 FY27 call — consolidated PBDIT-style margin came in near 5.3% this quarter, below both the year-ago 7.28% and management's own 5.8% FY27 target, so the guided-against risk materialised and margin undershot the target. Partially offsetting it, engineering PBIT rose 24% YoY to ₹36.21 Cr even though engineering revenue itself fell 11.8% YoY to ₹303.69 Cr this quarter (H1 engineering revenue is still up 21.4%, within the company's ₹2,000 Cr / 20-25% growth band, so the Q2 dip looks like order-timing rather than a trend break). The equity-accounted associate, IFB Refrigeration, added a further drag, with its share of loss widening to ₹6.56 Cr from ₹1.75 Cr YoY; there is no non-controlling interest, so the full consolidated profit of ₹38.34 Cr accrues to owners. Management's prior guidance (Q1 FY27 call) targeted FY27 H1AD revenue growth of 20%+, since trimmed to 18%, alongside the ₹150 Cr cost-reduction program (₹42 Cr realised in Q1). H1 FY27 consolidated revenue growth now stands at 16.7% YoY (₹3,160.52 Cr vs ₹2,708.74 Cr), trailing even the revised-down 18% bar, so growth is running a touch below guidance; the margin outcome also missed the 5.8% PBDIT target. We could not find brokerage consensus estimates for this print, so the quarter cannot be scored against Street expectations (vsStreet: unknown). No management press release was available alongside this filing to cross-check against the company's own framing of the quarter. Standalone PAT of ₹39.56 Cr on revenue of ₹1,505.28 Cr (EPS ₹9.77) tracks closely with the consolidated number, reflecting that the associate loss is the main reconciling item between the two. Going into Q3 FY27, the quarter sets up three things to track: whether home appliances PBIT margin recovers from ~2.7% toward the 5.8% PBDIT target as the cost-initiative program scales past its ₹42 Cr Q1 run-rate, whether engineering segment revenue resumes YoY growth after this quarter's 11.8% dip, and whether the IFB Refrigeration associate loss (₹6.56 Cr this quarter) stabilises or keeps widening.

27 Oct 2026, 07:10 pm

Board Meeting6 Aug, 8:41 pm

IFB Q1FY27: consolidated PAT +65% YoY to ₹43 Cr, engineering margin trails target

IFB Industries' consolidated PAT (the primary basis) rose 64.6% YoY to ₹43.05 Cr on revenue of ₹1,584.74 Cr, up 18.4% YoY, with EPS at ₹10.62 versus ₹6.46 a year ago. Neither this quarter nor the year-ago quarter carried exceptional items, so this growth is entirely underlying — adjusted and reported YoY PAT growth are the same 64.6%. Sequentially the picture is far more muted: revenue grew just 5.8% and PAT only 0.9% over Q4 FY26, and consolidated NPM actually eased slightly to 2.72% from 2.83% in Q4 even as it expanded sharply from 1.94% a year earlier — the YoY margin expansion is the real story, not the flat QoQ print. Standalone PAT grew a slower 50.1% YoY to ₹38.06 Cr, a divergence of roughly 14.5 percentage points from the consolidated number. The gap traces to subsidiaries and the associate: consolidated pre-tax, pre-associate profit of ₹56.87 Cr already exceeds standalone's ₹51.54 Cr by ₹5.33 Cr, and the IFB Refrigeration associate added a further ₹0.33 Cr — together explaining why the parent-only print understates the group's improvement. On the cost side, material and purchase costs scaled roughly in line with revenue while employee costs (₹113.85 Cr) and other expenses (₹360.32 Cr) grew more slowly, giving the operating leverage behind the YoY margin gain. Against management's FY27 guidance from the Q4 FY26 concall — over 20% home-appliances revenue growth and 20-25% engineering growth with a 17-18% EBITDA margin target for engineering — the quarter runs slightly behind. Home appliances revenue (consolidated) grew 19.4% YoY to ₹1,268.69 Cr, just under the >20% bar, while engineering grew 18.4% YoY to ₹279.79 Cr, below the guided range, with engineering segment PBIT margin of only 11.6% (12.3% standalone) — well short of the 17-18% EBITDA-margin target management had flagged, consistent with its own caveat that commodity and forex headwinds have not been fully offset yet. No analyst consensus estimates for this quarter could be located, so the print cannot be benchmarked against Street numbers; no management press-release commentary was available either, so this read rests on the filed statements alone. Corporate developments this quarter — the board's Q1 results approval, the AGM/annual report release, and the passing of director Ashok Bhandari on August 4 — are administrative and don't bear on the operating numbers.

6 Aug 2026, 08:41 pm

Corporate Events

Board MeetingIFBIND
2026
27Oct

Board Meeting

The meeting of the Board of Directors is scheduled to consid…

BSE Filing ↗
Board MeetingIFBIND
2026
6Aug

Board Meeting

The Board Meeting has been rescheduled to consider and appro…

BSE Filing ↗
Board MeetingIFBIND
2026
29Jul

Board Meeting

The 50th Annual General Meeting of the Company will be held …

BSE Filing ↗
Board MeetingIFBIND
2026
6Jun

Board Meeting

The Board of Directors of the Company met on 06 June 2026. …

BSE Filing ↗
Board MeetingIFBIND
2024
26Oct

Board Meeting

Consider And Take On Record The Unaudited Financial Results …

BSE Filing ↗
Board MeetingIFBIND
2024
25Jan

Board Meeting

consider and approve Un Audited Standalone and Consolidated …

BSE Filing ↗
Board MeetingIFBIND
2023
2Nov

Board Meeting

Consider and approve the UnAudited Financial Results of the …

BSE Filing ↗
Board MeetingIFBIND
2023
30Oct

Board Meeting

Consider and approve Un Audited Standalone and Consolidated …

BSE Filing ↗