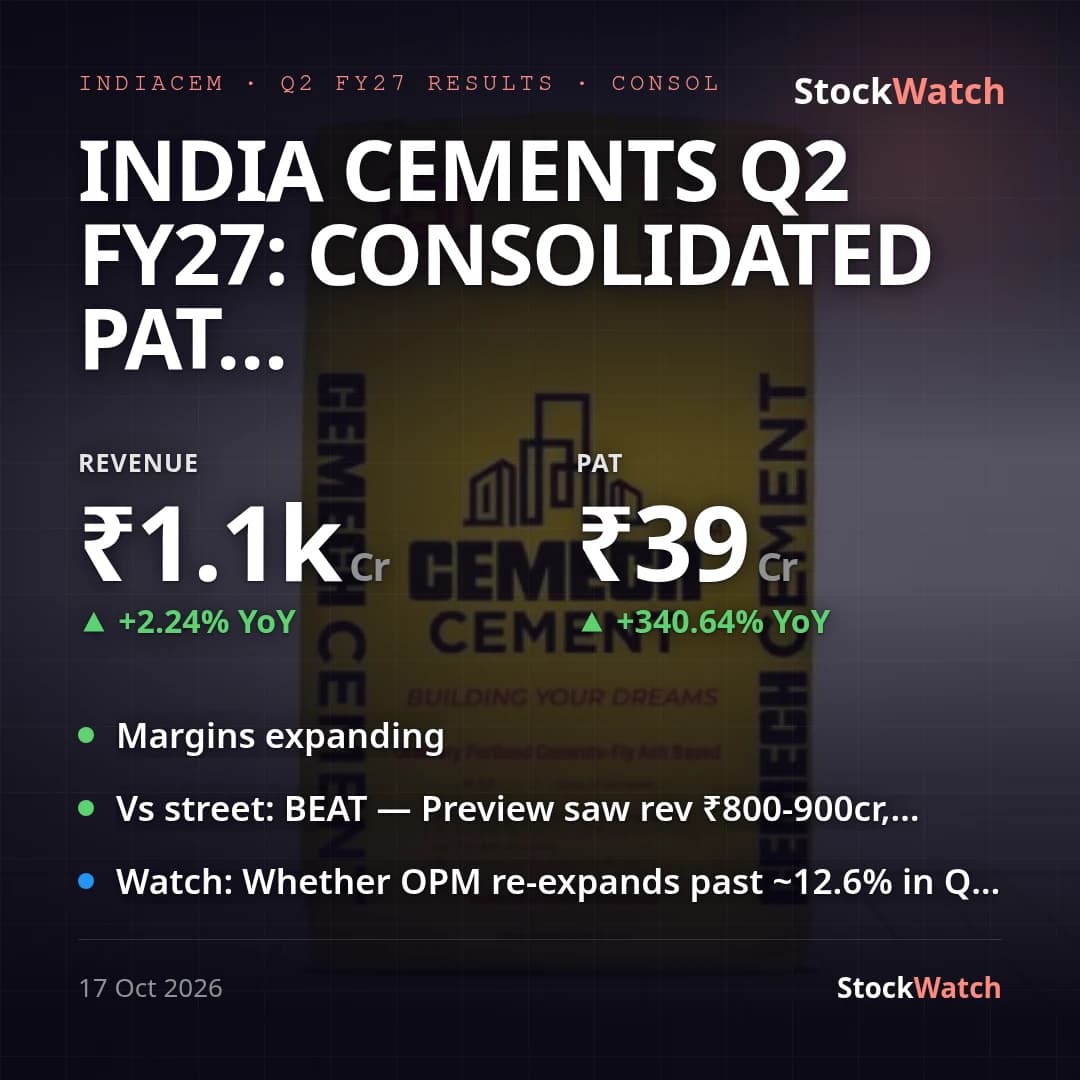
India Cements Q2 FY27: Consolidated PAT Surges to ₹38.8 Cr as Margin Gains Hold Near 13%
India Cements' consolidated PAT for Q2 FY27 (quarter ended 30 September 2026) came in at ₹38.82 Cr, up 340.6% YoY from ₹8.81 Cr and up 44.6% QoQ from ₹26.85 Cr, on revenue of ₹1,142.03 Cr (+2.2% YoY, +12.0% QoQ). EPS was ₹1.25 against ₹0.28 a year ago. The YoY jump is flattered by an unusually thin base: the year-ago quarter carried a ₹6.01 Cr exceptional charge offset by a deferred-tax credit; normalising both on a consistent tax basis, underlying YoY PAT growth is actually higher, at roughly 402%, since this quarter carries no exceptional item at all (vs ₹25.28 Cr in Q1 FY27 and ₹6.01 Cr a year ago). Either way the direction is the same — large, base-effect-adjusted profit growth as the company works through FY26's UltraTech-integration turnaround — but the headline multiple says more about how thin the comparison base was than about a step-change in the business this quarter.
Margins tell a more measured story than the PAT headline. Consolidated OPM was 12.64% this quarter, essentially flat against Q1 FY27's 12.80% (down 16 bps) and well above the year-ago 6.73%; NPM rose to 3.39% from 2.62% QoQ and 0.77% YoY. Crucially, pre-exceptional PBT actually fell 14.4% sequentially, to ₹52.28 Cr from ₹61.08 Cr in Q1 — the entire QoQ profit rise to ₹38.82 Cr is explained by Q2 carrying zero exceptional charges versus Q1's ₹25.28 Cr hit, not by any operating improvement. That lines up with India Cements' own Q1 commentary flagging Q2 as seasonally softer on monsoon and West Asia-linked cost pressure; the 44.6% QoQ PAT 'growth' is a one-off-driven artifact, not a margin-acceleration signal.
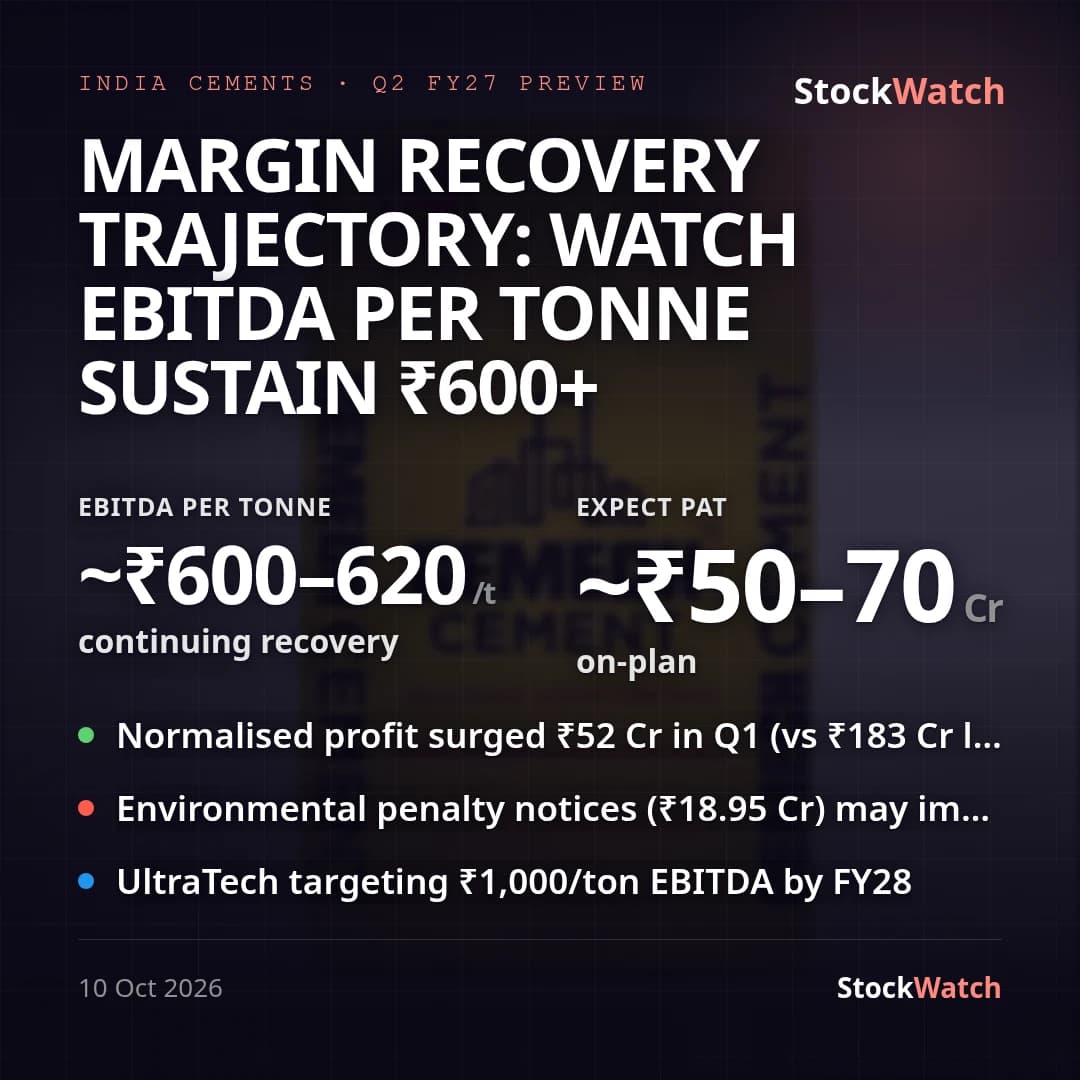
Against our pre-result preview (EBITDA/tonne ~₹600-620/t, normalised PAT ₹50-70 Cr, revenue ₹800-900 Cr), the print is a revenue beat — ₹1,142 Cr against the ₹800-900 Cr estimate — while normalised profitability (PBT before exceptional items, ₹52.28 Cr) landed within the flagged ₹50-70 Cr band, nearer the low end; per-tonne EBITDA can't be independently verified from this filing since volumes aren't disclosed. No broker-specific Q2 estimate turned up beyond our own preview; full-year Street consensus (FY27 revenue ~₹5,340 Cr, EPS ₹9.20, 'Sell'-leaning rating, median target ₹402.50) is unchanged background rather than a quarter-specific check. Against management's FY26-concall guidance — 7-8% volume growth, double-digit FY27 growth, cost efficiency above ₹300/tonne, and leverage under 1x — this filing only confirms the balance-sheet leg: consolidated debt-equity is 0.16x and net worth ₹10,189 Cr, comfortably inside the <1x target; volume data isn't disclosed in this statement, so the 7-8% growth claim can't be verified here. Two long-running legal matters remain unresolved and unprovided for — a ₹187.48 Cr CCI penalty under Supreme Court review and a ₹120.34 Cr asset-attachment order from 2015 — both carried with auditor emphasis-of-matter notes but no P&L impact this quarter.
The quarter's two renewable-energy stake purchases (26% in Amplus TN One Energy on 2 September, 3.62% in Zenataris Renewable Energy on 15 October) are too small to register in this P&L. The pre-result watch item on a ₹18.95 Cr environmental provision does not appear as a distinct line in this statement — H1 cash flow shows a ₹55.26 Cr 'Provision for Liabilities' that isn't broken out further — so it can't be confirmed as having materialised from this filing alone. No standalone management press release or commentary was available for this result beyond the regulatory filing itself.