INOX India Q1 FY27: consol. PAT slips 5% YoY to ₹58 Cr as margins compress on higher costs
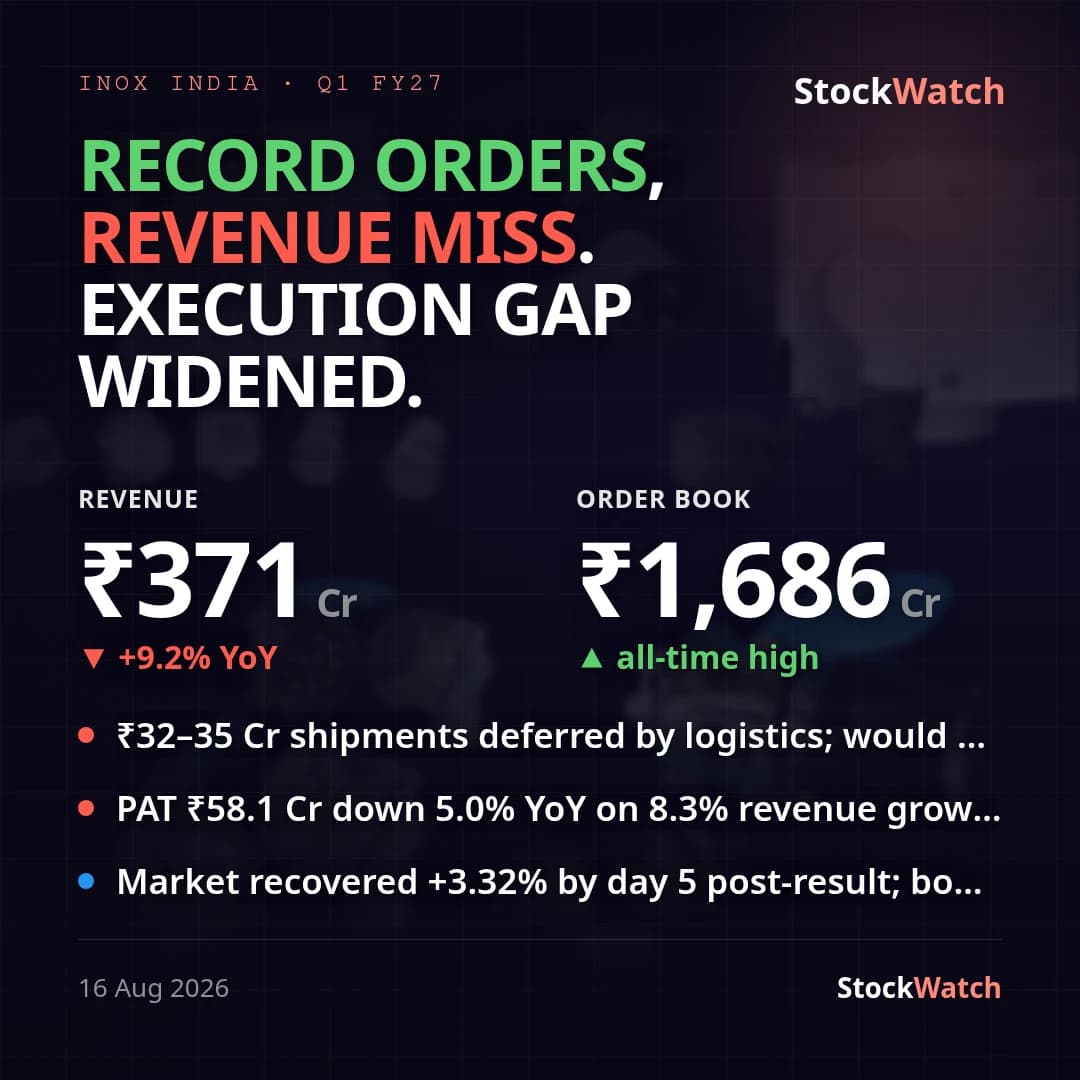
INOX India's consolidated revenue from operations grew 9.2% YoY to ₹370.8 Cr (total income ₹381.6 Cr, +8.3% YoY on the company's own basis), but consolidated PAT fell 5.0% YoY to ₹58.07 Cr from ₹61.12 Cr, with basic EPS down to ₹6.40 from ₹6.73. Notably, the company's press release states PAT of ₹61 Cr (flat YoY) and EBITDA of ₹90 Cr (23.5% margin) — both diverge materially from the SEBI-format reviewed financial statement, which computes PAT of ₹58.07 Cr (PBT ₹75.59 Cr less tax ₹17.51 Cr, exactly) and EBITDA of roughly ₹86.7 Cr; the statement figure is corroborated by the EPS decline and is used here as authoritative. Sequentially, revenue fell 19.5% QoQ and PAT fell 22.8% QoQ off a seasonally strong Q4.
Margins compressed on both counts: net profit margin eased to 15.2% from 17.35% a year ago (15.83% last quarter), and operating margin (EBITDA/revenue) eased to roughly 20.5% from 22.4% YoY. Employee benefits expense rose 24.7% YoY to ₹42.2 Cr, other expenses rose 14.5% to ₹108.6 Cr, finance costs more than doubled (+120%) to ₹1.59 Cr, and depreciation rose 25.5% to ₹9.50 Cr — all outpacing the 9.2% revenue growth, while cost of materials grew a modest 4.3%. The finance-cost and depreciation jumps are consistent with the capacity build-out (new Kandla facility) flagged on the prior concall.
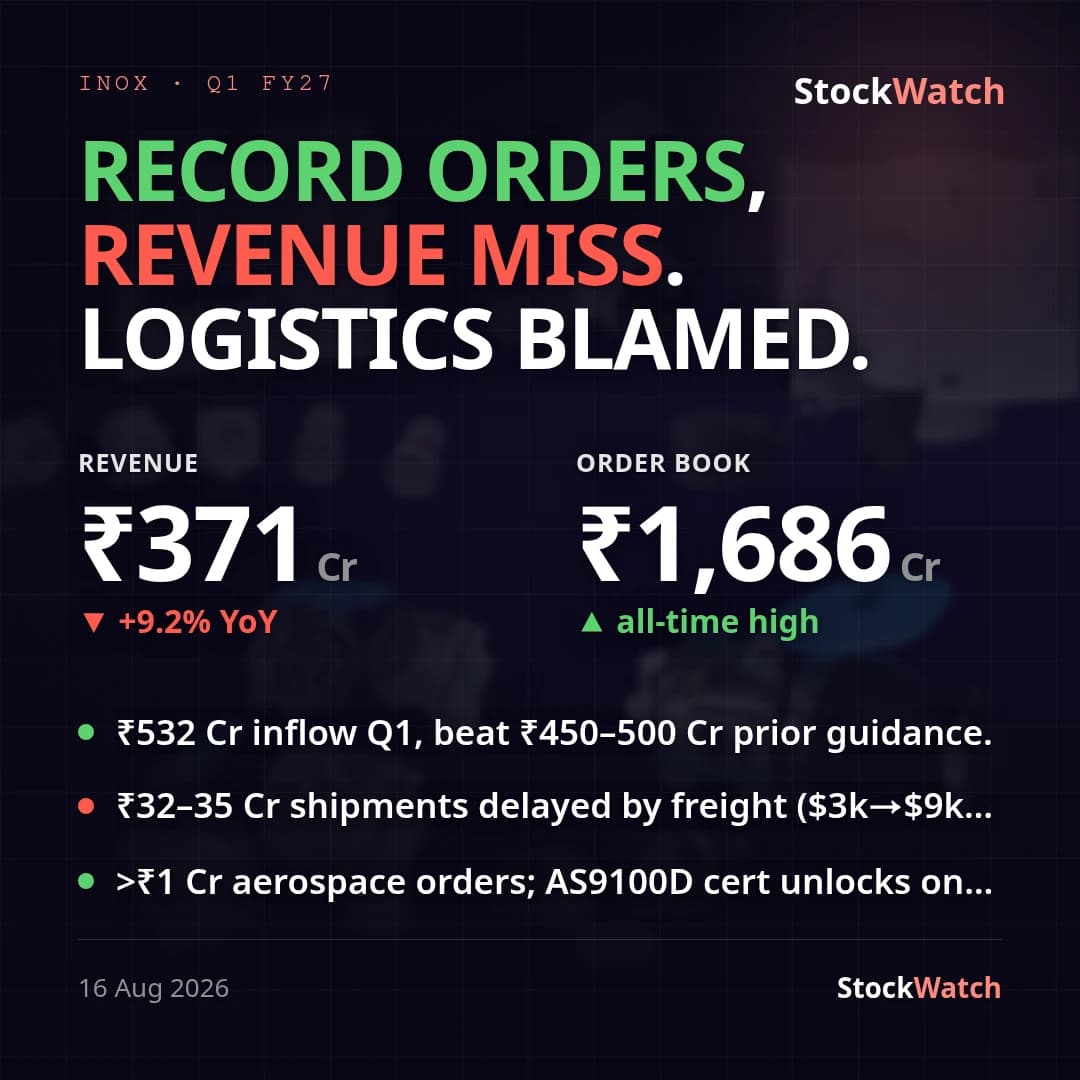
Management's FY27 guidance from the Q4 FY26 call called for 18-20% revenue growth and EBITDA margins in the 21-24% range; Q1's 9.2% YoY growth runs well below that pace, though order-to-revenue conversion in this business is lumpy so one quarter isn't decisive. A Univest trailing-growth preview (not a formal analyst consensus) had pencilled in ₹407-468 Cr revenue and ₹62-79 Cr PAT for the quarter; the actual print came in below both ranges. On the positive side, order inflow hit a record ₹532 Cr — the company's highest ever for a quarter — lifting the order book to ₹1,686 Cr, with the export order book alone above ₹1,140 Cr; exports were 58% of revenue at ₹222 Cr. New wins spanned aerospace (CERN, ITER, additional space-exploration tanks), a first entry into semiconductor infrastructure (Dholera), and LNG fuelling stations, alongside first deliveries to the Bahamas mini-LNG terminal project.
CEO Deepak Acharya framed the quarter around the record order book and new growth platforms (AS9100D aerospace certification, the WAYOUT water micro-factory partnership, a semiconductor skill-development tie-up) — consistent with the strong order intake, though this framing does not reconcile with the PAT figure the company itself quoted. The ₹1,686 Cr order book (about 4.4x this quarter's revenue) supports revenue visibility ahead, but the margin compression from rising employee, finance and depreciation costs is the item to watch next quarter, alongside whether revenue growth accelerates toward the guided 18-20% band as orders convert to billings.