StockWatch
·

IPCA LABORATORIES LTD.

BSE: 524494

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27·vs Q2 FY26
Revenue
2.3K
+6.5%+16.5%
Expenditure
1.7K
+7.4%+12.8%
Net Profit
387.29
+3.8%+27.1%
OPM %
26.47%
-0.79pp+2.40pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
-345.80379.471.1K1.8K2.6KQ2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

Revenue on Track, But Margins Compressed—Pricing Power Gets Tested

margin compression · pricing power · freight headwinds

Result verdictFollow-upQ2 FY2706 Nov 20266 minPharma & Healthcare

14% revenue growth on track; PAT down QoQ amid cost pressures

domestic formulation 14% · export 32% · generics 36%

TranscriptDeep diveQ2 FY2706 Nov 20266 minPharma & Healthcare

Margin Expansion & Guidance Reset — Can Q2 Sustain Q1's Momentum?

pharma · IPCA · guidance

Result previewQ2 FY2702 Nov 20263 minPharma & Healthcare
Latest
Quarterly Result5 Nov, 1:46 pm

IPCA Q2 FY27: Consolidated PAT +33% YoY to ₹375 Cr (~17% adjusted), revenue +14%

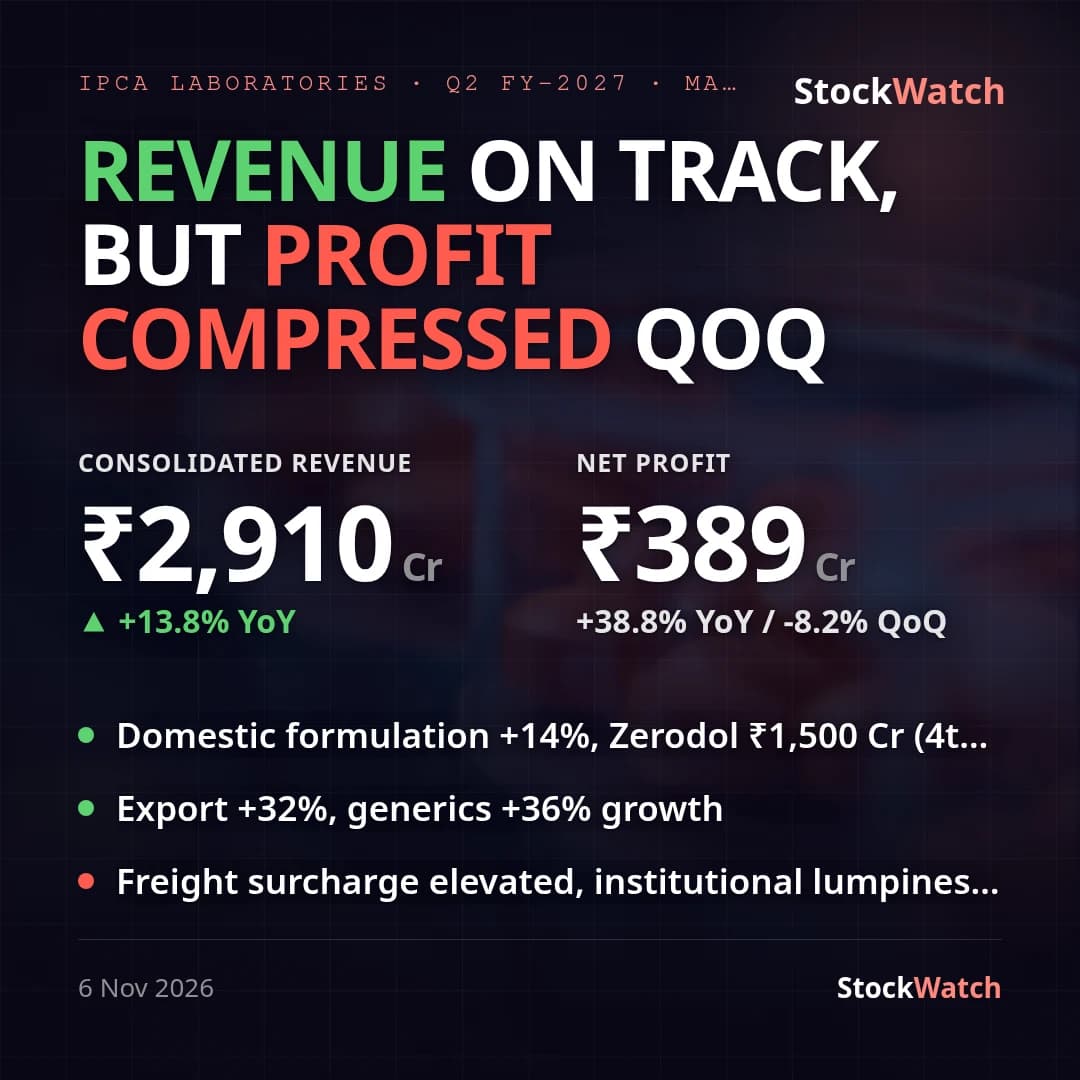
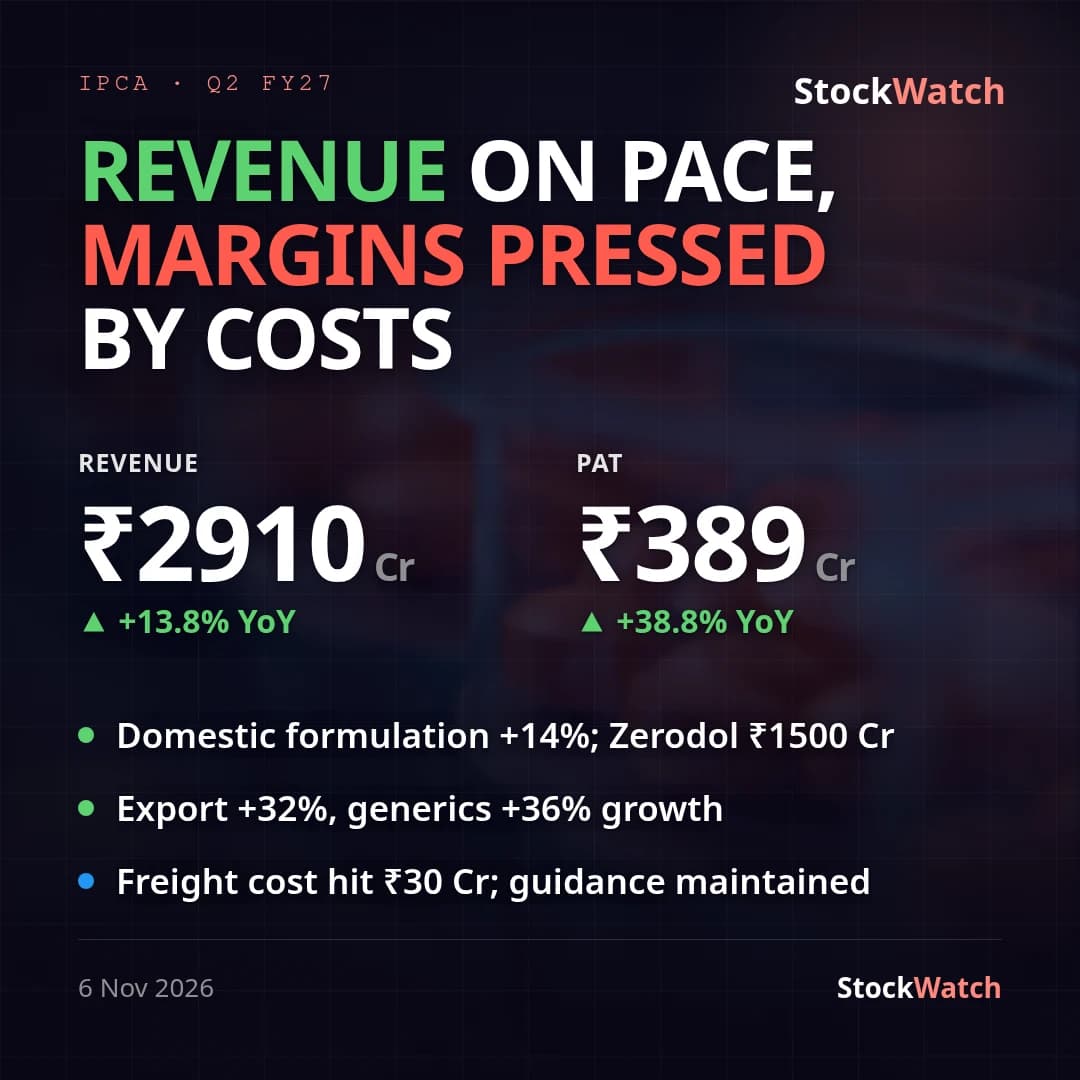
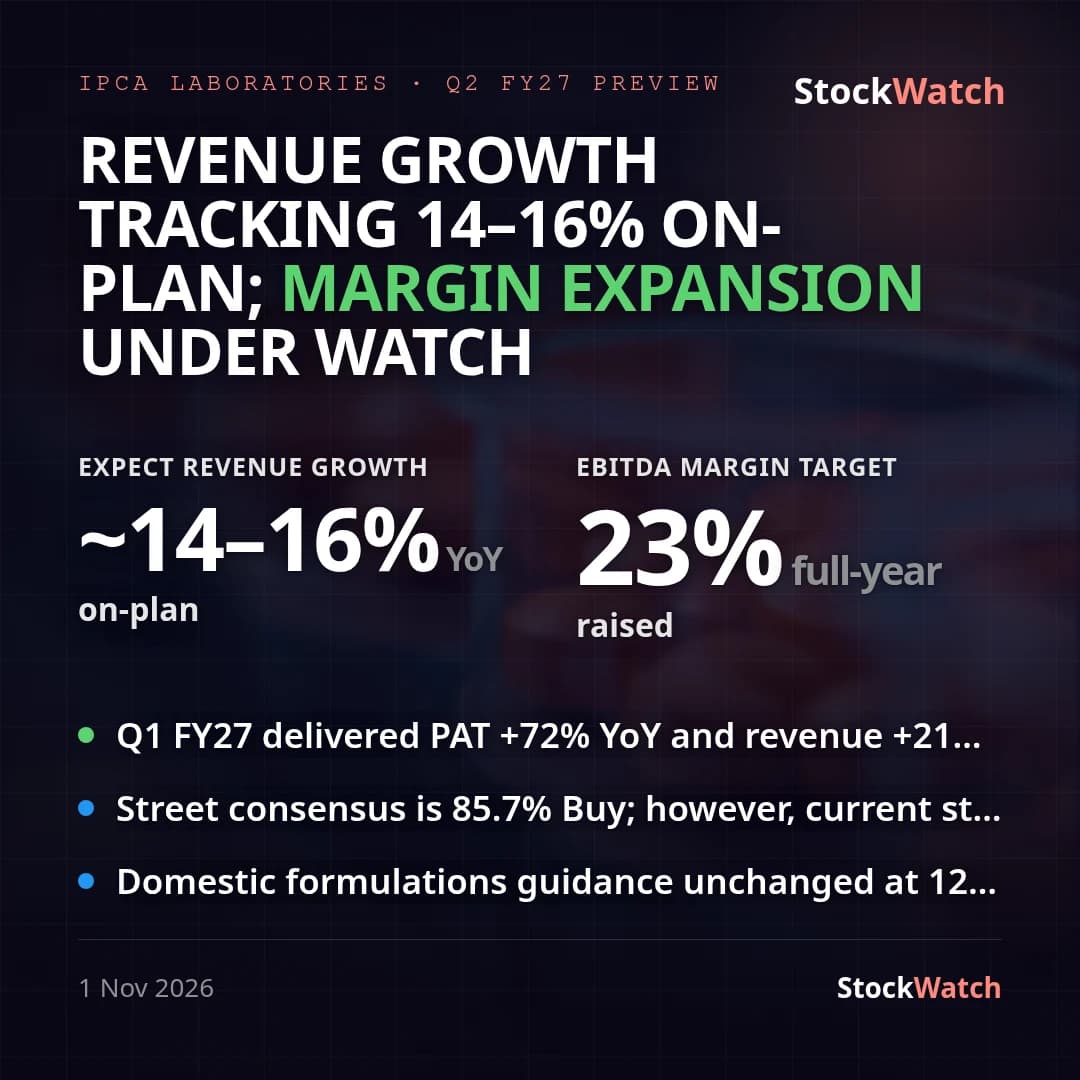
Ipca Laboratories' consolidated PAT (owners) came in at ₹375.13 Cr for Q2 FY27, up 32.8% YoY from ₹282.57 Cr, on consolidated revenue of ₹2,909.94 Cr, up 13.8% YoY (+4.4% QoQ). Standalone revenue grew faster YoY (16.9%) than consolidated, while standalone PAT grew slower (27.1% vs 32.8%) — a >3-point divergence in both directions that reflects the subsidiary mix (Unichem/exports) rather than any inconsistency in the underlying print; both bases point the same direction. This is the primary, consolidated-basis read. The reported 32.8% YoY PAT jump is flattered by one-off items on both sides of the comparison: this quarter carries a ₹24.26 Cr exceptional 'Provision for Claims' (Perindopril UK litigation at Niche Generics, a Unichem step-down subsidiary), while the year-ago quarter absorbed a larger ₹58.26 Cr European Commission interest-settlement charge on the same Unichem/Niche litigation. Stripping both out (pre-tax, since the filing doesn't separately disclose tax effects on exceptional items) gives adjusted PAT growth of roughly 17% YoY — still healthy but well below the headline. Margins expanded YoY on both measures: NPM (PAT/total income) rose to 12.8% from 10.9%, and EBITDA margin (PBT excl. exceptional + finance cost + D&A, over revenue) rose to ~24.0% from ~22.4%. Sequentially, PAT fell 6.7% from ₹401.89 Cr in Q1 FY27 and OPM eased from ~24.9%, with the Q2 claims provision the main driver of that dip rather than any operating deterioration — revenue still rose 4.4% QoQ. No reliable Street consensus for this specific quarter's PAT/EBITDA could be sourced via web search, so vsStreet is marked unknown rather than guessed. Against the company's own guidance from the Q1 FY27 call — FY27 revenue growth raised to 14-16% and EBITDA margin raised to ~23% — the half-year run-rate is tracking ahead: H1 FY27 consolidated revenue is up 17.1% YoY and H1 OPM works out to ~24.5%, both above the raised bars, so the quarter reads as a guidance beat rather than merely on-track. This is consistent with the bullish, confident tone management struck on the August 2026 call. The quarter's other disclosed developments — board approval on November 5, the pending Krebs Biochemicals amalgamation (no P&L effect yet, pending approvals), and the routine insider-trading window closure ahead of results — are procedural and don't move the numbers. No management press release text was available in this filing bundle to cross-check against management's own framing of the quarter. Going into Q3, the two swing factors are whether the Niche/Unichem claims provision proves final or needs topping up, and whether H2 margins hold near the 23%+ guided level after this quarter's sequential easing.

5 Nov 2026, 01:46 pm

Quarterly Result13 Aug, 1:34 pm

IPCA Q1 FY27: consolidated PAT +72% YoY to ₹402 Cr as margins expand, revenue +21%

Ipca's Q1 FY27 print is unambiguously strong on a year-on-year basis: consolidated PAT of ₹401.89 Cr rose 72% YoY (the company's own release cites 80% using a pre-minority-interest base of ₹422.81 Cr), on consolidated revenue of ₹2,788.10 Cr, up 21% YoY and 16.7% QoQ. Standalone PAT was ₹373.29 Cr, up 42% YoY, on revenue of ₹2,119.24 Cr, also up 21%. Neither period carries an exceptional item this quarter, making it a clean read against Q4 FY26, which had absorbed a ₹45.82 Cr (consolidated) labour-code exceptional charge. The margin story is the real driver: consolidated EBITDA margin (before forex and other income) expanded to 22.88% from 18.39% a year ago, and standalone margin to 26.27% from 23.82%. Consolidated total expenses grew only ~11.5% (₹2,241.28 Cr vs ₹2,011.00 Cr) against 21% revenue growth — clear operating leverage, not a forex artifact, since the EBITDA metric already excludes forex (which itself swung favorable: a ₹31.57 Cr consolidated gain versus an ₹8.16 Cr loss a year ago). Mix also helped: institutional export formulations jumped 107% YoY to ₹119.75 Cr, generics exports rose 27% to ₹340.02 Cr and API exports grew 33% to ₹332.35 Cr — export income overall (+34% standalone) comfortably outpaced domestic formulations (+13%). No independent analyst consensus for this print turned up in a web search, so the reading is against our own pre-result preview, which flagged expected revenue of ~₹1,850–1,900 Cr, an EBITDA margin watch of 21–23%, and organic growth of 10%+ as the bar — the actual print clears all three (standalone revenue ₹2,119 Cr, consolidated EBITDA margin 22.9%, revenue growth 21% YoY). Against management's own FY27 guidance from the June 4, 2026 concall — consolidated revenue growth of 12–13% and EBITDA margin improving to 22–22.3% from 20.7% — Q1 is already running ahead of pace on both counts, with margin printing at the top of the full-year target in the very first quarter. Domestic branded formulations grew 13%, roughly matching the guided ~12%. The Krebs Biochemicals amalgamation, board-approved June 26, 2026 with an April 1, 2026 appointed date, remains pending consents and is not yet reflected in these numbers. The ₹6/share dividend (record date August 7) and today's AGM are procedural, not P&L-relevant. With both growth and margin ahead of the full-year guide after just one quarter, the bar for the rest of FY27 rises. What it sets up: whether the 22.9% consolidated EBITDA margin holds once Krebs is consolidated and once Unichem's separately-guided 12–13% margin target (not broken out this quarter) shows up in the numbers.

13 Aug 2026, 01:34 pm

Corporate Events

Board MeetingIPCALAB
2026
5Nov

Board Meeting

The meeting of the Board of Directors will be held to consid…

BSE Filing ↗
Board MeetingIPCALAB
2026
30Sep

Board Meeting

The Board of Directors met to take on record the Standalone …

BSE Filing ↗
Board MeetingIPCALAB
2026
13Aug

Board Meeting

The 76th Annual General Meeting (AGM) of the Company will be…

BSE Filing ↗
DividendIPCALAB
2026
7Aug

₹6 / share

BSE Filing ↗
DividendIPCALAB
2025
5Aug

₹2 / share

BSE Filing ↗
DividendIPCALAB
2024
27Nov

₹2 / share

BSE Filing ↗
Board MeetingIPCALAB
2024
14Nov

Board Meeting

consider and approve Standalone and Consolidated Financial R…

BSE Filing ↗
Board MeetingIPCALAB
2024
30Sep

Board Meeting

Integration and consolidation of the generics formulations b…

BSE Filing ↗
Board MeetingIPCALAB
2024
29May

Board Meeting

Consideration and approval of Standalone and Consolidated Au…

BSE Filing ↗
Board MeetingIPCALAB
2024
14Feb

Board Meeting

Consider and approve Unaudited Standalone and Consolidated F…

BSE Filing ↗
DividendIPCALAB
2023
22Nov

₹2 / share

BSE Filing ↗
Board MeetingIPCALAB
2023
10Nov

Board Meeting

Consideration and approval of Standalone and Consolidated Un…

BSE Filing ↗