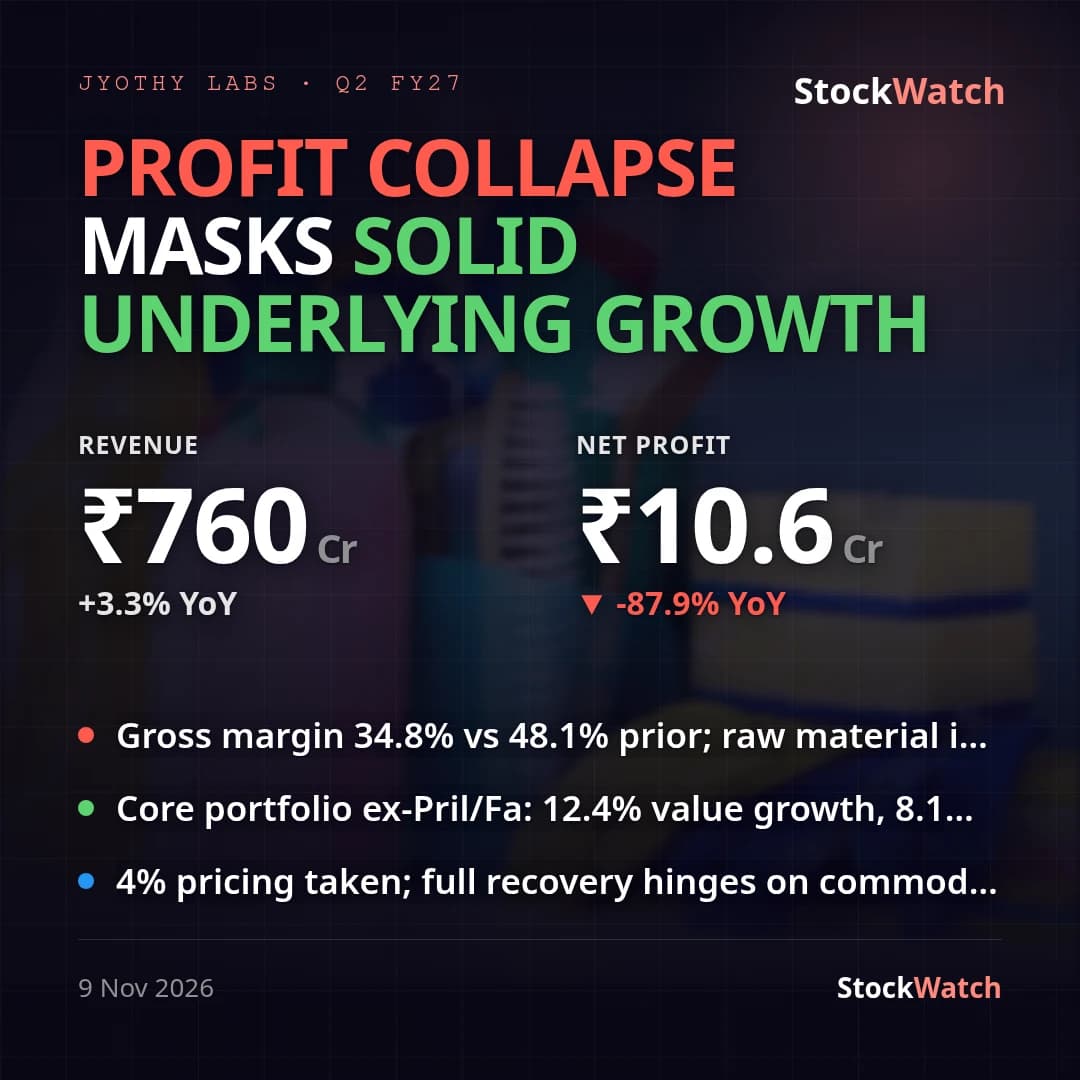
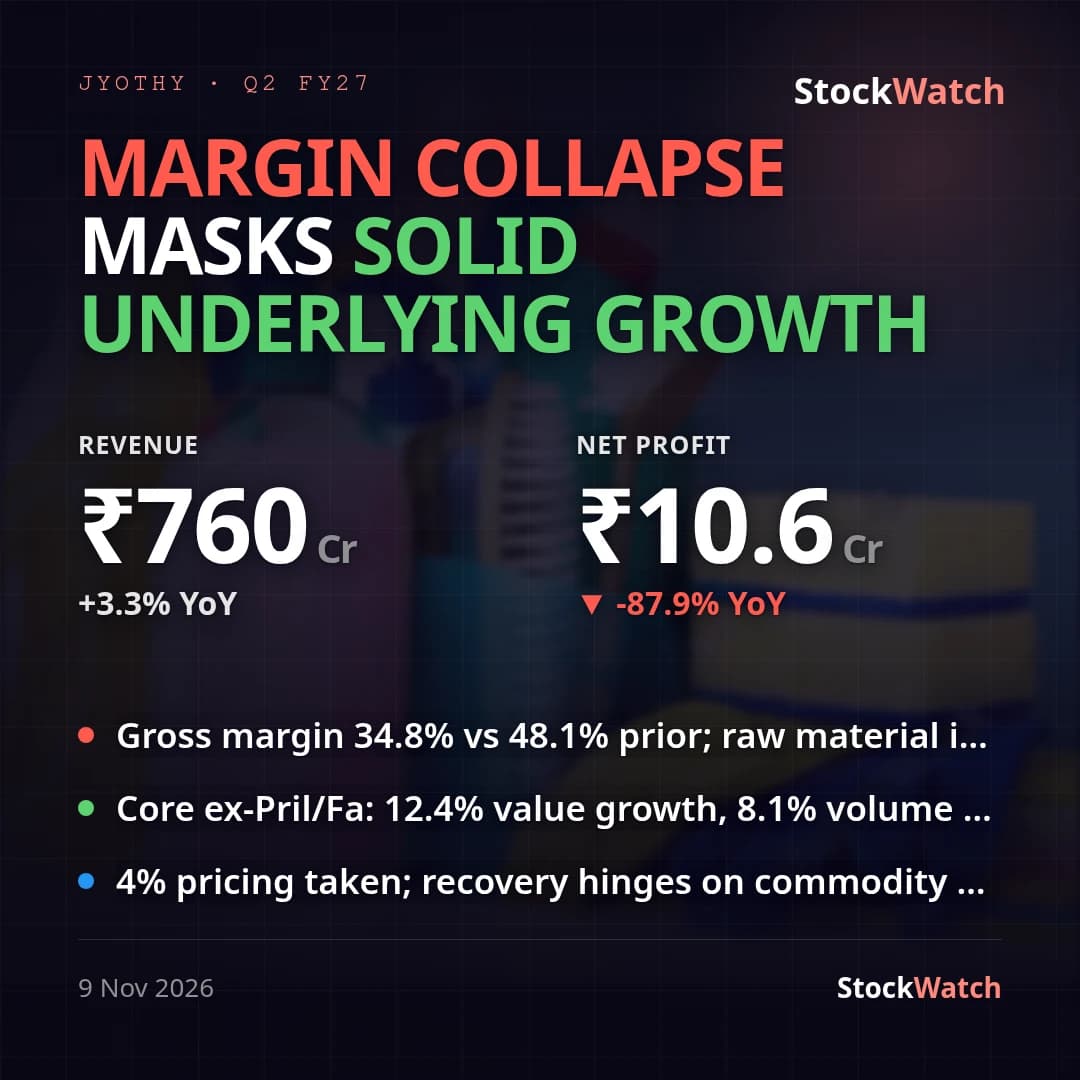
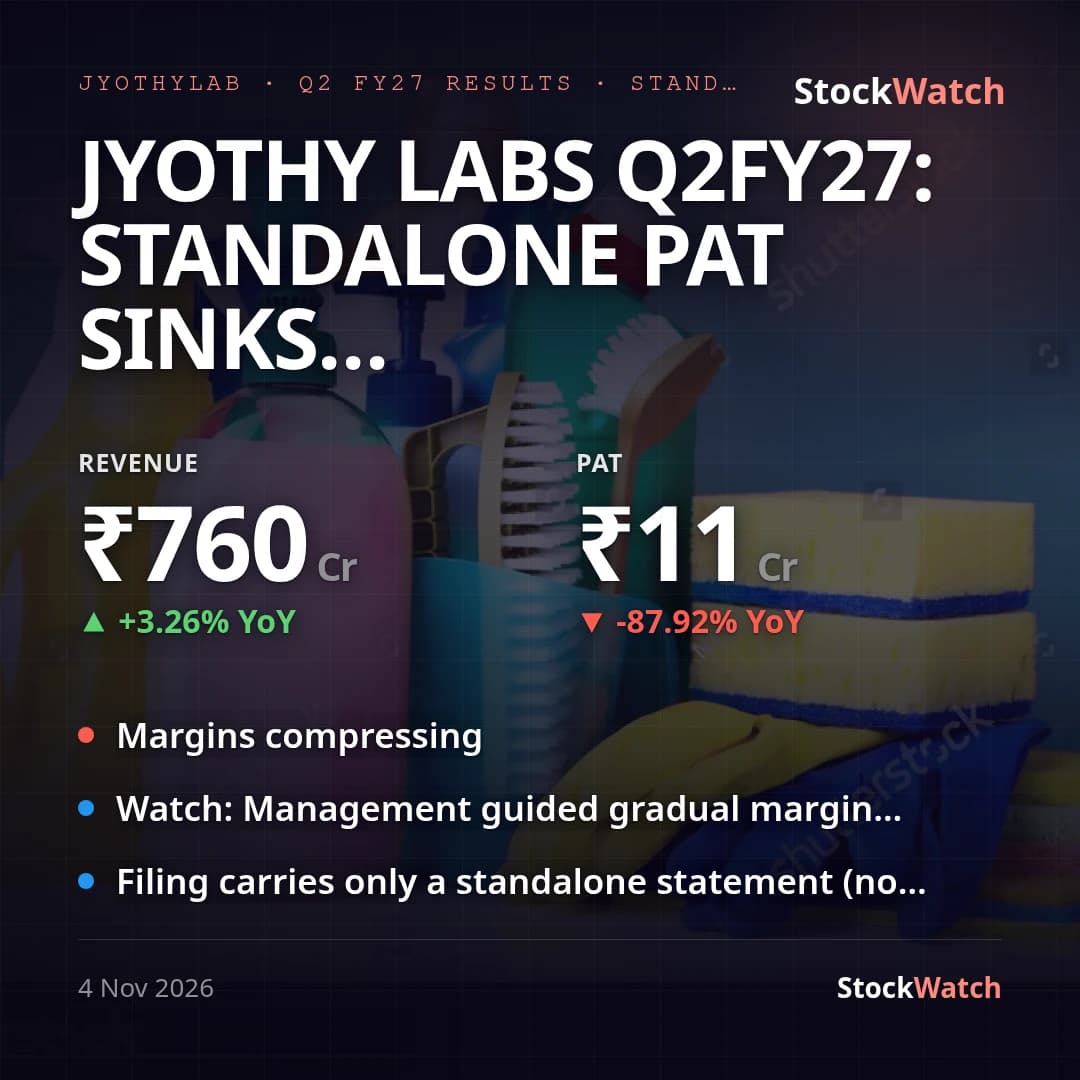
Jyothy Labs Q2FY27: standalone PAT sinks 88% YoY to ₹10.6 Cr as input costs crush margins
Jyothy Labs' standalone PAT for Q2 FY27 (quarter ended September 30, 2026) fell 87.9% YoY to ₹10.60 Cr from ₹87.76 Cr, and 77.7% QoQ from ₹47.64 Cr, even though revenue from operations grew 3.3% YoY to ₹760.04 Cr (down 1.7% QoQ from ₹773.40 Cr). EPS fell to ₹0.29 from ₹2.39 a year ago and ₹1.30 last quarter. NPM (PAT/total income) collapsed to 1.37% from 11.65% YoY and 6.02% QoQ; OPM (PBT+finance cost/total income) fell to 2.28% from 16.07% YoY and 8.36% QoQ. No consolidated statement is filed, so these standalone figures are the primary — and only — basis for this result.
The squeeze sits almost entirely on cost of materials consumed, which rose to 59.8% of revenue (₹454.75 Cr) from 52.1% a year ago (₹383.78 Cr) — an 18.5% YoY jump in raw-material cost against 3.3% revenue growth. A finished-goods inventory swing added further pressure: the inventory line moved from a ₹29.50 Cr cost credit a year ago to a ₹11.62 Cr charge this quarter, a ₹41 Cr adverse swing. By segment, Home Care (dishwash, mosquito repellents, aerosols) swung to a ₹12.83 Cr segment loss from a ₹39.48 Cr profit a year ago on revenue down 7.1% YoY to ₹282.38 Cr. Fabric Care, the largest segment, grew revenue 10.4% YoY to ₹386.58 Cr but segment PBT fell 67.1% YoY to ₹23.88 Cr. Personal Care was the lone bright spot, PBT up 152% YoY to ₹5.56 Cr on 11.2% revenue growth. Advertisement and sales-promotion spend was cut 8.1% YoY to ₹56.52 Cr, a lever management appears to have pulled to partially offset the cost hit.
Management's prior (Q1 FY27) concall guidance flagged exactly this: EBITDA margins under pressure through H1, with "no immediate relief anticipated in Q2" as high-cost inventory works through the system, and recovery only expected from October. On that narrow point the quarter is consistent with what was flagged. But the broader FY27 guidance of double-digit revenue growth (ex-Pril and franchise) is tracking well short — H1 FY27 cumulative revenue grew just 3.1% YoY (₹1,533.44 Cr) and H1 PAT fell 68.4% YoY (₹58.24 Cr), meaning H2 would need to accelerate sharply to reach a double-digit full-year number. A web search found no specific analyst consensus or brokerage preview published ahead of this Q2 FY27 print, so the result cannot be benchmarked against street estimates; CARE Ratings reaffirmed the company's AA/Stable long-term facility rating on September 25, 2026, and the company separately recognised a ₹6.63 Cr insurance claim for the Patiala warehouse fire in late September — both minor relative to the scale of the margin miss. No company press release accompanied this filing beyond the regulatory results, so there is no management framing to reconcile against the numbers.
The same board meeting approved a ₹147 Cr tender-offer buyback of up to 68.37 lakh shares (1.86% of paid-up equity) at ₹215/share, with the promoter group confirming it will not participate and November 11, 2026 set as the record date. The buyback follows four consecutive quarters of YoY profit decline and sits alongside management's own guidance that margin relief is a Q3/Q4 story, not a Q2 one — the next print is the test of whether that recovery materialises.