StockWatch
·

KAMAT HOTELS (INDIA) LTD.

BSE: 526668

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27·vs Q2 FY26
Revenue
60.63
-7.9%+5.1%
Expenditure
51.08
-1.2%-7.2%
Net Profit
7.11
-33.1%+84.7%
OPM %
21.20%
-4.78pp+10.94pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.0025.6051.2076.81102.41Q2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

Turnaround real, but margin claims overstated; expansion unproven

profitability turnaround · margin expansion · 400-key expansion

TranscriptDeep diveQ2 FY2706 Nov 20266 minConsumer & Retail

Kamat Hotels turns to ₹5.45 Cr consol. PAT YoY; margins expand, Q2 softens QoQ as guided

hospitality · yoy turnaround · margin expansion

ResultsQ2 FY2703 Nov 20263 minConsumer & Retail

Solid YoY growth masks Q1 seasonal dip; expansion pipeline uncertain

domestic travel · margin expansion · property pipeline

TranscriptDeep diveQ1 FY2714 Aug 20266 minConsumer & Retail
Latest
Board Meeting3 Nov, 3:04 pm

Kamat Hotels turns to ₹5.45 Cr consol. PAT YoY; margins expand, Q2 softens QoQ as guided

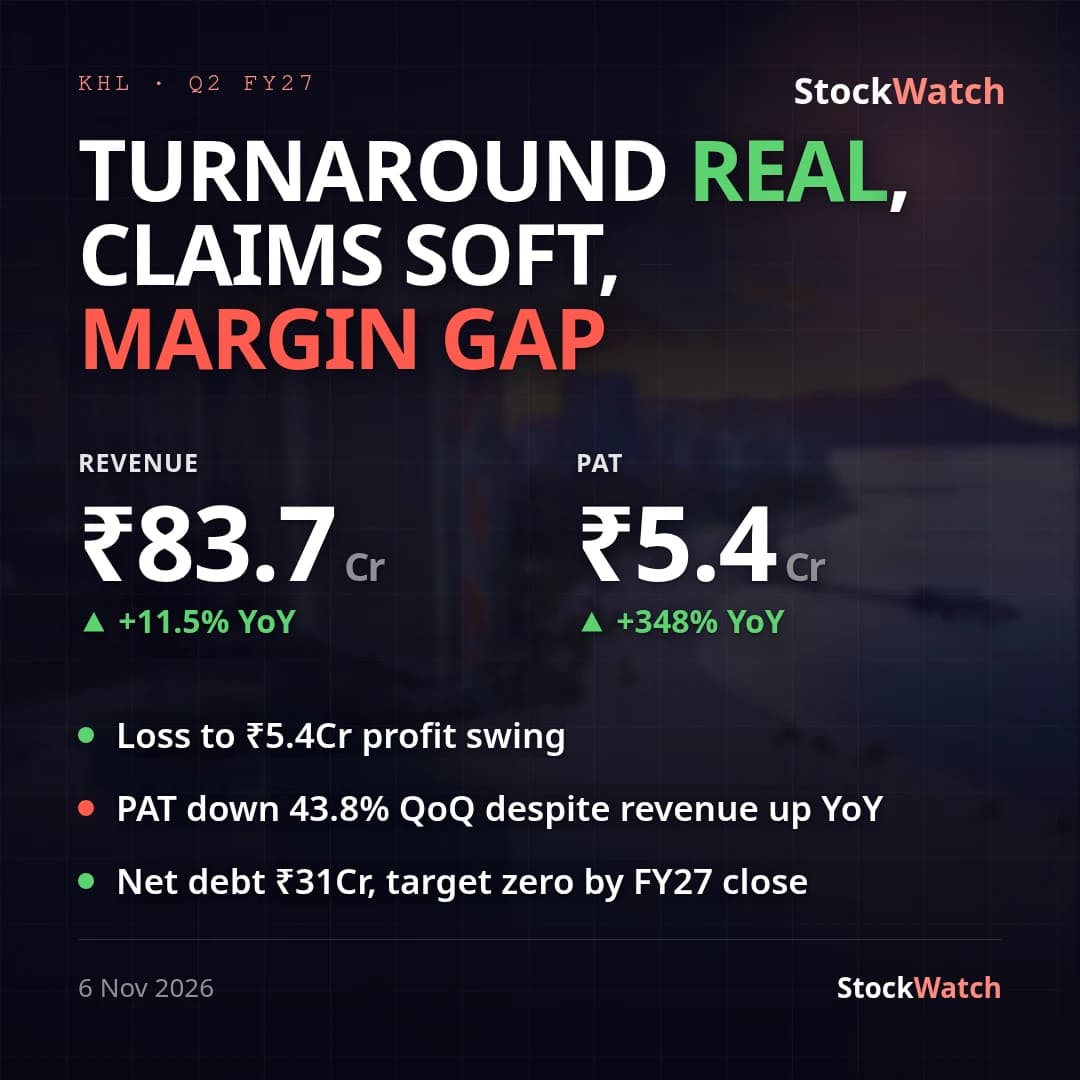
Kamat Hotels' consolidated profit swung to ₹5.45 Cr for the quarter ended September 2026, against a ₹2.19 Cr loss in the year-ago quarter, as revenue from operations grew 11.5% YoY to ₹83.73 Cr. The year-ago quarter also carried a ₹2.5 Cr exceptional gain that is absent this quarter; stripping that out, the comparable year-ago loss deepens to roughly ₹4.69 Cr, making the swing to this quarter's clean ₹5.45 Cr profit a sharper turnaround than the reported numbers alone suggest. Standalone PAT was ₹7.11 Cr (EPS ₹2.41) against consolidated PAT of ₹5.45 Cr (EPS ₹1.59, after ₹0.77 Cr attributable to non-controlling interests in subsidiaries including Orchid Hotels Pune and Fort Jadhavgadh). Margins expanded sharply on a YoY basis — operating margin rose to 23.8% from 13.8%, and net margin to 6.3% from -2.9% — but eased from Q1 FY27's 27.2% OPM / 10.4% NPM, with revenue down 7.5% and PAT down 43.8% sequentially. This QoQ softening is consistent with management's own seasonal call on the Q1 FY27 concall that Q1 and Q2 would be soft before an H2 recovery; on that basis the quarter tracks guidance rather than missing it, even though no formal revenue or EBITDA number was ever given. Operating margin at 23.8% also remains roughly 6 points short of management's 2-3 year target of 30% EBITDA margins. No broker previews or consensus estimates for this specific quarter turned up in a search, consistent with thin formal analyst coverage of the stock; vs-street is accordingly unknown rather than a miss. The quarter's standout corporate action was the board's approval, at the same meeting, of up to ₹168 Cr of investment via OCDs/NCDs into wholly-owned subsidiary Orchid Hotels Pune — funding that ties directly to the ~400-key expansion across Gwalior, Dwarka, Dehradun, Nashik, Rishikesh and Mandvi flagged on the prior call. The board also granted 1,78,000 RSUs under a new FY26 ESOP scheme, a minor item with no P&L impact this quarter. No standalone management press release was available to cross-check against the filing. The quarter sets up a test of the H2 recovery call: FY26's full-year consolidated PAT ran at ₹38.55 Cr, so the next two quarters need to outrun this soft Q2 materially to keep that pace intact, with the ₹168 Cr Orchid Hotels Pune capex now a near-term funding commitment to track alongside it.

3 Nov 2026, 03:04 pm

Board Meeting11 Aug, 2:36 pm

Kamat Hotels: consolidated PAT more than doubles YoY to ₹9.69 Cr as margins expand

Kamat Hotels' consolidated revenue rose 9.6% YoY to ₹90.54 Cr in Q1 FY27 (Q1 FY26: ₹82.65 Cr), with consolidated PAT of ₹9.69 Cr (owners' share ₹9.40 Cr, EPS ₹3.19) versus ₹4.28 Cr a year ago — a headline gain of roughly 127% YoY. Standalone PAT was actually higher, at ₹10.63 Cr (EPS ₹3.50), pointing to a drag from subsidiary-level performance/minority interests at the group level. No brokerage preview or consensus estimate for this print turned up in a search, so there is no street beat/miss to call here (vsStreet: unknown); a separate management press release was not available to cross-check tone beyond the exchange filing itself. The YoY jump was margin-led rather than purely volume-led: net margin (PAT/total income) expanded to about 10.4% from 5.1%, and operating margin improved to roughly 27.2% from about 22.4%, as employee costs and other opex grew slower than revenue while finance cost stayed roughly flat (₹5.86 Cr vs ₹6.05 Cr). Both quarters were largely clean of one-offs — this quarter had none, versus a modest ₹0.41 Cr net exceptional gain in Q1 FY26 — so the ~127% reported PAT growth is essentially adjusted-clean, if anything mildly understated versus a fully comparable base. On guidance, management's FY26 Q4 concall had flagged a cautious FY27 topline outlook — an expected ~₹50 Cr full-year revenue hit from discontinuing the IRA Mumbai lease, offset by EBITDA gains as FY26's newer hotels mature — and management has separately spoken of a ₹500 Cr FY27 revenue ambition with EBITDA margins held in a 29-30% band. This quarter doesn't yet show the IRA Mumbai drag (revenue is still up YoY), but at ₹90.54 Cr it is only about 18% of the ₹500 Cr full-year mark and OPM of ~27.2% trails the guided 29-30% band, so this is best read as too early to call rather than on-track or off-track. Sequentially, revenue fell 17.8% and PAT fell 44.5% versus the Jan-Mar quarter (₹110.12 Cr revenue, ₹17.46 Cr PAT, NPM ~14.7%) — a seasonal unwind from the wedding/MICE-heavy Q4 rather than a deterioration. The quarter included two asset-light moves consistent with the stated 150-200 key FY27 expansion plan: IRA by Orchid opened in Bhavnagar (June 19) and a second luxury Orchid property was signed in Dwarka (May 14). The board also approved a new ESOP scheme (up to 8.845 lakh options) and confirmed Milind Wadekar as CFO effective August 1, 2026, alongside the results. Auditors carried forward going-concern-related emphasis of matter for subsidiaries OHPPL and MPPL and the ongoing ₹5 Cr ED/PMLA deposit matter, both unchanged from prior quarters. Watch items going forward are whether the IRA Mumbai exit shows up in H2 revenue, whether OPM converges toward the 29-30% band as newer properties ramp, and delivery on the Dwarka/Bhavnagar-style asset-light additions.

11 Aug 2026, 02:36 pm

Corporate Events

Board MeetingKAMATHOTEL
2026
3Nov

Board Meeting

The meeting of the Board of Directors is scheduled to consid…

BSE Filing ↗
Board MeetingKAMATHOTEL
2026
26Sep

Board Meeting

The Annual General Meeting will be held to receive, consider…

BSE Filing ↗
Board MeetingKAMATHOTEL
2026
11Aug

Board Meeting

A Meeting of the Board of Directors of Kamat Hotels (India) …

BSE Filing ↗
Board MeetingKAMATHOTEL
2024
7May

Board Meeting

Consider and approve the Audited (Standalone and Consolidate…

BSE Filing ↗
Board MeetingKAMATHOTEL
2024
18Mar

Board Meeting

Consideration and approval of modification in the terms of N…

BSE Filing ↗
Board MeetingKAMATHOTEL
2024
31Jan

Board Meeting

Consider and approve Unaudited (Standalone and Consolidated)…

BSE Filing ↗
Board MeetingKAMATHOTEL
2023
21Oct

Board Meeting

consider and approve Unaudited (Standalone and Consolidated)…

BSE Filing ↗
Board MeetingKAMATHOTEL
2023
11Aug

Board Meeting

consider and approve Unaudited (standalone and consolidated)…

BSE Filing ↗