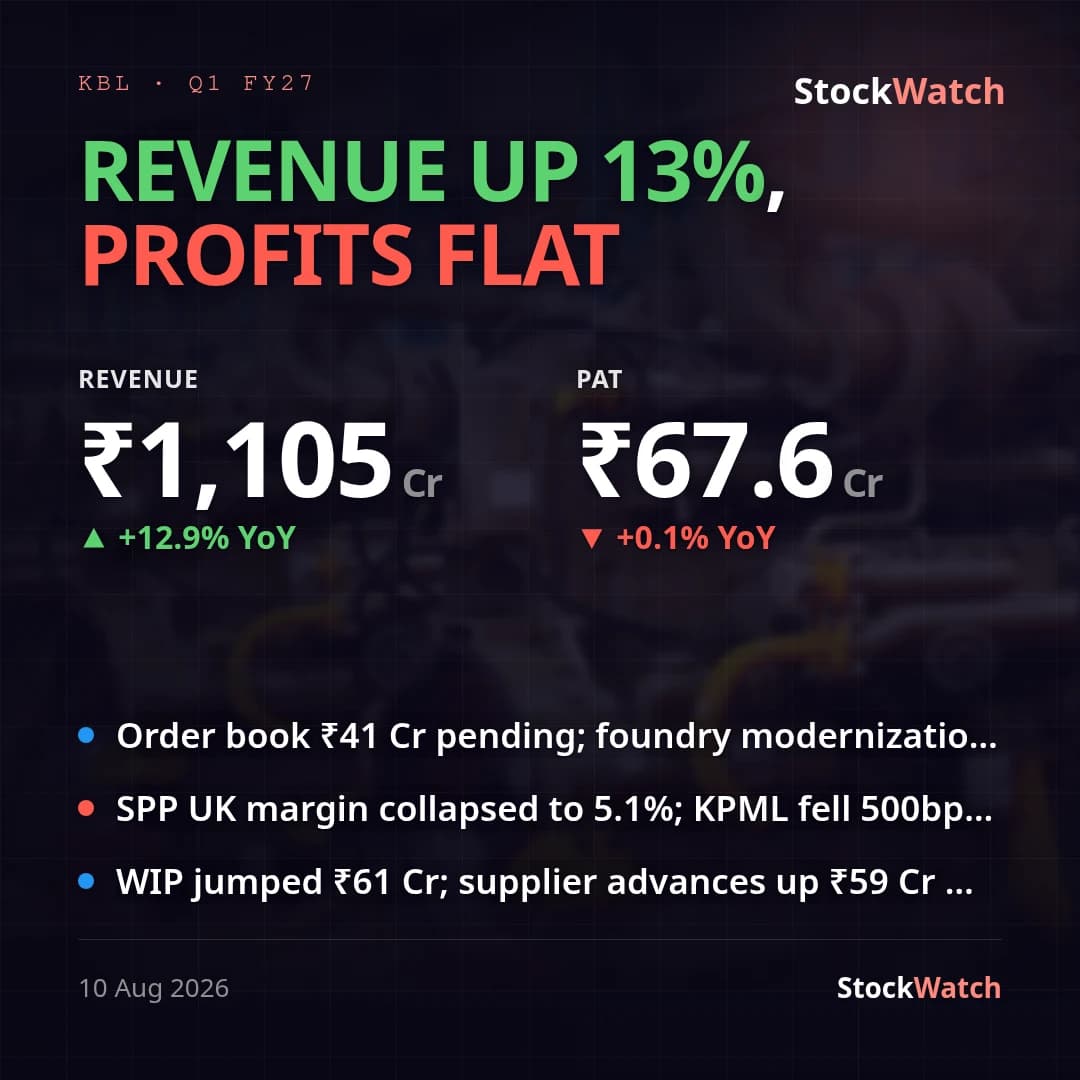
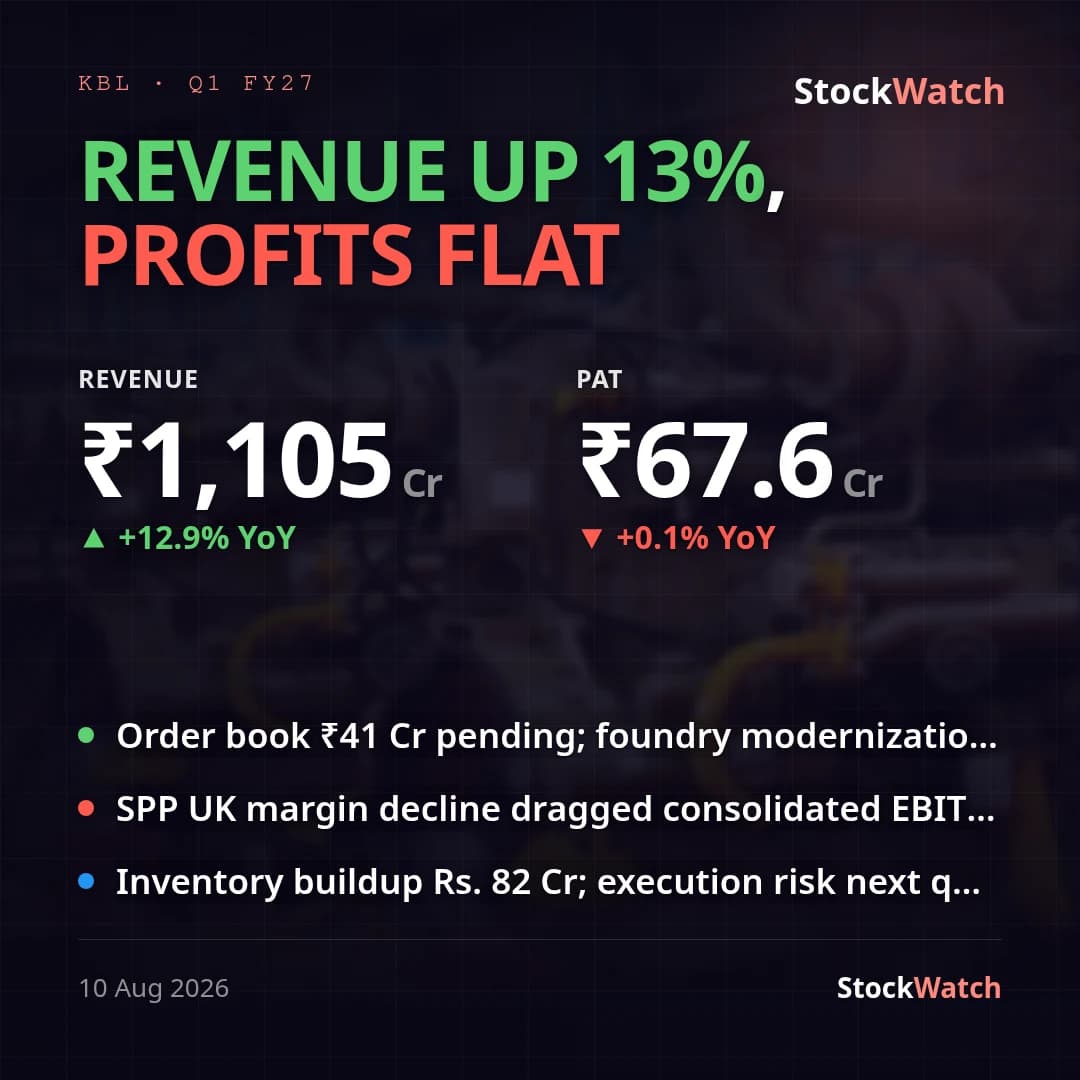
Kirloskar Brothers Q1: PAT flat at ₹67.6 Cr as margins compress despite 13% revenue rise
Kirloskar Brothers delivered its guided return to double-digit topline growth in Q1 FY27 — consolidated revenue rose 12.9% YoY to ₹1,104.9 Cr — but the bottom line failed to follow, with net profit essentially flat at ₹67.6 Cr versus ₹67.5 Cr a year ago (EPS ₹8.39 vs ₹8.40). The 39.7% sequential fall in PAT and 21.9% drop in revenue are largely seasonal, as Q4 is the year-end execution peak for the pump maker; YoY is the cleaner read, and it shows growth delivered on the top line but stalled on the bottom.
The gap sits on margins. Net profit margin compressed to 6.1% from 6.9%, and operating margin eased to ~10.5% from ~11.4%, as cost of materials (+15.3% YoY) and employee expense (+15% YoY) both outran the 12.9% revenue gain. A mix shift toward faster-growing but lower-margin international operations is a factor: overseas revenue jumped 18.5% YoY to ₹422.9 Cr while domestic rose 9.6% to ₹682.0 Cr. The consolidated–standalone divergence is telling — the standalone (domestic parent) grew PAT 14.9% YoY to ₹54.0 Cr on 8.6% revenue growth, a materially better profit trajectory than the flat consolidated line, confirming that the foreign subsidiaries (one posted a ₹5.5 Cr loss in the quarter) diluted group profitability.
The print broadly meets management's May guidance for a return to double-digit growth underpinned by a 30% domestic / 21% international order-book expansion — this quarter's international outperformance is consistent with that book, and concurrent developments support the thrust, with subsidiary SPP Pumps securing a GBP 11.7M order in July. But the promised operational-efficiency gains and international-margin-mix improvement have yet to show in the numbers. There were no exceptional items this quarter (the year-ago quarter carried only a ₹0.3 Cr VRS charge), so the flat YoY profit is clean rather than one-off-distorted. No brokerage consensus is on record for this mid-cap and the company gives no formal margin guidance; the Q1 earnings call is scheduled for August 3, where margin trajectory and order-book conversion will be the key questions into H2.