Knack Packaging Q2 FY27: record revenue +53% YoY, margin squeeze caps PAT at +21%
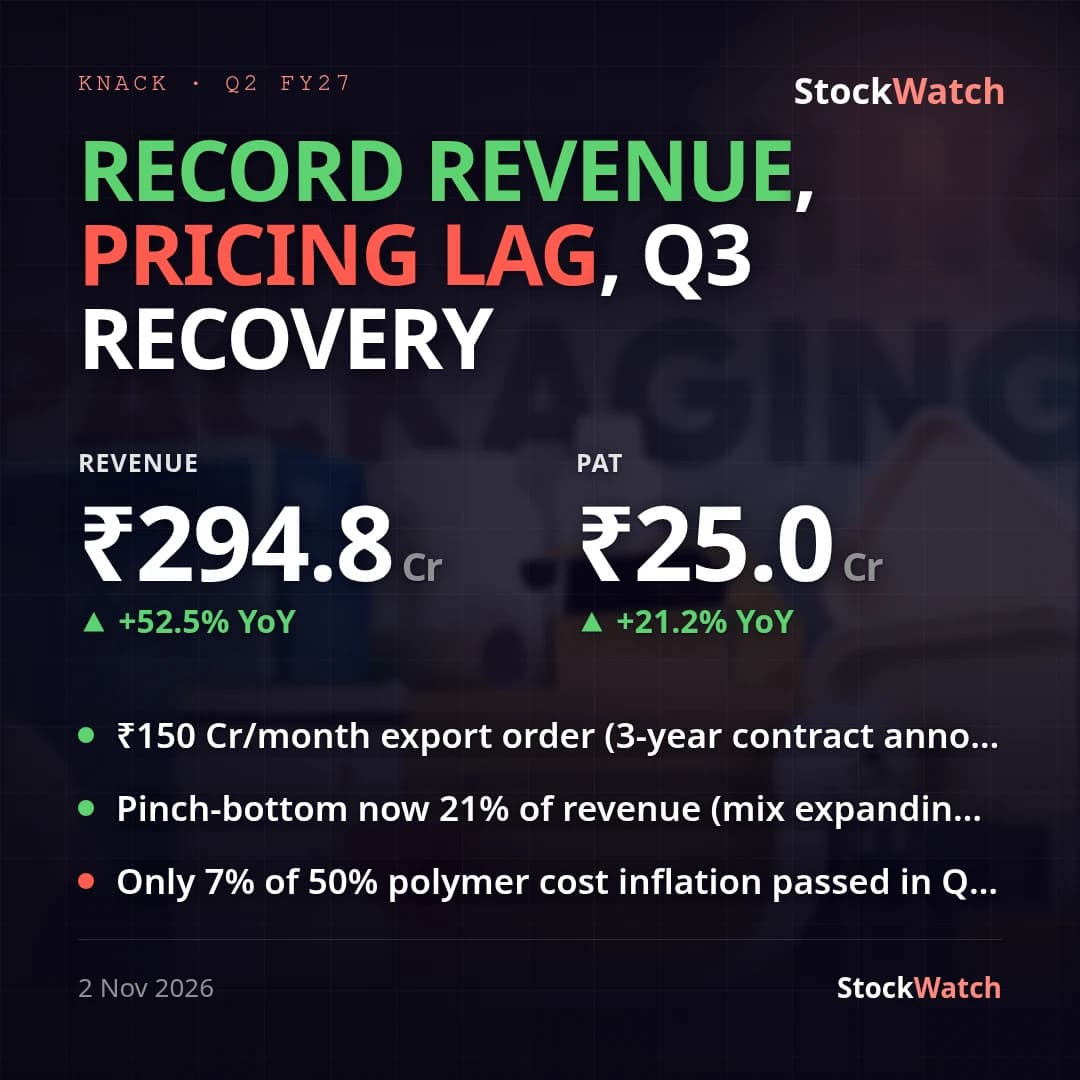
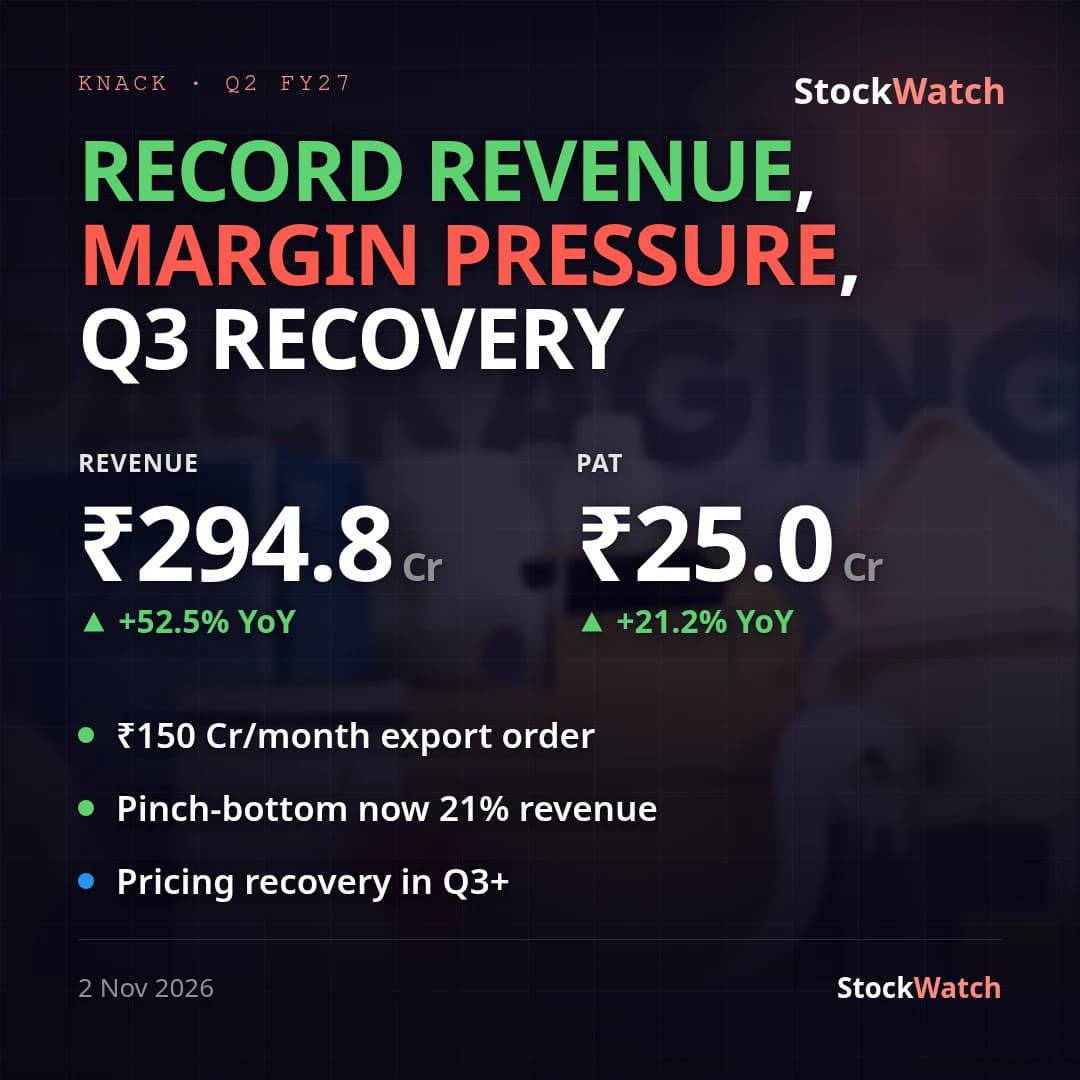
Knack Packaging's consolidated revenue rose 52.5% YoY to ₹294.76 Cr in Q2 FY27 (+12.3% QoQ), its highest-ever quarterly revenue and a continuation of the post-IPO growth seen in Q1 FY27 (+41% YoY). But profitability trailed the topline: consolidated PAT grew a slower 21.2% YoY to ₹25.02 Cr, and actually fell 18.0% QoQ from ₹30.53 Cr in Q1 FY27, with basic EPS easing to ₹2.07 from ₹3.05 last quarter. Standalone PAT, at ₹25.84 Cr on a PBT of ₹33.30 Cr, ran marginally ahead of consolidated, as the Mexico joint venture (Sayem Knack S.A. de C.V.) added a ₹2.62 Cr net loss this quarter (₹6.06 Cr for H1 FY27) with no offsetting revenue since the JV is still in scale-up. No exceptional items were booked in the quarter on either statement.
The gap between revenue and profit growth is a margin story: consolidated EBITDA margin fell to 16.35% from 22.35% in Q1 FY27 and 19.2% a year ago, and PAT margin compressed to 8.22% from 10.34% YoY — management attributes this to crude-oil-linked polymer price inflation and Red Sea-driven freight cost surges hitting the packaging industry broadly this quarter. Customer price revisions are underway and management expects the benefit to flow into realisations from Q3 FY27, making next quarter's margin trajectory the key marker to verify. There is no formal numeric FY27 revenue or margin guidance on record; the one qualitative marker from the August concall — maintaining Q1 sales levels via rented interim capacity — was exceeded, with revenue growing a further 12.3% sequentially. No analyst/street estimates for this quarter were found (Knack listed on BSE/NSE only in July 2026), so vs-street is unknown.
Alongside the result, the company secured a ₹150 Cr/3-year annual order (announced Oct 2) that should support the revenue run-rate, while a senior management personnel resignation (Oct 17) is a governance item to track with no stated earnings impact. The ₹380 Cr new Borisana plant (70k tons capacity, flagged for October 2027 commissioning) remains on schedule, though only ₹7.04 Cr of the ₹320 Cr IPO allocation for it has been deployed so far (₹323.9 Cr of the full ₹380 Cr IPO proceeds remain unutilised). CMD Alpesh Patel's press release framed the quarter as 'stable performance,' noting EBITDA 'increased in absolute terms' even as the margin 'slightly declined' — consistent with the numbers: EBITDA itself grew to ₹49.77 Cr from ₹38.30 Cr YoY (+29.9%) even though the margin ratio fell.