L&T Q2 FY27: PAT jumps 33% to ₹5,202 Cr on record orders; EBITDA margin dips to 8.7%
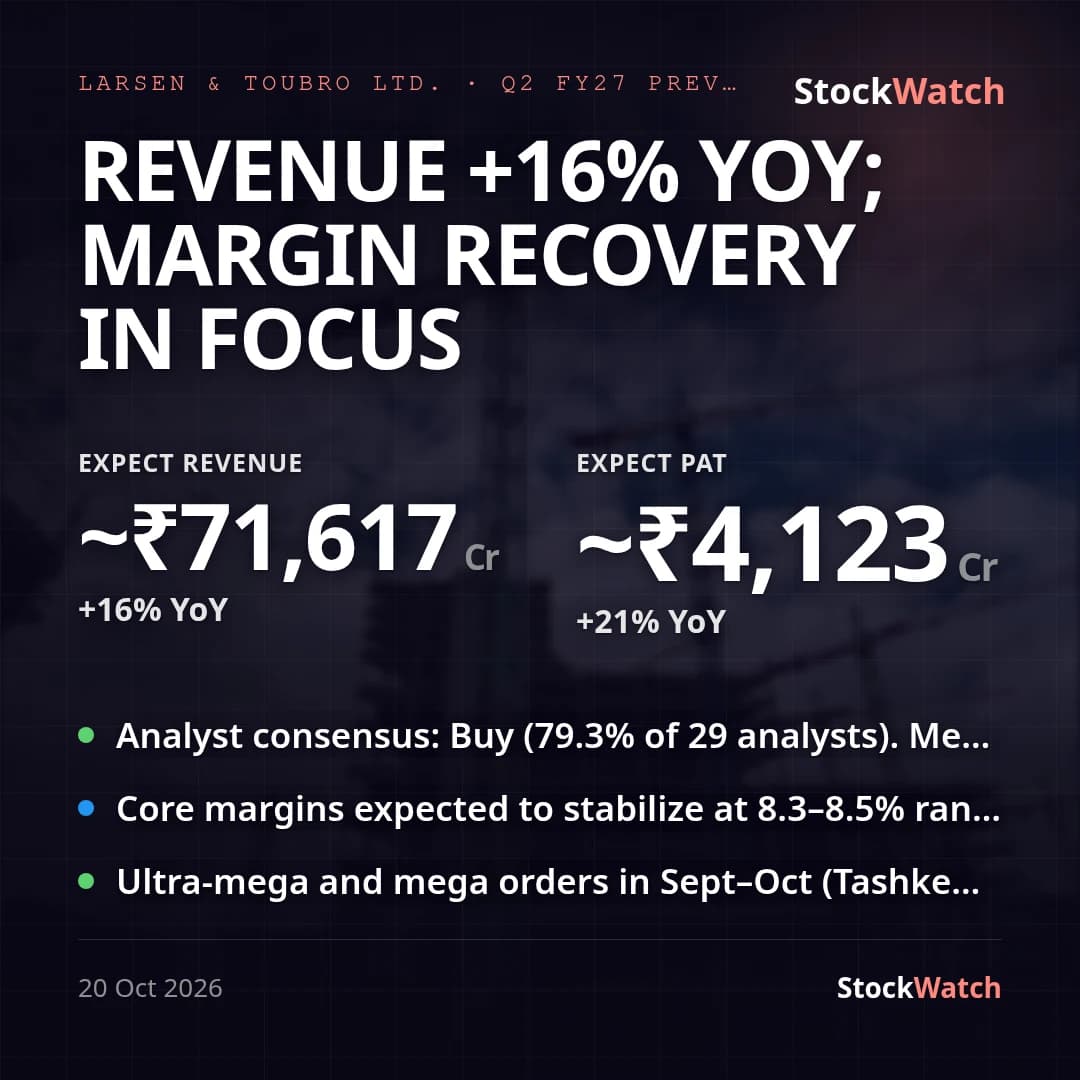
L&T's consolidated PAT (attributable to owners) rose 32.5% YoY to ₹5,202 Cr for Q2 FY27, comfortably ahead of the ~21% YoY profit growth analysts had penciled in pre-result, while consolidated revenue of ₹78,750 Cr grew 15.8% YoY and 15.9% QoQ — a sequential acceleration, since Q1 FY27 revenue (₹67,942 Cr) was itself nearly flat versus the year-ago quarter. Revenue growth came in roughly in line with the ~16% consensus estimate. Basic EPS rose to ₹37.81 from ₹28.54 a year ago. Measured against management's own medium-term aspiration flagged on the last concall — 8-10% revenue CAGR with single-digit margin improvement — L&T is tracking well ahead on growth but behind on the margin leg: EBITDA margin compressed to 8.7% from 10.0% a year ago and 9.0% last quarter, the opposite of the stated direction.
The disconnect between a 33% PAT jump and a near-flat EBITDA print (₹6,845 Cr, +1% YoY) is the quarter's real story: operating profit barely grew while bottom-line surged, driven by a 38% YoY drop in corporate finance costs (₹473 Cr vs ₹763 Cr) and a 33% jump in the Financial Services segment's PBT (₹1,319 Cr vs ₹989 Cr) on loan-book growth and stable asset quality. Segment margins were mixed: Manufacturing & Products expanded to a 15.7% EBITDA margin (from 13.5%) on a better execution mix, while Infrastructure & Utilities (5.7% vs 6.2%) and Energy-Conventional (7.4% vs 8.2%) both compressed on cost pressure and a higher share of early-stage orders — confirming the margin softness sits in the core EPC businesses, not in a one-off.
Order momentum was the standout: the Group booked a record ₹1,47,665 Cr of orders, up 28% YoY (63% international), taking the consolidated order book to an all-time-high ₹8.5 lakh crore (+15% over March'26), aided by wins flagged through the quarter — Dhaka Metro Line 1, large orders in New Delhi and Andhra Pradesh, and initial work on the Tashkent airport project. Basis divergence is sharp this quarter: standalone PAT of ₹3,370 Cr compares with a standalone LOSS of ₹3,591 Cr a year ago, but that prior-year loss was driven by a one-off ₹5,413 Cr exceptional item that never appears in the consolidated accounts — so the standalone 'turnaround' overstates the underlying trend versus the steadier 32.5% consolidated PAT growth. Development Projects, now comprising only the held-for-sale Hyderabad Metro (divestment pushed to December 31, 2026) and the nascent Green Energy business following the Nabha Power divestment on June 25, 2026, posted a ₹16 Cr EBIT loss versus an ₹87 Cr profit a year ago — immaterial to the Group P&L but a reminder the segment base is no longer comparable.
Chairman & Managing Director S N Subrahmanyan called it "a strong quarter in an ever-changing geopolitical landscape," citing "yet another record quarterly order inflow" and an order book providing "multi-year revenue visibility" — a framing the topline and order-book numbers support, though management's commentary did not directly address the EBITDA margin compression visible in the segment disclosures. Going into Q3, the open questions are whether the 130bps YoY EBITDA margin slippage reverses as the Energy-Conventional and Green segments' early-stage orders mature, and how quickly the record order book converts into billed revenue.