StockWatch
·

LUMAX INDUSTRIES LTD.

BSE: 517206

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27·vs Q2 FY26
Revenue
1.3K
+8.3%+32.8%
Expenditure
1.3K
+9.8%+32.2%
Net Profit
39.14
-24.7%+51.8%
OPM %
8.04%
-0.82pp-0.64pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.00375.91751.821.1K1.5KQ2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

33% Growth, but the Margin Question Defines H2

automotive lighting · LED penetration · margin recovery

Result verdictFollow-upQ2 FY2703 Nov 20266 minAutomobile

Lumax Q2 FY27: consolidated PAT +46% YoY to ₹52 Cr on 33% revenue growth, OPM dips to 8.2%

auto components · led lighting · margin compression

ResultsQ2 FY2726 Oct 20263 minAutomobile

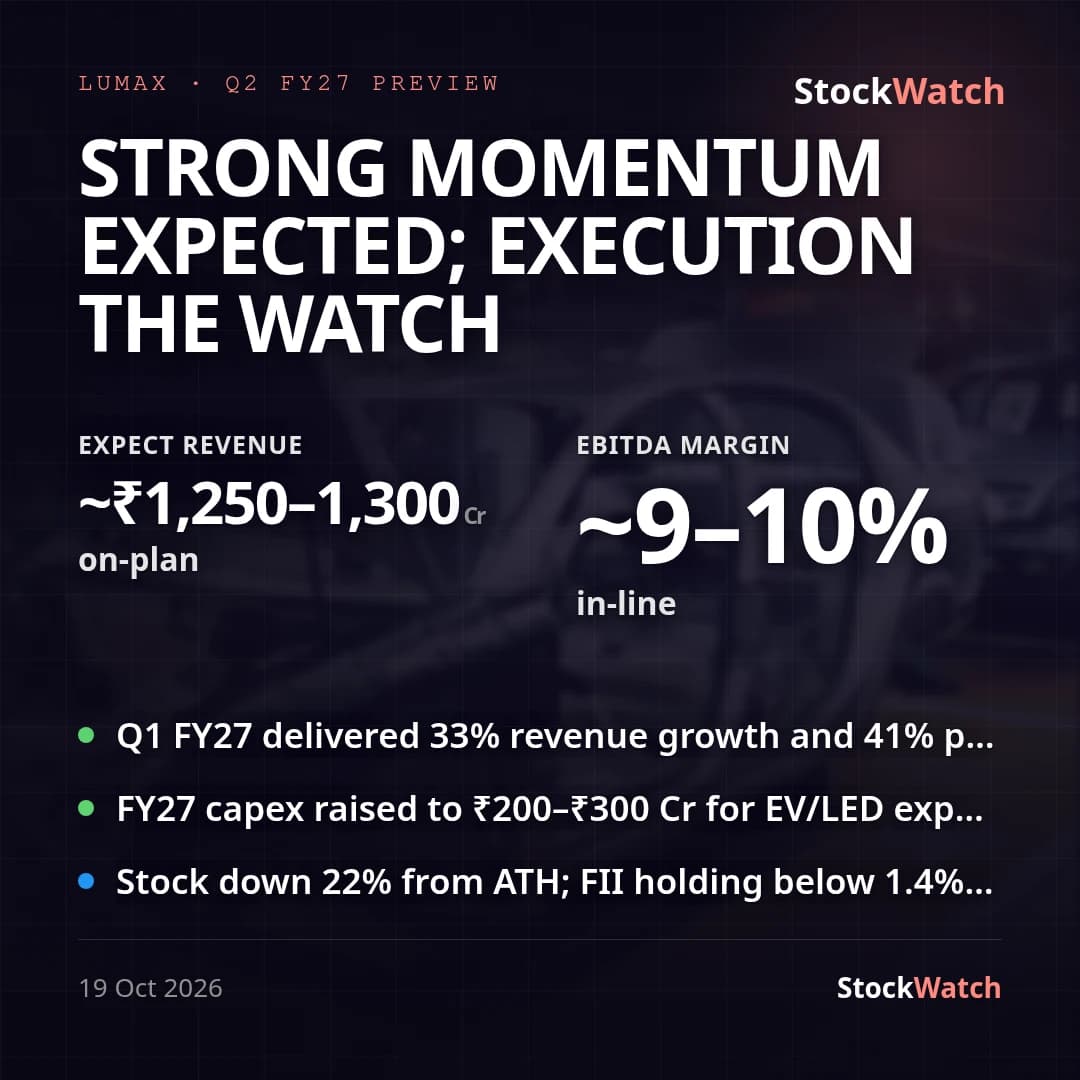
The 30% growth question: Can Lumax sustain its breakout pace into H2?

automotive components · LED lighting · EV content

Result previewQ2 FY2720 Oct 20263 minAutomobile
Latest
Board Meeting26 Oct, 2:16 pm

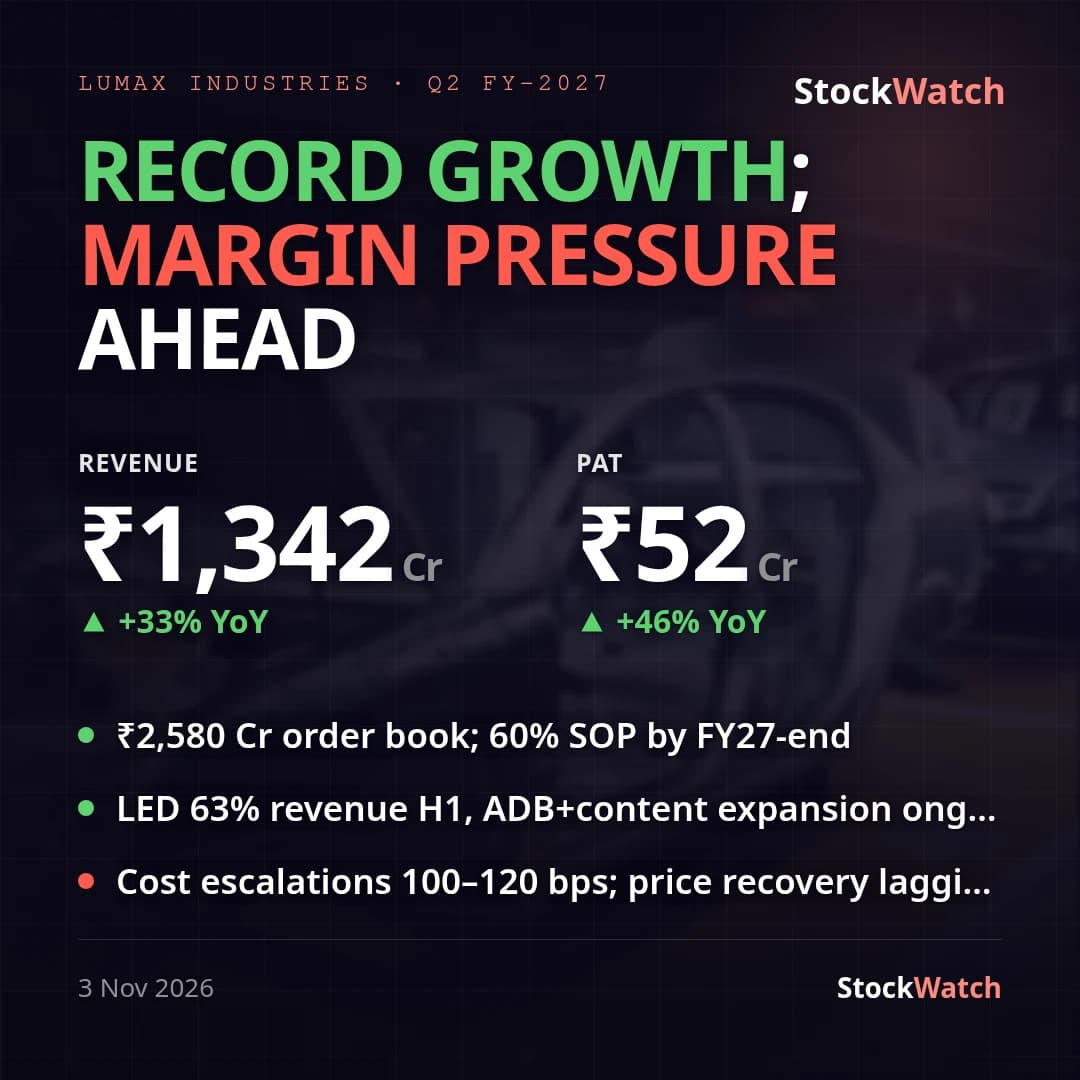
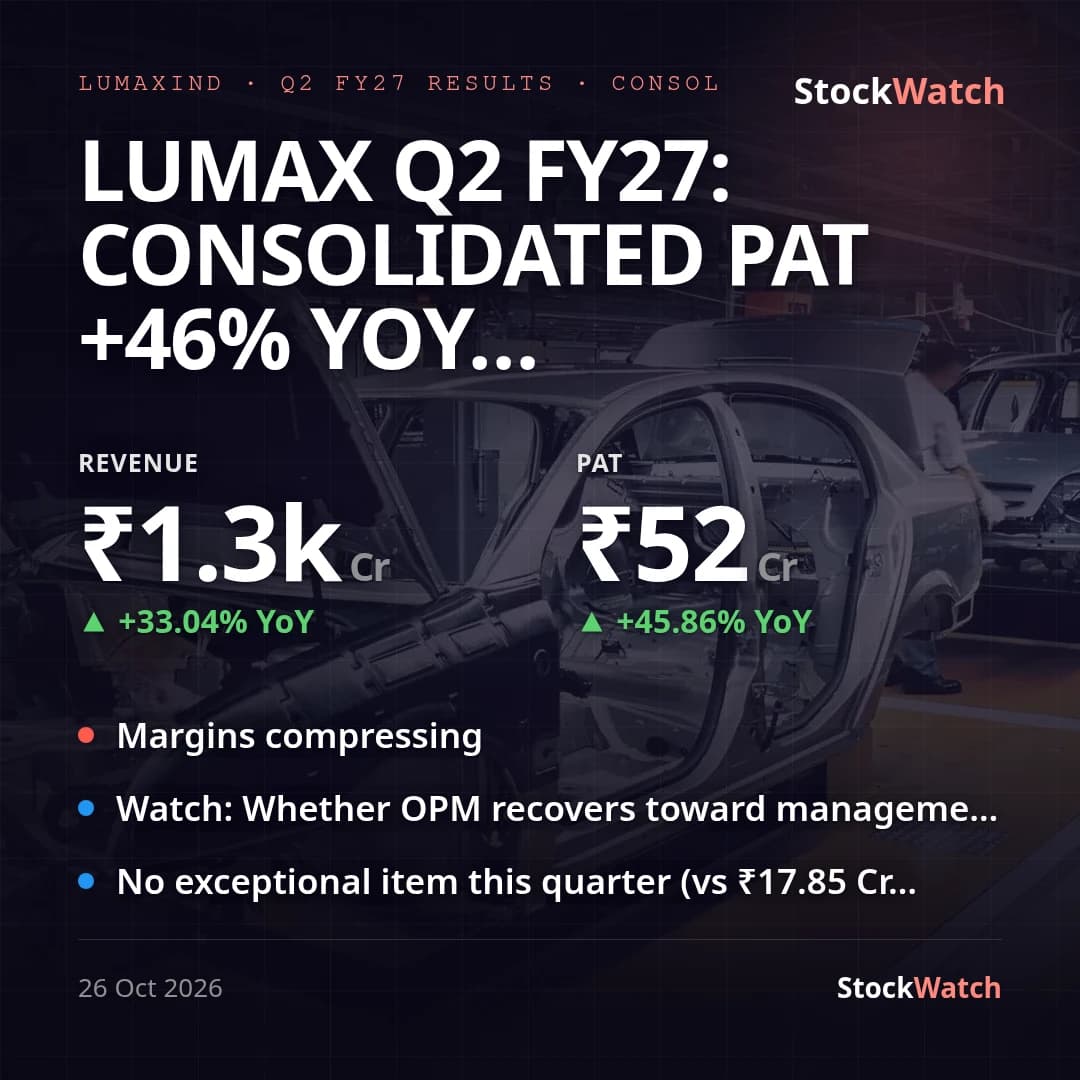
Lumax Q2 FY27: consolidated PAT +46% YoY to ₹52 Cr on 33% revenue growth, OPM dips to 8.2%

Lumax Industries' consolidated Q2 FY27 (quarter ended September 30, 2026) revenue rose 33.0% YoY to ₹1,341.84 Cr from ₹1,008.60 Cr, and 9.7% QoQ from ₹1,223.23 Cr. Consolidated PAT — the primary basis, since it diverges materially from standalone this quarter — climbed 45.9% YoY to ₹51.99 Cr from ₹35.64 Cr, though the QoQ advance was a much steadier 1.8% over Q1's ₹51.08 Cr, underlining that the YoY jump, not the QoQ print, is the real story. EPS was ₹55.62 versus ₹38.13 a year earlier. Standalone PAT was lower at ₹39.14 Cr on the identical ₹1,341.84 Cr revenue base. Net margin expanded to 3.87% from 3.53% YoY, but that masks a softer operating print: EBITDA margin (OPM) came in near 8.2%, down from 8.97% in Q1 FY27 and 8.80% in Q2 FY26 — compression on both counts even as PAT grew. The gap between NPM expansion and OPM compression is explained by the ₹16.46 Cr share of associate (SL Lumax) profit recognized in consolidated PBT this quarter (consolidated PBT ₹69.57 Cr vs standalone ₹52.43 Cr) — a non-operating contribution that lifts the bottom line without showing up in the cost structure. No exceptional item was booked this quarter, so the print is otherwise clean of one-offs (FY26 carried a ₹17.85 Cr labour-code related exceptional charge). Against management's own FY27 outlook from the Q1 concall — revenue growth of 15-20%, EBITDA margin of 10.5-11%, and capex of ₹200-250 Cr — this quarter's 33% YoY revenue growth runs well ahead of plan, but ~8.2% OPM sits meaningfully below the guided margin band and has now slipped for two straight quarters, a shortfall worth tracking into H2. H1 FY27 capex (PP&E including CWIP, per the cash-flow statement) of ₹139.36 Cr is broadly on pace with the raised full-year guidance. We found no quarter-specific Street estimate for Q2 FY27 to benchmark against; Q1 FY27 had beaten broker PAT estimates by roughly 12%, and full-year FY27 consensus pegs revenue near ₹4,980 Cr (+19%), a bar this quarter's growth rate is tracking comfortably ahead of. Lumax did not issue a separate press release with this filing. Alongside the results, the board approved issuing ₹50 Cr of unlisted commercial paper to Kotak Mahindra Bank — a funding step that lines up with the working-capital build visible in the cash flow, where trade receivables rose ₹182.7 Cr and inventories ₹157.0 Cr over H1 FY27 as the business scaled. This sets up H2 FY27 as the test of whether OPM can recover toward the 10.5-11% guided band even as revenue growth continues to outpace the 15-20% full-year target, with the fresh ₹50 Cr CP facility giving near-term working-capital headroom to support that growth.

26 Oct 2026, 02:16 pm

Board Meeting8 Aug, 4:30 pm

Lumax Industries Q1FY27: Consolidated PAT up 41% YoY to ₹51 Cr on 33% revenue growth

Lumax Industries reported consolidated revenue of ₹1,223.23 Cr for Q1 FY27 (quarter ended June 30, 2026), up 32.6% year-on-year from ₹922.52 Cr, with consolidated net profit rising 41.2% YoY to ₹51.08 Cr from ₹36.19 Cr. Sequentially, growth was far more muted — revenue grew just 1.9% and PAT fell 5.6% versus Q4 FY26's ₹1,200.32 Cr revenue and ₹54.10 Cr PAT, so the strength here is a YoY story riding a soft year-ago base rather than fresh sequential acceleration. Consolidated NPM expanded modestly to 4.18% from 3.91% a year ago, and calculated EBITDA margin was roughly flat at ~8.97% versus 8.87% YoY, though both margins are down from Q4's seasonally stronger ~4.51%/~10.2% levels. There were no exceptional items in either the current or year-ago quarter, so both the revenue and PAT YoY comparisons are clean with no adjustment needed. The standalone entity tells a sharper story: standalone PAT surged 104.6% YoY to ₹51.99 Cr from ₹25.41 Cr, well ahead of the consolidated growth rate. The gap traces to the associate SL Lumax Limited, whose equity-accounted profit contribution to the Group fell 17.2% YoY to ₹11.25 Cr from ₹13.59 Cr, dragging consolidated growth below the standalone print. Relatedly, consolidated PAT (₹51.08 Cr) is actually marginally below standalone PAT (₹51.99 Cr) because consolidation strips out the ₹13.38 Cr dividend Lumax received from the associate (booked as standalone other income) and replaces it with the smaller ₹11.25 Cr equity-method profit share — a normal consolidation mechanic, not a result-quality issue. At the operating level, standalone PBT before exceptional items grew 92.3% YoY on 34.0% income growth against 31.8% expense growth, reflecting genuine operating leverage off a thin base margin. No formal analyst consensus or brokerage preview for this specific quarter turned up in a web search — Lumax's earnings call with Chairman Deepak Jain and CFO Ravi Teltia is scheduled only for August 11, 2026, after this filing — so vs-Street is unknown rather than a scored beat or miss. Against management's own February 2026 guidance (revenue growth over 20% for FY27, double-digit EBITDA margins with a 12-13% two-year goal, backed by a ₹1,759 Cr order book), the quarter's 32.6% YoY revenue growth is already tracking well ahead of the >20% annual target, consistent with the bullish, confident tone management struck on that call. EBITDA margin of ~9%, however, remains short of the double-digit near-term goal, so margin build-out is still in progress even as the growth commitment is being beaten. No management press release or MD&A commentary accompanying this result was available to corroborate framing beyond the filed statements. The results were declared alongside routine governance items this quarter — the FY26 annual report/AGM notice dispatch and the August 26 AGM — none of which bear directly on the operating numbers. Going into Q2 FY27, the print sets up three things to track: whether EBITDA margin progresses toward management's double-digit goal from the current ~9%, whether the associate SL Lumax's profit contribution recovers from this quarter's 17% YoY decline, and execution against the guided ₹100-150 Cr FY27 capex and the ₹1,759 Cr order book cited in February. The August 11 earnings call should provide updated commentary on all three.

8 Aug 2026, 04:30 pm

Corporate Events

Board MeetingLUMAXIND
2026
26Oct

Board Meeting

The meeting of the Board of Directors is scheduled to consid…

BSE Filing ↗
Board MeetingLUMAXIND
2026
26Aug

Board Meeting

The Board of Directors have approved the change in the date …

BSE Filing ↗
Board MeetingLUMAXIND
2026
8Aug

Board Meeting

The meeting of the Board of Directors is scheduled to consid…

BSE Filing ↗
DividendLUMAXIND
2026
6Aug

₹55 / share

BSE Filing ↗
DividendLUMAXIND
2026
6Aug

₹55 / share

BSE Filing ↗
Board MeetingLUMAXIND
2026
28May

Board Meeting

The board meeting is scheduled to consider and approve the a…

BSE Filing ↗
Board MeetingLUMAXIND
2025
1Oct

Board Meeting

Closure of Trading Window

BSE Filing ↗
Board MeetingLUMAXIND
2025
1Jul

Board Meeting

Closure of Trading Window

BSE Filing ↗
Board MeetingLUMAXIND
2025
26May

Board Meeting

Consider and approve Intimation of Board Meeting, Audited Fi…

BSE Filing ↗
DividendLUMAXIND
2024
9Sep

₹350 / share

BSE Filing ↗
Board MeetingLUMAXIND
2024
9Feb

Board Meeting

Consideration and approval of the Un-audited Standalone and …

BSE Filing ↗