Mahindra Finance: Consolidated PAT Jumps 61% YoY to ₹911 Cr, NPM Expands to 15.3%
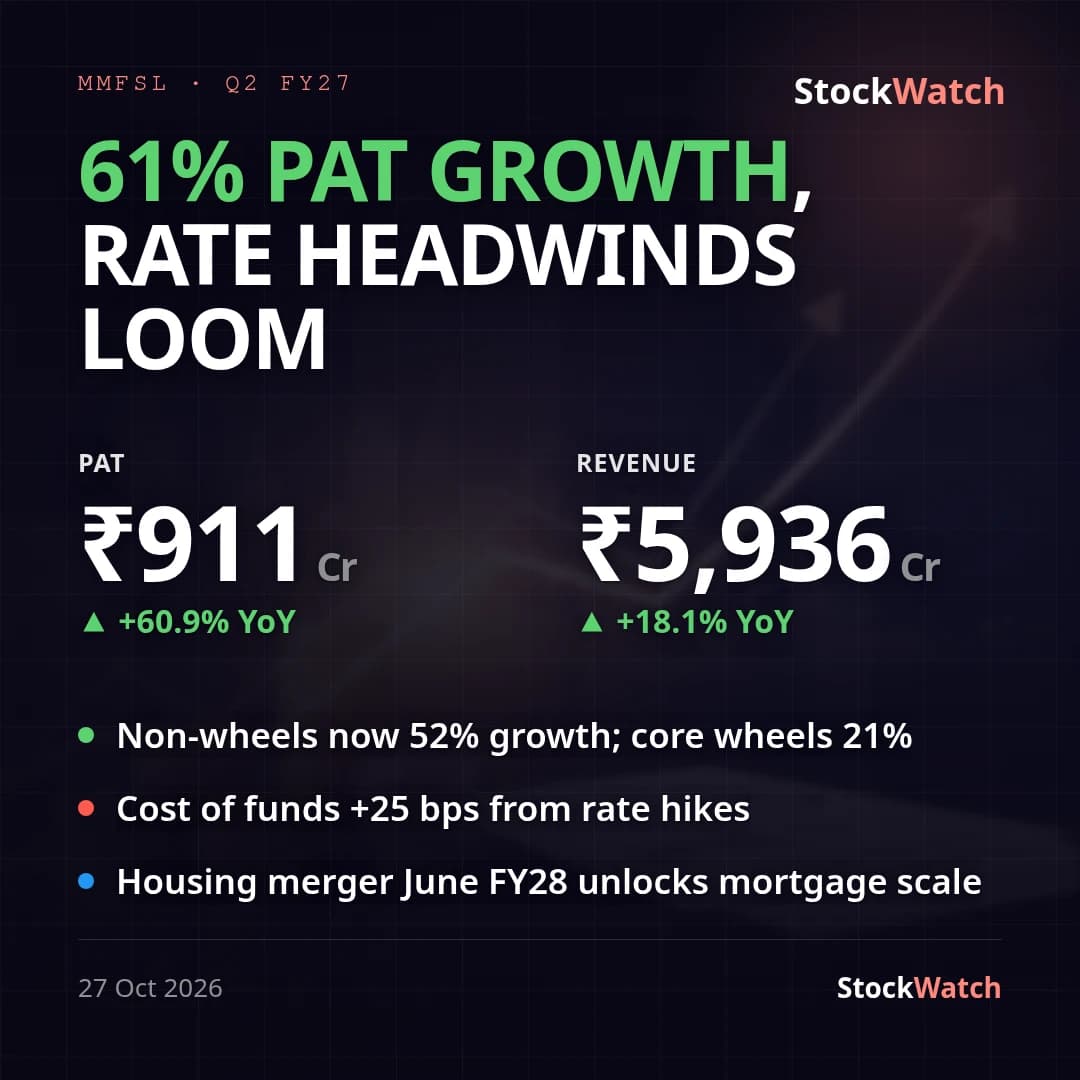
Mahindra & Mahindra Financial Services posted consolidated PAT of ₹910.73 Cr for Q2 FY27, up 60.9% YoY from ₹566.07 Cr a year ago, on consolidated revenue from operations of ₹5,935.66 Cr, up 18.1% YoY from ₹5,026.19 Cr. Standalone PAT came in at ₹881.52 Cr (EPS ₹6.34) against consolidated EPS of ₹6.54; YoY profit growth was somewhat stronger at the consolidated level (+60.9%) than standalone (+54.8%), a gap consistent with scale-up at housing-finance subsidiary MRHFL ahead of its planned April 2027 merger into the parent. Sequentially, PAT eased 1.8% QoQ from Q1 FY27's ₹927.48 Cr even as revenue grew 3.8% QoQ — a mild step-down after Q1's exceptional 75% YoY profit jump, which the pre-result preview had flagged as a tough comparison to sustain. This quarter's slower-but-still-strong 61% YoY print reads as normalization rather than deterioration, with NPM still expanding to 15.28% from 11.21% a year ago (versus 16.20% in Q1, so a touch of sequential margin give-back).
The YoY margin expansion was driven by a lower provisioning load relative to book growth: half-year impairment on financial instruments came in at ₹1,195.82 Cr, which annualizes to roughly 1.6% of the average loan book (₹1,46,017.84 Cr) — comfortably within management's guided 1.3-1.7% through-cycle credit-cost band. Finance costs rose to ₹2,523.00 Cr for the quarter from ₹2,197.68 Cr a year ago as the balance sheet grew (total assets to ₹1,80,291.69 Cr from ₹1,58,643.94 Cr at FY26-end), but revenue growth outpaced the rise in cost of funds, letting operating leverage flow through. No exceptional items hit either the current or year-ago quarter, so the 60.9% YoY PAT growth is a clean, unadjusted figure.
Against our pre-result preview (PAT ~₹850-950 Cr, revenue ~₹5,700-5,900 Cr), the print landed inline — PAT at ₹910.73 Cr sat mid-band and revenue at ₹5,935.66 Cr came in marginally above the top of the guided range. No independent brokerage consensus PAT estimate turned up in search beyond the preview itself; Street positioning (60.6% Buy rating, ₹350 median target versus a pre-result price of ₹319.45) centered on execution risk around the MRHFL merger and sustaining 20%+ disbursement growth — both of which this quarter's 22% YoY disbursement growth (to ₹16,490 Cr, per the company's October 2 business update) and the board's merger clearance help address. Standalone gross Stage-3 came in at 3.42% (net 1.51%, PCR 56.64%), within the pre-flagged 3.35-3.45% range, confirming asset quality held up as expected; collection efficiency wasn't separately disclosed in this filing, so the previewed 97% figure couldn't be independently verified. The quarter also saw ₹2,000 Cr and ₹1,250 Cr NCD raises (the latter at a 7.95% fixed coupon) and a steady-to-improved ESG rating, neither of which shows up directly in this quarter's P&L. No standalone press release commentary was available to extract management's own framing of the quarter.
Against the FY26-31 guidance from the July 2026 call (16-18% CAGR, credit cost 1.3-1.7%, ROA progressing to 2.5%, no capex for 6-8 quarters), the quarter tracks on-plan: credit cost at ~1.6% annualized sits mid-band, and annualized ROA (PAT run-rate over average total assets) works out to roughly 2.1-2.2% — still below the 2.5% target but consistent with the "progressing to" framing rather than a miss. The items to watch into H2 FY27 are whether PAT growth normalizes further toward the ~22% disbursement growth rate as Q1's high base fully laps, and how MRHFL integration and NCLT approval timelines affect the P&L ahead of the April 1, 2027 appointed date.