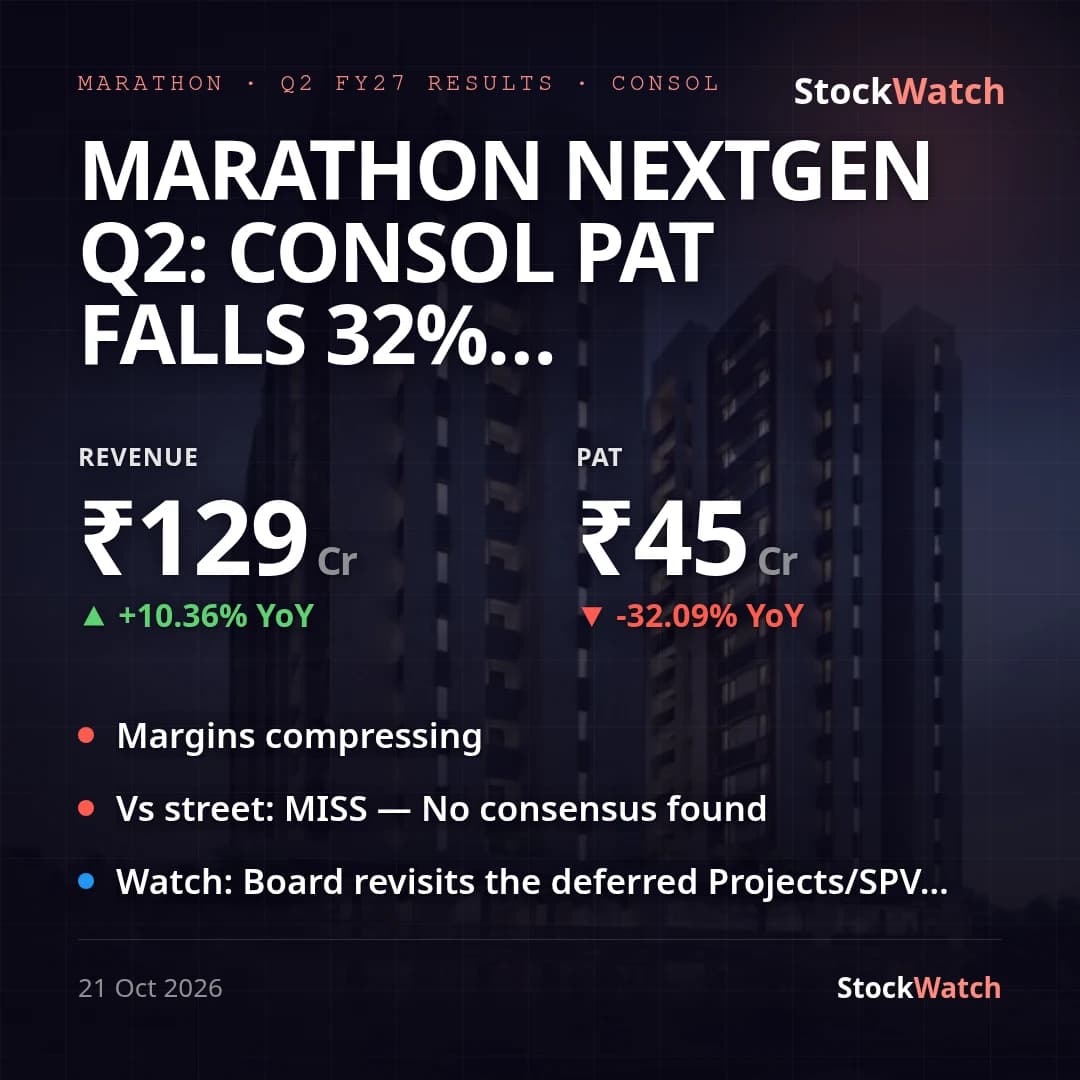
Marathon Nextgen Q2: Consol PAT Falls 32% YoY to ₹45 Cr Despite 10% Revenue Growth
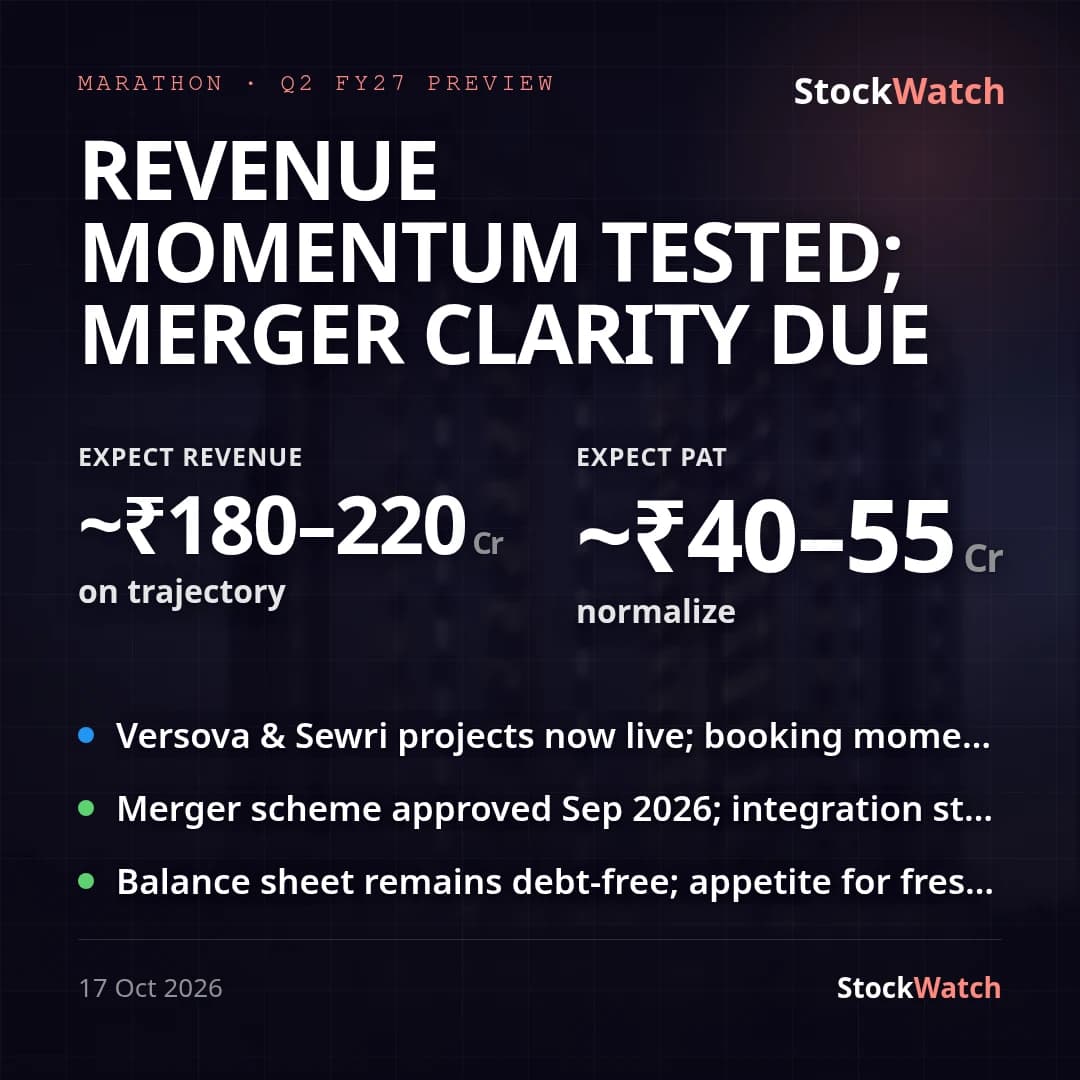
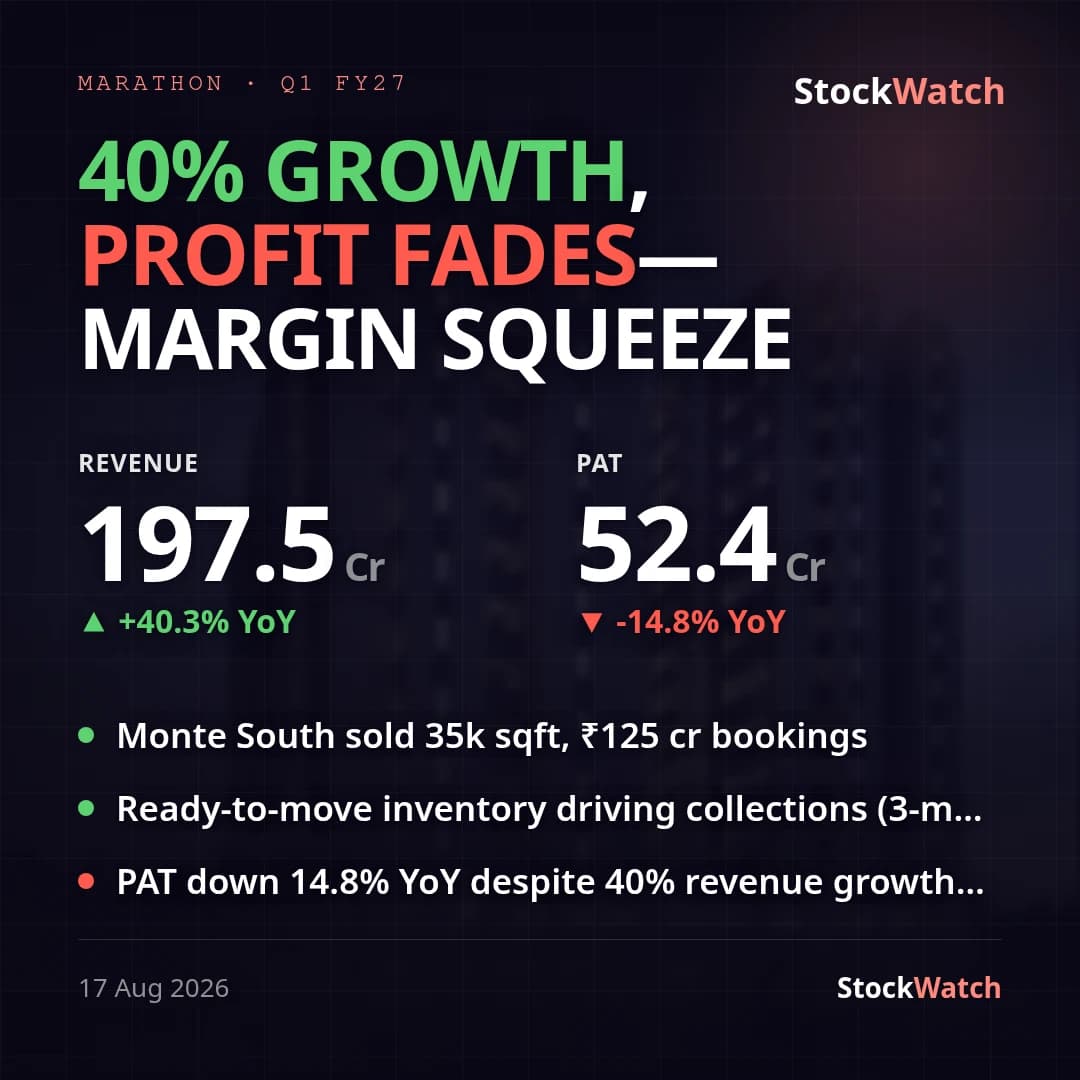
Marathon Nextgen Realty's consolidated Q2 FY27 (quarter ended September 30, 2026) net profit fell 32.1% year-on-year to ₹45.19 Cr from ₹66.54 Cr, even as consolidated revenue from operations grew 10.4% YoY to ₹128.95 Cr from ₹116.85 Cr — a profit decline despite topline growth is the primary signal this quarter. Sequentially both lines were down from Q1 FY27 (revenue -34.7%, PAT -13.8%), but that comparison is a base-effect artifact: Q1's ₹197.50 Cr revenue was itself a multi-quarter high, not a run-rate. No external sell-side consensus exists for this stock (web search found price-target commentary but no Q2 estimate); against our own pre-result preview range (revenue ₹180-220 Cr, PAT ₹40-55 Cr, EBITDA margin 28-32%), the quarter missed on revenue, landed within range on PAT, and beat on margin — netting out to a miss given revenue is the larger shortfall.
The YoY squeeze sits mainly on net margin: NPM compressed to 31.2% of total income from 42.9% a year ago (-11.7pp), while operating margin held comparatively steady at 34.97% versus 35.96% YoY. That gap implies the erosion is less about the core property-development cost mix and more about items below operating profit and a tough prior-year comparison base (Q2 FY26's 42.9% NPM was unusually high). Standalone entity profitability (₹47.79 Cr PAT, EPS ₹7.09) was actually higher than the consolidated figure and nearly flat YoY (-1.1% revenue), underscoring that consolidated YoY growth comes from subsidiaries and the joint-venture share (₹3.53 Cr), not the parent — an 11-point-plus divergence between standalone and consolidated revenue growth worth flagging since readers will see both numbers.
Management gave no explicit FY27 revenue or PAT target on the last call, so there is no formal topline/bottom-line guidance to grade; the firmer commitment was to deploy ₹200 Cr of capital at a 30-35% EBITDA hurdle and launch new redevelopment projects (Versova/Sewri, ~₹900 Cr GDV) selectively. This quarter's ~35% OPM clears that margin hurdle, but the Board's own outcome letter states the agenda item for new investments in Projects/SPVs 'was deferred' — the capital-deployment decision flagged for this quarter did not happen, a miss on that specific timeline. Separately, merger integration advanced: the Company Scheme Petition (second motion) was filed with the NCLT on September 24, 2026, following the September 8 shareholder approval of the five-entity amalgamation. QIP proceeds of ₹899.99 Cr are now ~77% utilized (₹695.40 Cr), with the ₹203.79 Cr balance parked in mutual funds, debentures and bonds. No separate management press release was available in the record to check messaging against the numbers.
Going into Q3, the deferred investment decision and the pending NCLT scheme hearing are the concrete items to track, alongside whether NPM recovers toward its historical 40%+ band or settles near this quarter's low-30s level.