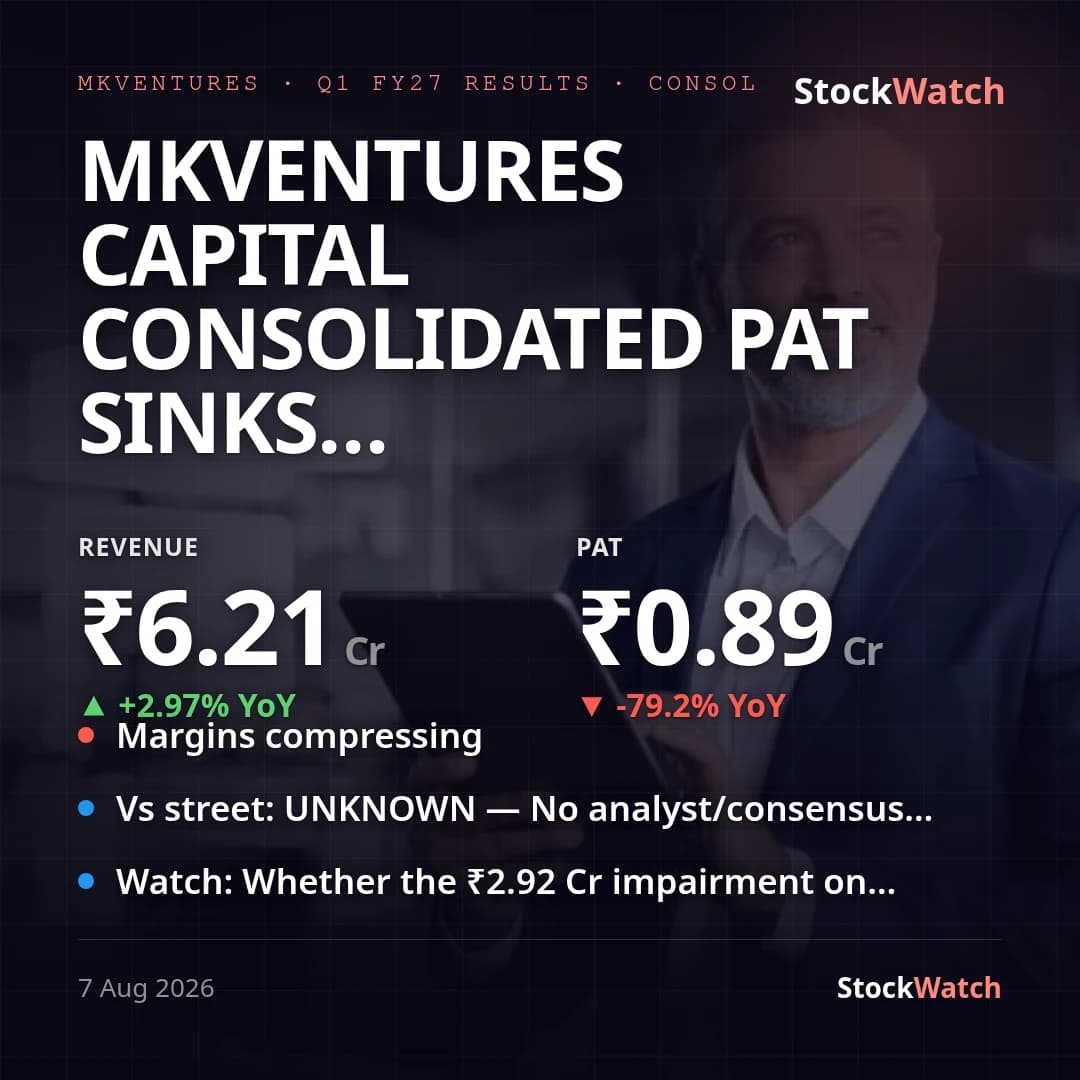
Mkventures Capital consolidated PAT sinks 79% YoY on one-off ₹2.92 Cr loan impairment
Mkventures Capital, a small NBFC split between a Loan & Investment book and a Consultancy division, posted consolidated Q1 FY27 (quarter ended June 30, 2026) revenue of ₹6.21 Cr, up 2.97% YoY, but PAT of ₹0.89 Cr, down 79.2% YoY from ₹4.29 Cr. The entire swing traces to a ₹2.92 Cr impairment provision on financial instruments booked this quarter against the Loans & Investment book — a charge absent in both Q1FY26 and Q4FY26 — which flipped that segment from a ₹3.15 Cr profit a year ago to a ₹1.07 Cr loss. Adding the impairment back, adjusted PAT is roughly ₹3.81 Cr, about 11% below the year-ago quarter — a far steadier underlying picture than the reported 79% collapse implies. NPM compressed to 14.2% from 65.5% YoY (and from 19.7% QoQ); OPM (PBT/revenue from operations) fell to 35.0% from 91.8% YoY, though it actually improved sequentially from 28.6% in Q4FY26, helped by the Consultancy division growing revenue and profit to ₹4.65 Cr from ₹2.90 Cr a year ago, which cushioned the lending-side hit.
The company carries no analyst coverage and no published street estimates were found (web search), and management has issued no formal guidance or outlook on record, so vsStreet and vsGuidance are both unknown; there is also no prior concall on record to check tone against. The filing itself carries no separate management commentary beyond standard Ind AS 34 notes on segment reporting and prior-period regrouping. The quarter's other corporate action — the May 28, 2026 board meeting that appointed Ajay Shah as MD & CEO and approved a ₹0.25/share interim FY26 dividend — predates this filing and is unrelated to the impairment charge. Capital adequacy stays very high for the lending book, with CRAR at 76.98% (Tier I 76.66%), underscoring that this is a thinly capitalised, low-scale NBFC where a single provisioning call can swing reported profit sharply from one quarter to the next.