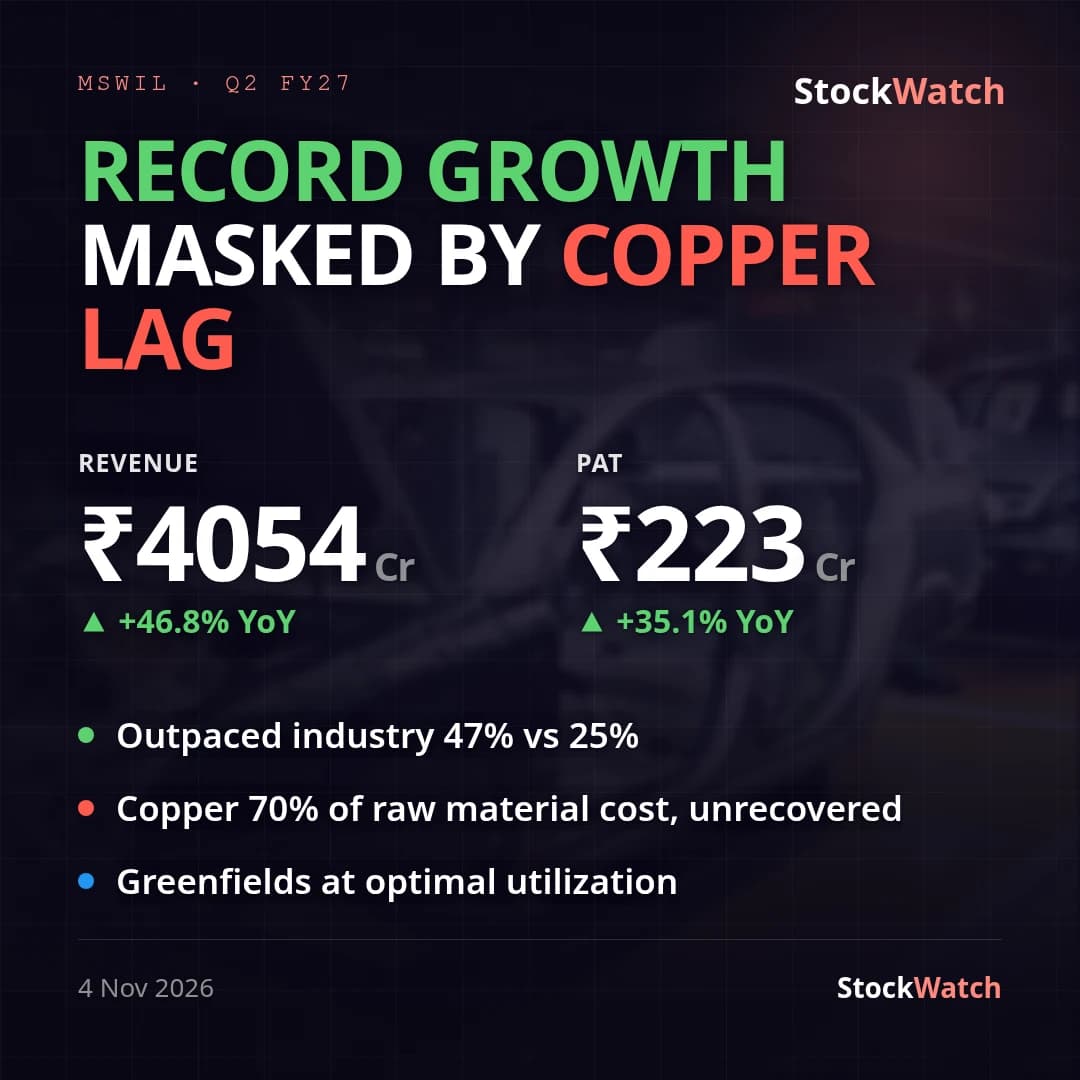
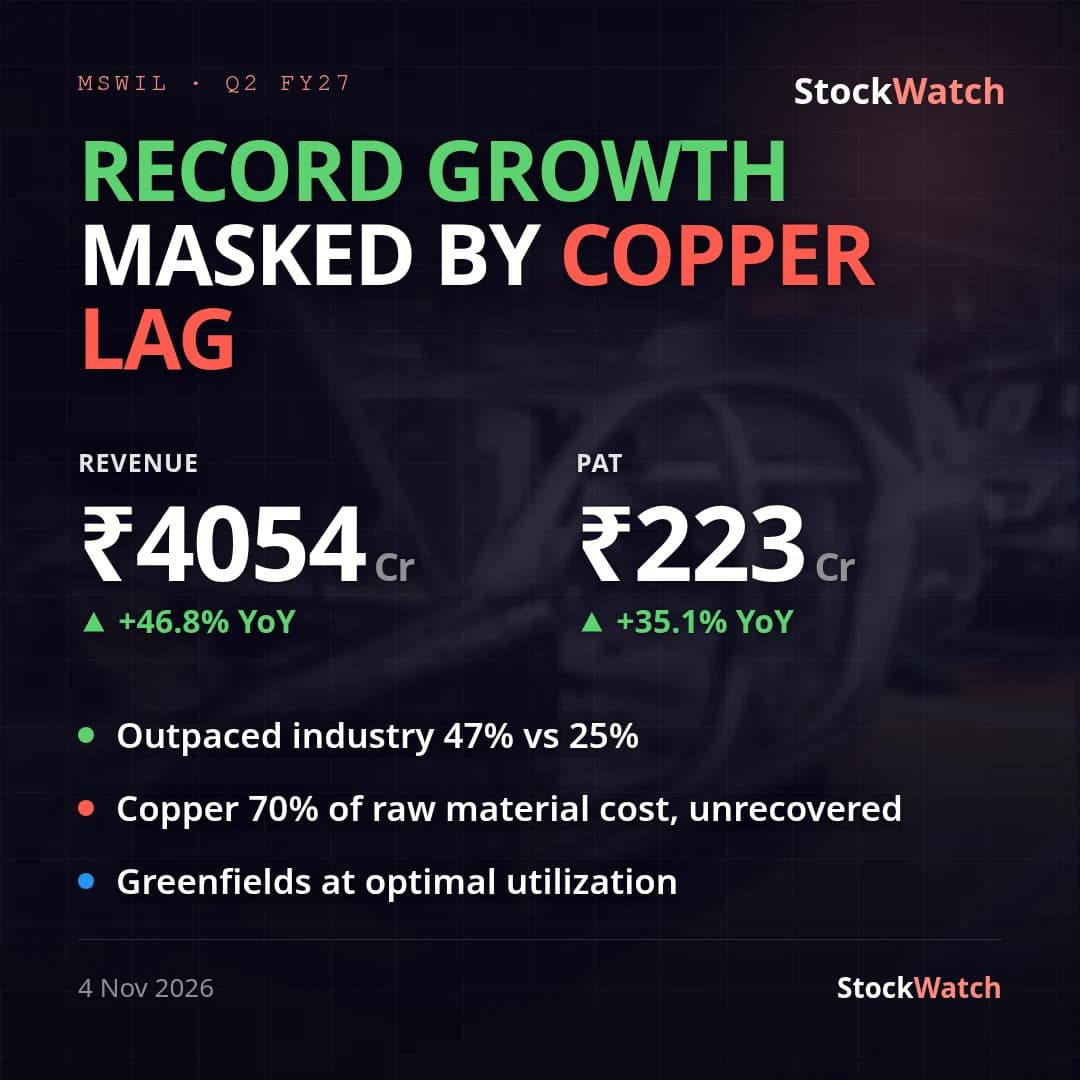
Revenue surges 47% YoY to ₹4,054 Cr, but margin compression caps PAT growth at 35%
Motherson Sumi Wiring India's standalone Q2FY27 (quarter ended September 30, 2026) revenue from operations rose 46.8% YoY to ₹4,053.83 Cr from ₹2,761.86 Cr, well ahead of the ~₹3,400–3,500 Cr range flagged in our pre-result preview and consistent with management's own framing of "Revenue Surges 47% YoY to ₹4,054 Crore" (total income ₹4,054.97 Cr). PAT rose 35.1% YoY to ₹223.37 Cr from ₹165.34 Cr — a clear beat against the preview's single-digit PAT growth expectation — though profit growth trailed revenue growth as margins compressed versus a year ago.
The gap between revenue and profit growth sits on the operating line: EBITDA margin (OPM) came in at 9.22% against 10.13% a year ago, a 91bps YoY compression, while net margin eased to 5.51% from 5.98% (-47bps). Sequentially, though, both margins expanded sharply — OPM from 7.58% and NPM from 4.26% in Q1FY27 — consistent with management's prior guidance that wage hikes (35-40% in NCR) are now fully absorbed and that copper cost pass-through, which lags 3-6 months, would show partial quarterly recovery. No exceptional items appear in either the current or year-ago quarter, so both comparisons are on a clean, unadjusted basis.
No updated formal guidance range accompanies this filing beyond the prior concall's qualitative color; against that backdrop the quarter reads as on-track rather than a clean beat or miss on margins — recovery is visible QoQ but YoY margins haven't fully caught up, matching the "cautiously optimistic" near-term, "optimistic" long-term stance management struck last quarter. Street consensus (per our preview) carried a Buy-leaning 10-of-12-analyst base with a median target of ₹47.50 against FY27 revenue guidance of +14.45% YoY (external consensus pegs FY27 revenue at ~₹13,140 Cr); H1FY27 revenue of ₹7,467.61 Cr already covers 56.8% of that full-year estimate, suggesting it may prove conservative if the second-half run-rate holds. The company reiterated it has no subsidiary, associate or JV as of September 30, 2026, leaving the standalone statement as the only one to read.
The next checkpoints are whether OPM continues closing the YoY gap as copper pass-through completes, and whether the ~₹2,000 Cr annualized greenfield ramp-up management cited last quarter shows up as incremental H2 volume.