StockWatch
·

MUKAND LTD.

BSE: 500460

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27·vs Q2 FY26
Revenue
1.3K
-10.5%+11.7%
Expenditure
1.3K
-8.2%+13.0%
Net Profit
15.89
-74.1%-0.1%
OPM %
4.73%
+4.75pp-1.99pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.00485.08970.161.5K1.9KQ2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

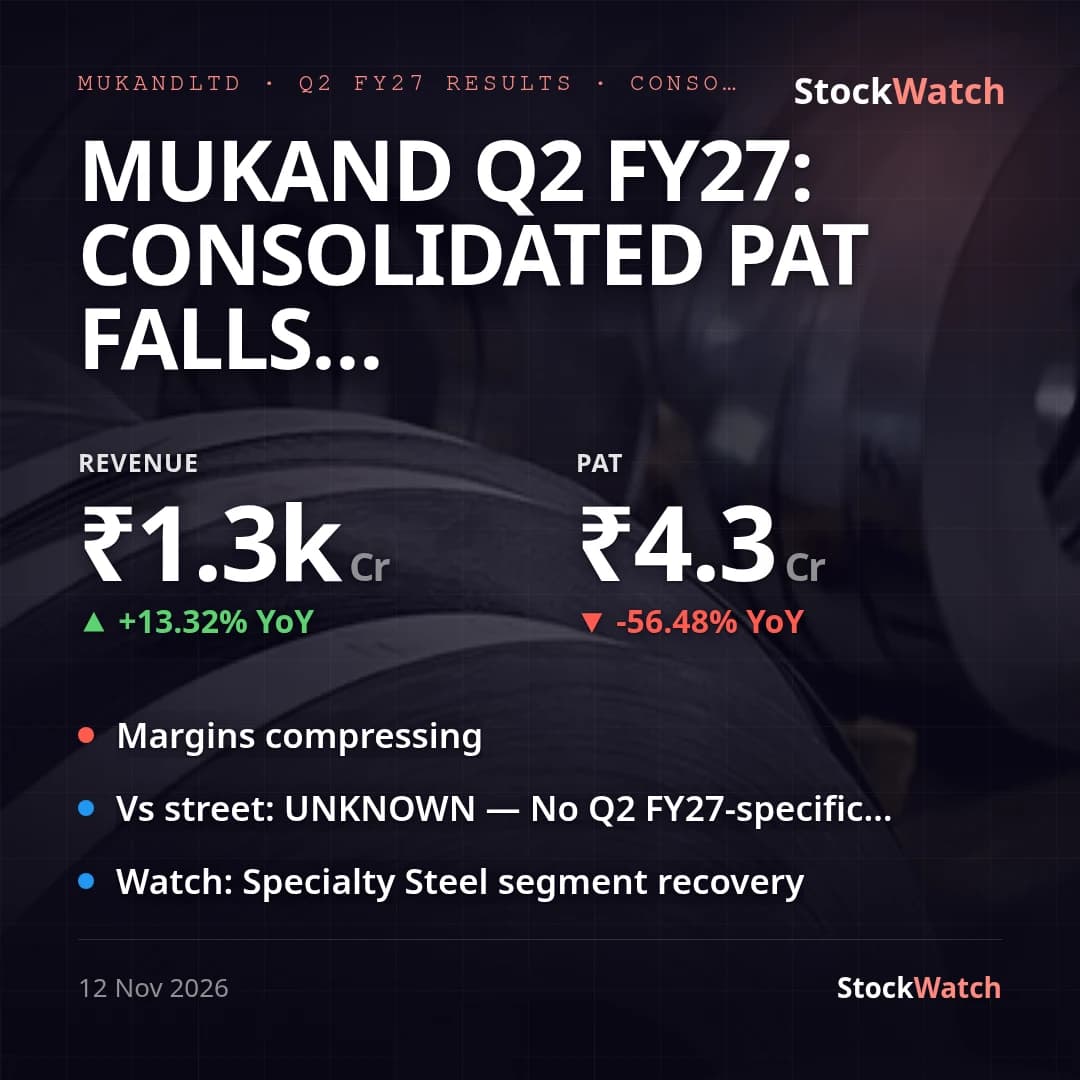
Mukand Q2 FY27: consolidated PAT falls 56% YoY to ₹4.3 Cr despite 13% revenue growth

specialty steel · margin compression · land sale one-off

ResultsQ2 FY2712 Nov 20263 minMetals & Mining

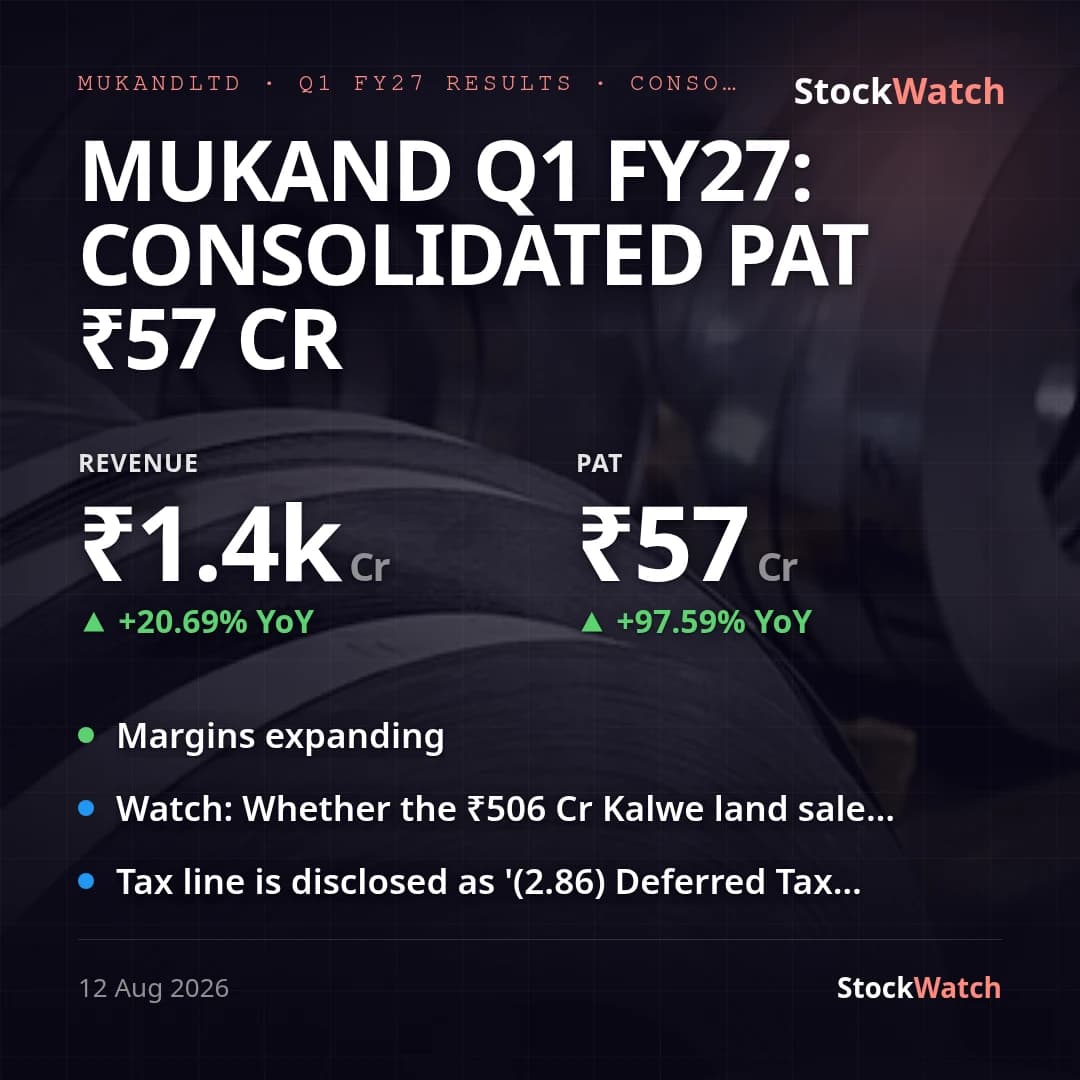
Mukand Q1 FY27: consolidated PAT ₹57 Cr, up 98% YoY but flattered by land-sale gain

specialty steel · land sale gain · one-off other income

ResultsQ1 FY2712 Aug 20263 minMetals & Mining
Latest
Quarterly Result12 Nov, 1:52 pm

Mukand Q2 FY27: consolidated PAT falls 56% YoY to ₹4.3 Cr despite 13% revenue growth

Mukand's consolidated revenue grew 13.3% YoY to ₹1,315.15 Cr in the quarter ended September 30, 2026, but consolidated PAT fell 56.5% YoY to ₹4.30 Cr from ₹9.88 Cr, and dropped 92.5% sequentially from ₹57.36 Cr in Q1 FY27. EPS came in at ₹0.30 against ₹0.68 a year earlier and ₹3.97 last quarter. NPM compressed to 0.33% from 0.85% YoY and 4.21% QoQ — growth in revenue did not translate into profit. The sequential collapse is largely a base effect: Q1 FY27's ₹57.36 Cr print was flattered by Other Income of ₹105.04 Cr that quarter, which the company's own notes attribute to the accounted surplus from conveying ~3.07 acres at Kalwe and a 50% stake in ~0.06 acres at Dighe. Q2's Other Income normalised to ₹5.32 Cr. The YoY comparison is cleaner, since last year's Other Income was similarly modest (₹2.76 Cr), and it shows the pressure sits in the core business: Total Segment Result (Specialty Steel plus Industrial Machinery & Engineering) fell to ₹39.53 Cr from ₹57.61 Cr a year ago and ₹91.32 Cr last quarter. The Specialty Steel segment result nearly halved YoY to ₹41.88 Cr from ₹66.82 Cr even as that segment's revenue rose to ₹1,261.24 Cr from ₹1,138.72 Cr — spread/margin compression despite higher steel revenue. Finance costs actually eased slightly to ₹34.37 Cr from ₹37.53 Cr YoY, so the squeeze is operating, not financing. Standalone PAT (continuing operations) of ₹15.89 Cr sits well above the consolidated ₹4.30 Cr; the ~₹11.6 Cr gap traces to losses at subsidiaries and the joint venture (Mukand Sumi Metal Processing, Mukand Heavy Engineering, Hospet Steels) — a materially wider divergence than the usual standalone-consolidated gap, worth noting since readers comparing the two could otherwise read one as wrong. The company has no formal guidance or prior outlook on record, and no management press release accompanied this filing, so there is nothing to grade the print against on that front. A web search for Street estimates turned up no analyst consensus specific to this September-2026 quarter — only an unrelated Q1 FY27 preview and a full-year FY27 PAT estimate (₹675 Cr) that does not reconcile with H1 FY27 actuals (₹61.66 Cr consolidated) — so vsStreet is unknown rather than assumed. The Kalwe land monetisation is not fully done: a separate note discloses a July 2026 term sheet for ~9.20 acres at Kalwe, still carried as "Assets Held for Sale" (₹15.94 Cr) pending government and regulatory approvals, which could bring another one-off gain whenever it closes. Absent further land-sale inflows, Q3 FY27 will show whether the Specialty Steel segment's profitability recovers from this quarter's compressed levels.

12 Nov 2026, 01:52 pm

Board Meeting12 Aug, 11:41 am

Mukand Q1 FY27: consolidated PAT ₹57 Cr, up 98% YoY but flattered by land-sale gain

Mukand Ltd's consolidated Q1 FY27 (quarter ended June 30, 2026) revenue rose 20.7% YoY to ₹1,362.21 Cr (₹1,128.71 Cr a year ago) and 7.3% QoQ (₹1,269.09 Cr in Q4 FY26), while consolidated PAT nearly doubled YoY to ₹57.36 Cr (+97.6% from ₹29.03 Cr) but fell 89.7% QoQ from ₹554.98 Cr. Standalone (secondary) PAT was ₹61.33 Cr on PBT of ₹64.19 Cr and revenue of ₹1,325.68 Cr; the two bases tell a broadly consistent story this quarter (well under 3% divergence in growth), so consolidated is used throughout. Both the YoY jump and the QoQ collapse are distorted by one-off items sitting in Other Income on either side of the comparison. Consolidated Other Income roughly tripled YoY to ₹105.04 Cr from ₹38.68 Cr; the ~₹66 Cr delta closely tracks a rise in standalone Miscellaneous Income (₹104.54 Cr vs ₹36.19 Cr), which the company ties (Notes 2-3) to the conveyance deed executed this quarter for ~3.07 acres of Kalwe land plus a 50% share of 0.06 acres at Dighe. Tax-effecting that estimated one-off at this quarter's ~4.75% effective rate (tax charge of just ₹2.86 Cr on ₹60.22 Cr PBT), adjusted YoY PAT growth looks closer to a swing toward breakeven than the +97.6% headline suggests — net profit margin (PAT/total income) did improve to 3.91% from 2.49% YoY, but that improvement leans heavily on the land gain. That said, the Specialty Steel segment's own operating result also rose to ₹89.2 Cr from ₹40.6 Cr YoY, so some of the gain looks operational too; the filing's disclosure doesn't allow the one-off and any organic improvement to be cleanly separated, so both the raw and adjusted figures should be read with that caveat. On the other side, the QoQ fall from ₹554.98 Cr is a high-base effect: Q4 FY26 Other Income was ₹508.34 Cr, including a ₹173.65 Cr fair-value gain on equity investments — a far larger one-off than this quarter's land gain — so the sequential decline overstates any operational slowdown. Management gives no formal guidance on record, and our prior-quarter concall notes hold none either, so there is no outlook to grade this print against. A web search for Street/consensus estimates for this quarter surfaced only share-price targets (Univest, ~₹145-180) rather than PAT or revenue estimates, so vsStreet is unknown. The filing carries no separate management press release beyond the standard board-outcome letter and result notes. Corporate developments this quarter line up with the land-sale note: the company signed a term sheet on July 15, 2026 to sell a further ~9.20 acres at Kalwe for ₹506 Cr, disclosed as 'Assets Held for Sale' under Ind AS 105 and pending regulatory approvals (Note 4) — that transaction has not yet hit the P&L. Separately, the board had already approved a ₹3/share dividend in May 2026, and a 30% dividend record date was set on July 21, 2026, alongside the FY26 annual report/AGM notice — none of these affect this quarter's P&L directly.

12 Aug 2026, 11:41 am

Corporate Events

Board MeetingMUKANDLTD
2026
12Nov

Board Meeting

The Board of Directors meeting is scheduled to consider and …

BSE Filing ↗
Board MeetingMUKANDLTD
2026
12Aug

Board Meeting

The Board of Directors meeting is scheduled to consider and …

BSE Filing ↗
DividendMUKANDLTD
2026
7Aug

₹3 / share

BSE Filing ↗
Board MeetingMUKANDLTD
2026
14May

Board Meeting

To consider and approve the Audited Financial Results for th…

BSE Filing ↗
DividendMUKANDLTD
2025
25Jul

₹2 / share

BSE Filing ↗
Board MeetingMUKANDLTD
2024
5Aug

Board Meeting

Consider and approve the Unaudited Financial Results (Standa…

BSE Filing ↗
Board MeetingMUKANDLTD
2024
15May

Board Meeting

Consideration and approval of Audited Financial Results for …

BSE Filing ↗
Board MeetingMUKANDLTD
2024
9Feb

Board Meeting

Consider and approve Un-audited Financial Results (Standalon…

BSE Filing ↗
Board MeetingMUKANDLTD
2023
9Nov

Board Meeting

Consideration and approval of Un-audited Financial Results (…

BSE Filing ↗