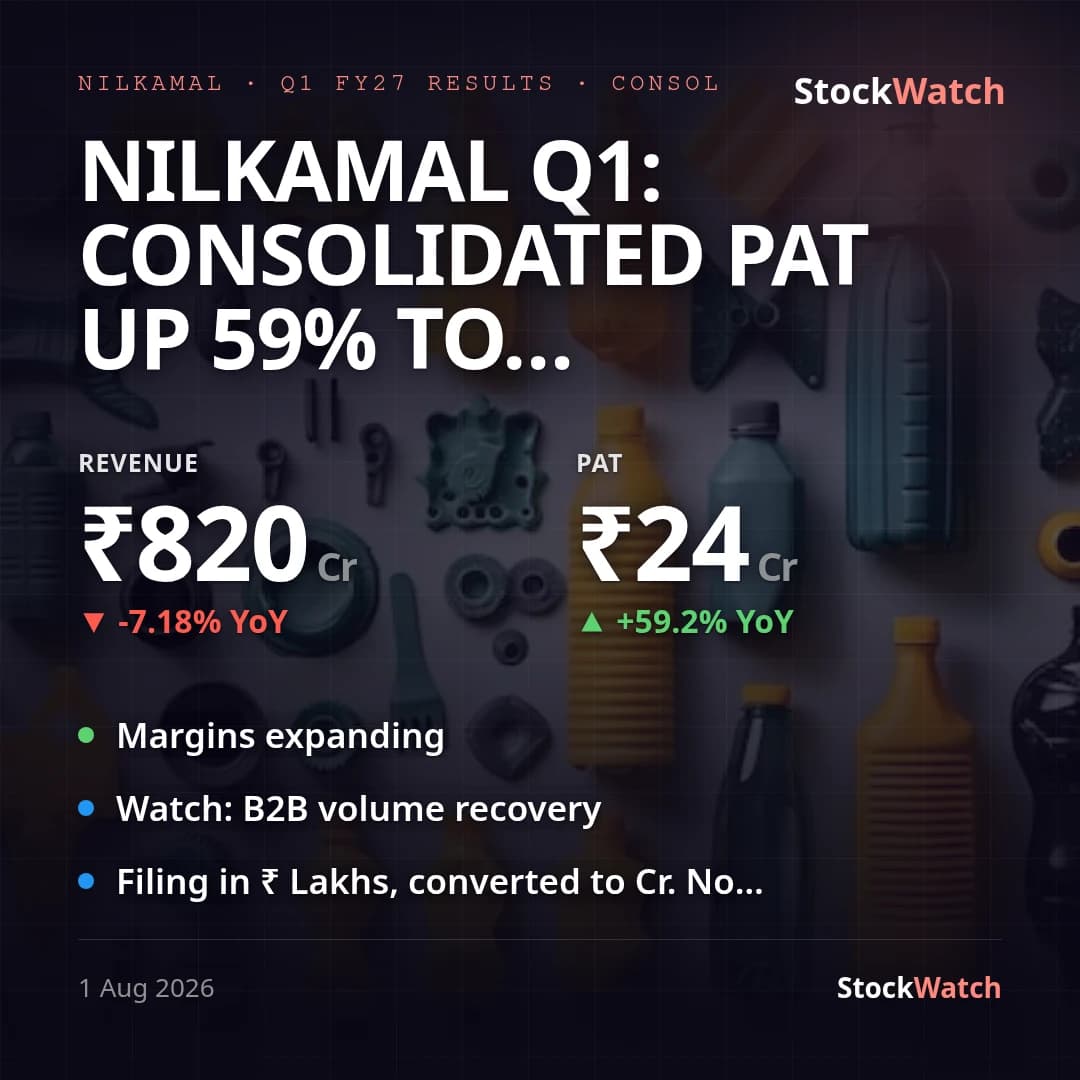
Nilkamal Q1: consolidated PAT up 59% to ₹24 Cr on margin lift as revenue slips 7%
Nilkamal's Q1 FY27 print is a margin-led profit story on a shrinking topline. Consolidated revenue fell 7.2% YoY to ₹819.7 Cr (₹883.1 Cr a year ago), yet consolidated PAT rose 59% to ₹24.4 Cr from ₹15.3 Cr, lifting net margin to 2.98% from 1.73% and operating margin to 9.1% from 6.85%. There were no exceptional items on either side of the comparison, so the profit jump is underlying, not optical. Management attributes the revenue drop to a ~50% surge in key raw-material costs since March 2026 that cut B2B volumes 37%; proactive price hikes and mix optimisation held B2B value degrowth to 10% while improving gross margin.
The swing driver is the Retail & E-commerce segment turning profitable: turnover grew 13% to ₹104 Cr and the segment posted EBIT of ₹1.68 Cr versus a ₹9.5 Cr loss a year ago (e-commerce +22%, stores +6%, network of 100 COCO/FOFO stores). Standalone tells an even sharper version — PBT and PAT both up ~145% to ₹31.4 Cr and ₹23.4 Cr — the divergence from the +59% consolidated figure reflecting a higher consolidated year-ago base; readers should anchor on the consolidated PAT of ₹24.4 Cr as the primary number. Sequentially the result is well below Q4 FY26 (revenue ₹965 Cr, PAT ₹41.7 Cr), but Q4 is seasonally the strongest quarter for furniture/durables, so the QoQ step-down is largely seasonality rather than deterioration.
Nilkamal gives no formal earnings guidance and no brokerage consensus previews exist for this small-cap, so there is no external bar to grade against. Concurrent developments: capex rose to ₹41 Cr (from ₹36 Cr), net borrowing fell sharply to ₹116 Cr from ₹331 Cr a year ago, and CARE reaffirmed CARE AA (Stable)/A1+. The read into next quarter hinges on whether raw-material costs ease enough to revive B2B volumes without giving back the pricing-led margin gains, and whether Retail can hold its newly positive EBIT.