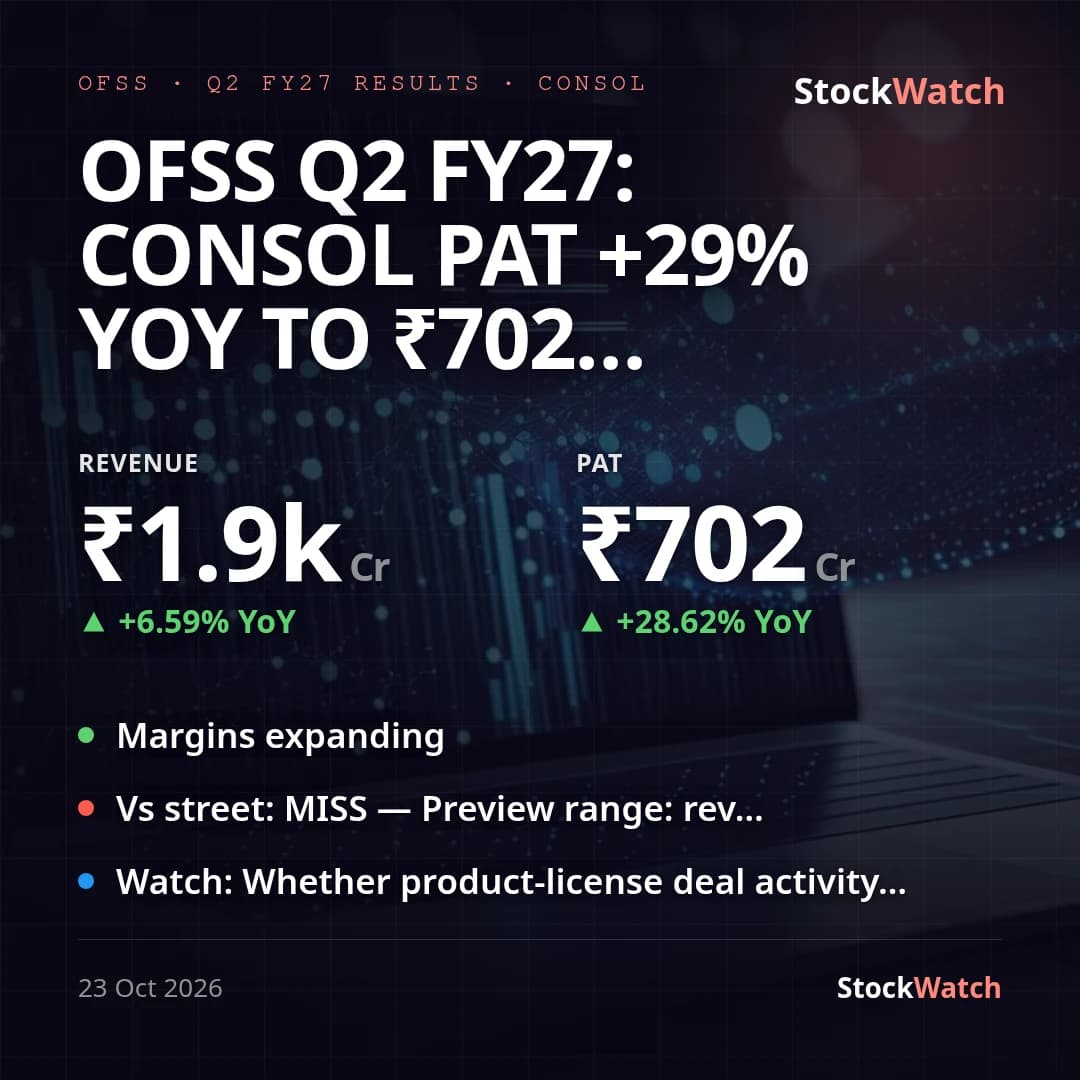
OFSS Q2 FY27: Consol PAT +29% YoY to ₹702 Cr on margin gains; revenue growth cools to 7%
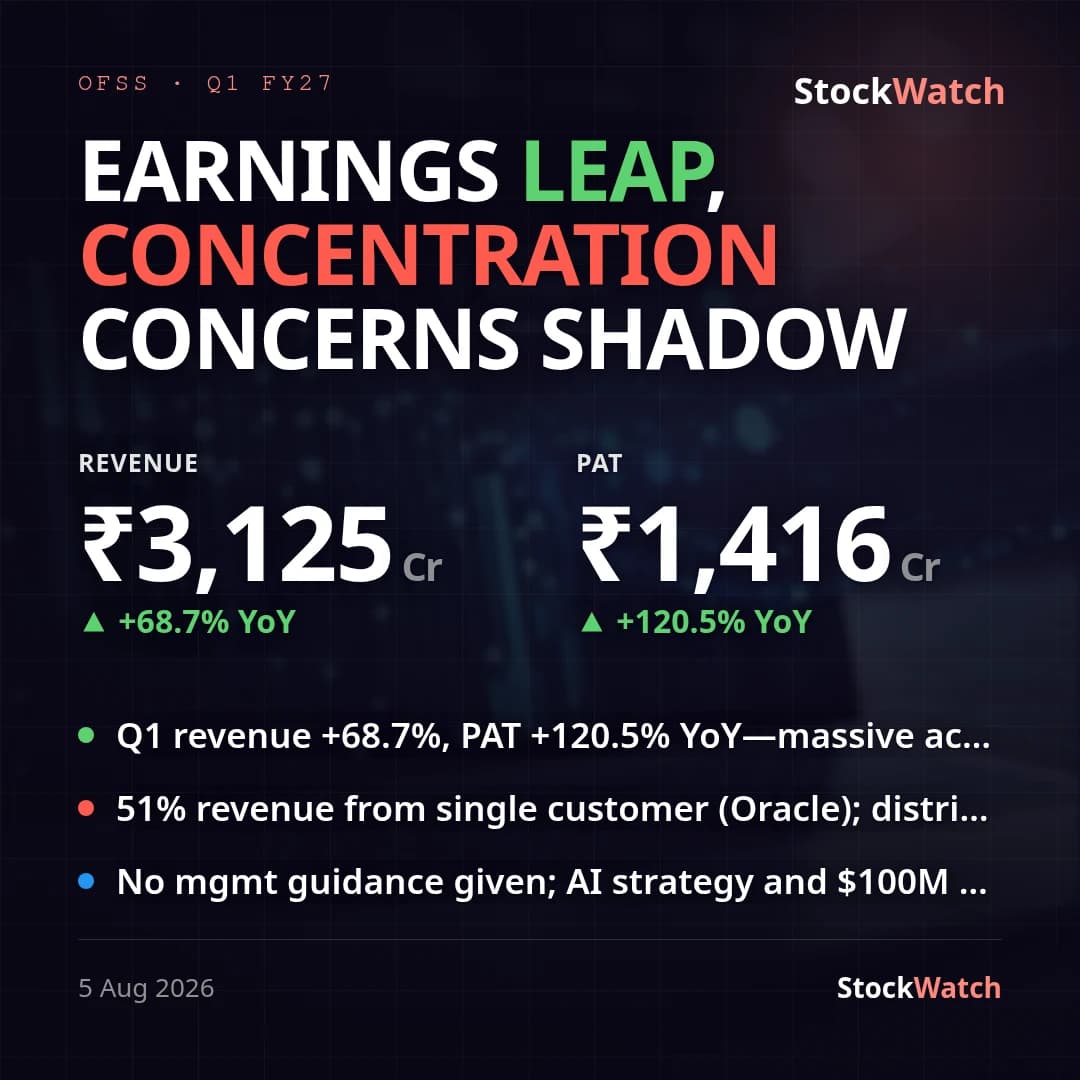
Oracle Financial Services Software's consolidated (primary basis) net profit for Q2 FY27 (quarter ended September 30, 2026) came in at ₹702.4 Cr, up 28.6% year-on-year from ₹546.1 Cr (~33% adjusted for a ₹35.3 Cr one-off severance cost this quarter tied to the CEO transition, detailed below), while consolidated revenue from operations grew a comparatively modest 6.6% YoY to ₹1,906.6 Cr from ₹1,788.8 Cr. Basic EPS was ₹80.66 against ₹62.84 a year ago. Sequentially, both lines fell sharply — revenue down 39.0% and PAT down 50.4% from the June quarter's ₹3,125.2 Cr / ₹1,415.5 Cr — because Q1 FY27 had booked a one-time ₹935.3 Cr license, personnel-transfer and transition-services deal with an existing customer that does not recur in Q2. Standalone PAT was ₹627.5 Cr (EPS ₹72.06) on standalone revenue of ₹1,426.5 Cr; the ~₹75 Cr gap to consolidated PAT reflects subsidiary contributions, and the two bases tell a broadly consistent story this quarter.
Margins expanded year-on-year but compressed sequentially for the same reason. Net profit margin rose to 36.8% from 29.4% a year ago (versus 44.2% in Q1), and the EBITDA-level operating margin improved to 48.6% from 42.2% YoY (versus 60.0% in Q1). By segment, product licenses and related activities — the segment that carried Q1's one-off — generated ₹1,715.8 Cr in Q2, up just 5.7% YoY and down 41.6% QoQ, while the steadier IT solutions and consulting services segment grew 15.2% YoY to ₹190.8 Cr. Employee benefit expenses this quarter also absorbed a ₹35.3 Cr one-off severance cost (versus ₹21.4 Cr the prior quarter), consistent with the CEO transition — Avadhut Ketkar took over as Managing Director and CEO effective July 24, 2026, succeeding Makarand Padalkar, with a new CFO (Manish Bhandari) also appointed July 24 and a non-independent director change effective October 2.
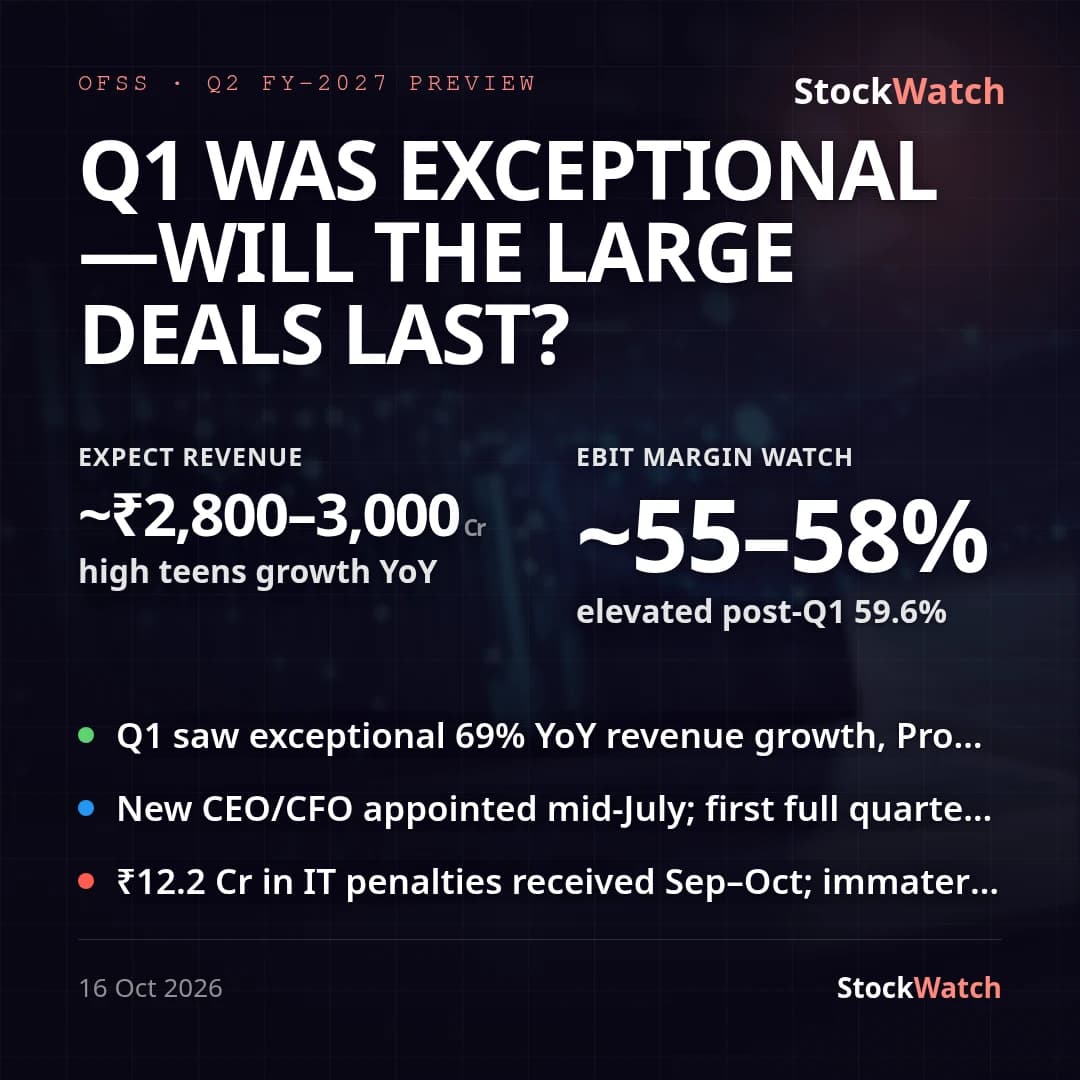
This result falls well short of the on-plan range our pre-result preview set out before the print: revenue of ₹2,800–3,000 Cr, net profit of ₹1,000–1,200 Cr and EBIT margin of 55–58%. Actual revenue of ₹1,906.6 Cr and PAT of ₹702.4 Cr missed the low end of both ranges, and the 48.6% operating margin came in below the expected band too — the preview's central question, "can OFSS sustain the large-deal momentum," is answered here: it did not, reverting instead to a run-rate closer to pre-Q1 levels. The Street's pre-result framing — OFSS forecast to grow 9–10% annually against a ~14% industry growth rate, with consensus target price (~₹10,500) only 1–2% above the then-current price — is reinforced by this quarter's 6.6% YoY revenue growth, which trails even that modest multi-year forecast. Management, per our records, maintains an explicit no-guidance policy, so there is no formal outlook to grade the print against, and no management press-release commentary was available in our records for this filing to cross-check against the numbers. Separately, the company disclosed ₹2.9 Cr and ₹9.3 Cr income-tax penalty orders received in late September 2026 and a director resignation (Nian Nian Yuan) on October 14, 2026 — neither is reflected as an exceptional item in this statement.
Going into H2 FY27, the key markers are whether product-license deal activity reaccelerates from this quarter's normalized ₹1,715.8 Cr run-rate, whether the 48–49% operating margin band holds as the new baseline now that the one-off deal has rolled through, and what commentary the new CEO offers on FY27 trajectory given no formal guidance exists and the Street's structural growth-gap concern versus the broader industry.