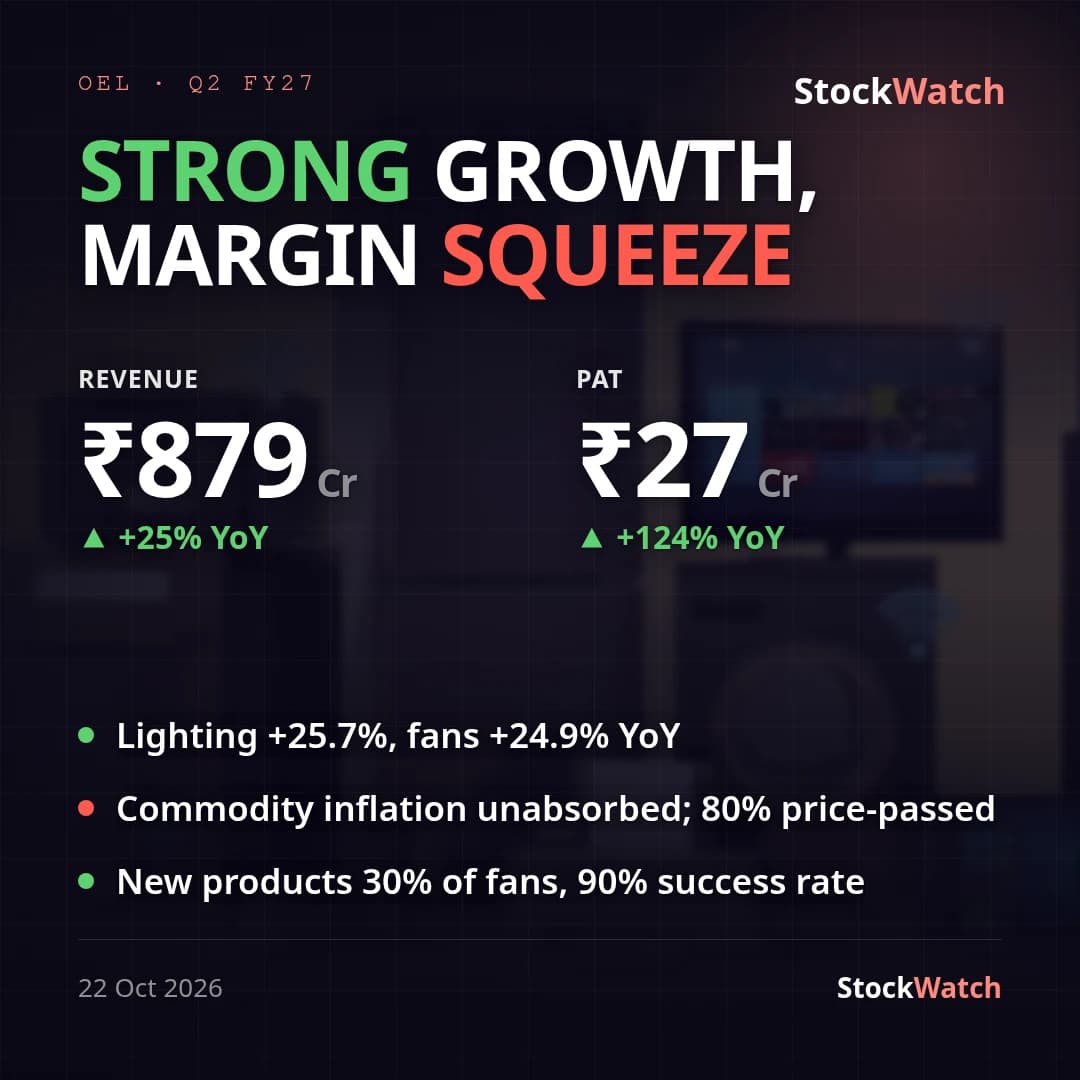
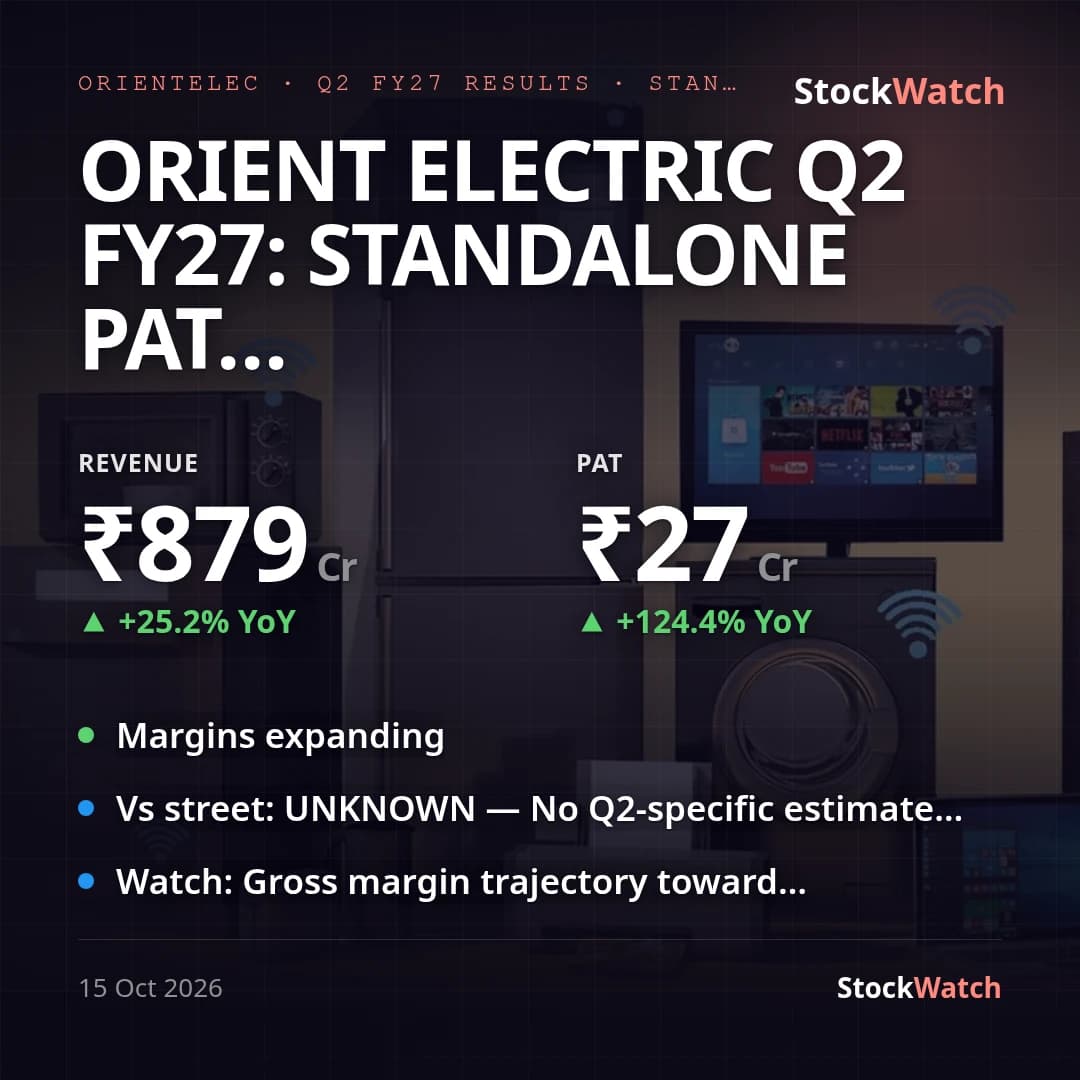
Orient Electric's standalone revenue rose 25.2% YoY to ₹879.34 Cr and net profit more than doubled to ₹27.06 Cr (+124.4% YoY) from ₹12.06 Cr a year ago, with basic EPS up to ₹1.27 from ₹0.57. Both periods are clean of exceptional items, so the YoY growth needs no adjustment. Sequentially, revenue fell 7.4% and PAT 14.1% from Q1 FY27 (₹949.76 Cr / ₹31.49 Cr) — a seasonal pattern typical of the fan/cooling-heavy Electrical Consumer Durables segment, where Q1 (Apr-Jun, peak summer) is structurally the strongest quarter and Q2 (monsoon) softer; this sequential dip should not be read as a deceleration.
The margin story is two-sided. Gross margin compressed to roughly 29.0% from about 31.5% a year ago as raw-material and traded-goods costs rose faster than revenue — consistent with the commodity headwinds management flagged against its 32-34% gross-margin aspiration, and little changed from Q1's ~29.8%, indicating the commodity pressure management said Q2's outlook was conditional on has not visibly eased. Despite that, operating margin (EBITDA/total income, ex other income) expanded to about 6.4% from 5.4% YoY (+~103 bps) — nearly identical to the +102 bps YoY expansion management reported for Q1 — as employee costs (9.5% of revenue vs 10.8% a year ago) and other expenses (13.1% vs 15.3%) fell as a share of sales, i.e. operating leverage below the gross-profit line offset the commodity squeeze above it. Net margin expanded similarly, to 3.08% from 1.71% YoY. Sequentially, operating margin held nearly flat (6.4% vs 6.6% in Q1), so the QoQ profit decline tracks volume, not a margin breakdown.
Both segments grew in the mid-20s YoY: Electrical Consumer Durables revenue rose 24.9% to ₹550.50 Cr with segment EBIT up 43.9% to ₹52.24 Cr; Lighting & Switchgear revenue rose 25.6% to ₹328.84 Cr with EBIT up 19.5% to ₹40.84 Cr — profitability grew faster than revenue in both, reinforcing the operating-leverage read. On management's own prior framing (from the last concall, sourced from our records, not a press release — none has been extracted for this result): a multi-year ₹5,000 Cr revenue target on 14-15% CAGR, a 32-34% gross-margin aspiration described as facing commodity headwinds (Q1 delivered 29.8%), and a reaffirmed path to double-digit EBITDA margin. H1 FY27 revenue growth of 24.3% YoY (₹1,829.10 Cr vs ₹1,471.69 Cr) is running well ahead of that 14-15% CAGR pace; EBITDA-margin expansion this quarter tracks the guided trajectory almost exactly; but the gross-margin aspiration remains unmet and roughly flat sequentially, so the commodity-headwind risk flagged last call is persisting rather than resolving. We found no Q2 FY27-specific Street estimate in a web search — brokerage notes located cover Q1 FY27 (e.g., an ICICI Securities buy call citing a 17% EBITDA beat) and full-year FY27 consensus (~₹3,710 Cr revenue, ~₹6.05 EPS), not a quarter-specific number, so a beat/miss call against Street cannot be made confidently this quarter. Two management appointments during the quarter (a new Chief Marketing Officer and a Head of Internal Audit) point to functional build-out alongside the growth, though neither is a direct financial driver this period.