PG Electroplast Q2 FY27 consolidated: revenue +43% YoY, margins expand to 6.4% OPM
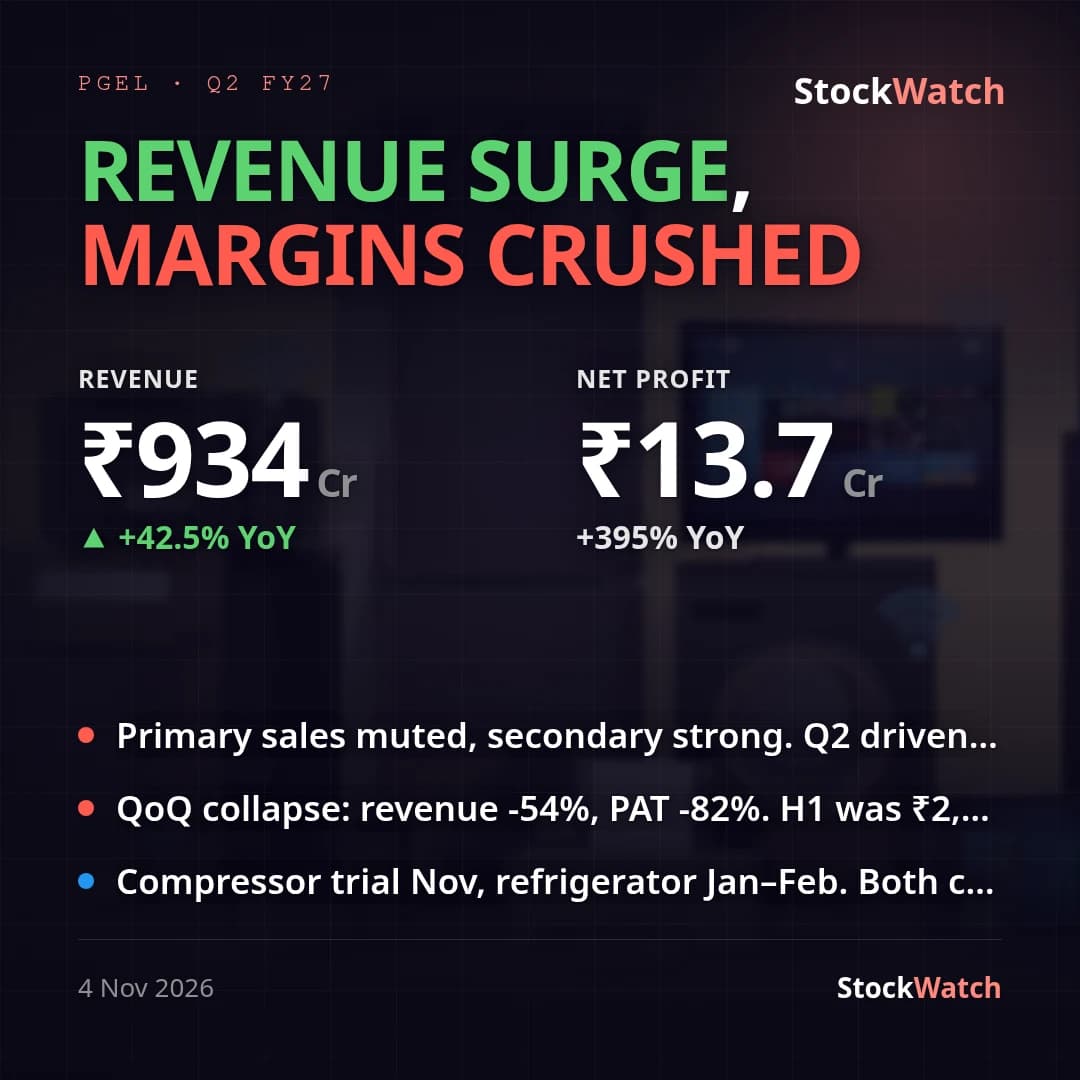
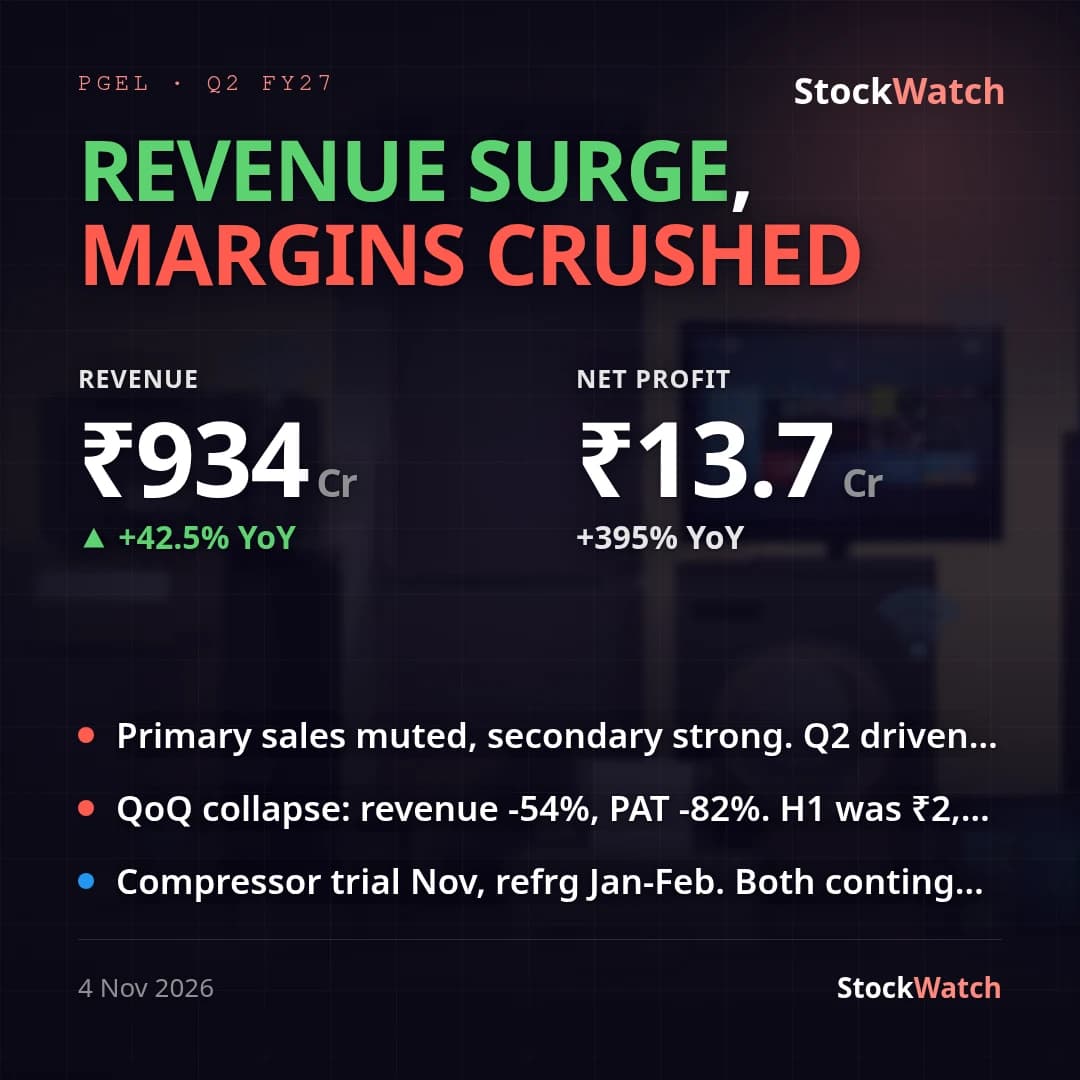
PG Electroplast's consolidated revenue came in at ₹933.88 Cr for Q2 FY27, up 42.5% YoY from ₹655.37 Cr, with consolidated PAT at ₹13.67 Cr versus ₹2.76 Cr a year ago. Sequentially, both lines fell sharply — revenue -54.1% and PAT -82.1% from Q1 FY27 — but this is a seasonal artifact: Q1 (Apr-Jun) is the peak AC-installation season for this EMS/durables business, and the year-ago quarter showed the identical pattern, so the YoY comparison is the one that matters here. On that basis, the quarter is a genuine improvement: operating margin (EBITDA/revenue) expanded to 6.40% from 4.59% a year ago (+181 bps), and net margin to 1.45% from 0.41%. The headline PAT growth of +395% YoY is flattered by an unusually thin year-ago base (NPM then was near breakeven at 0.41%), so the rupee improvement — margin expansion plus volume growth — is the more meaningful read than the percentage.
A notable wrinkle: standalone (parent-only) PAT of ₹25.86 Cr this quarter actually exceeds the consolidated PAT of ₹13.67 Cr, despite consolidated revenue being nearly double standalone revenue. The auditor's limited review report discloses that one unreviewed subsidiary posted a net loss after tax (before consolidation adjustments) of ₹16.83 Cr for the quarter, which is the main reason consolidation pulls group profit below the parent's own number. This is worth tracking rather than ignoring, since it is currently a meaningful drag on group profitability.
Against management's own framing from the Q1 FY27 call, the quarter is broadly on-track rather than a beat or a miss: the stated FY27 target was 8% operating margin (7.3% ex-PLI at the time), with downstream margin improvement guided to begin only from December as commodity-cost pass-through kicks in, and compressor mass production starting Dec-Jan. Q2's 6.40% OPM is below both the 7.3% baseline and the 8% target, but the specific margin catalysts management flagged hadn't started during the Jul-Sep quarter, so the shortfall is consistent with the stated timeline rather than a departure from it. The 20%+ full-year volume growth guidance cannot be checked from this filing, which discloses no volume data. No analyst estimate specific to this quarter could be found; the only available reference point is a full-year FY27 consensus (~₹6,660 Cr revenue, ~₹289 Cr adjusted PAT per one brokerage), which implies a materially stronger H2 than the ₹2,967.83 Cr / ₹89.88 Cr H1 run-rate — consistent with management's own guidance that the margin and volume catalysts load into the back half. Separately, BSR & Co. LLP reviewed this quarter as the company's new statutory auditor, succeeding the predecessor that signed off on FY26 and the preceding quarters; this is a governance change coincident with, but not a driver of, this quarter's numbers.
What this sets up: the next two quarters are the actual test of the FY27 margin and volume guidance, given management tied the improvement explicitly to December onward (commodity pass-through) and Q4 (refrigerator commercialisation). Q2's YoY margin expansion is a reasonable leading indicator, but the OPM gap to the 8% target (160 bps) and the subsidiary loss both remain open items into H2.