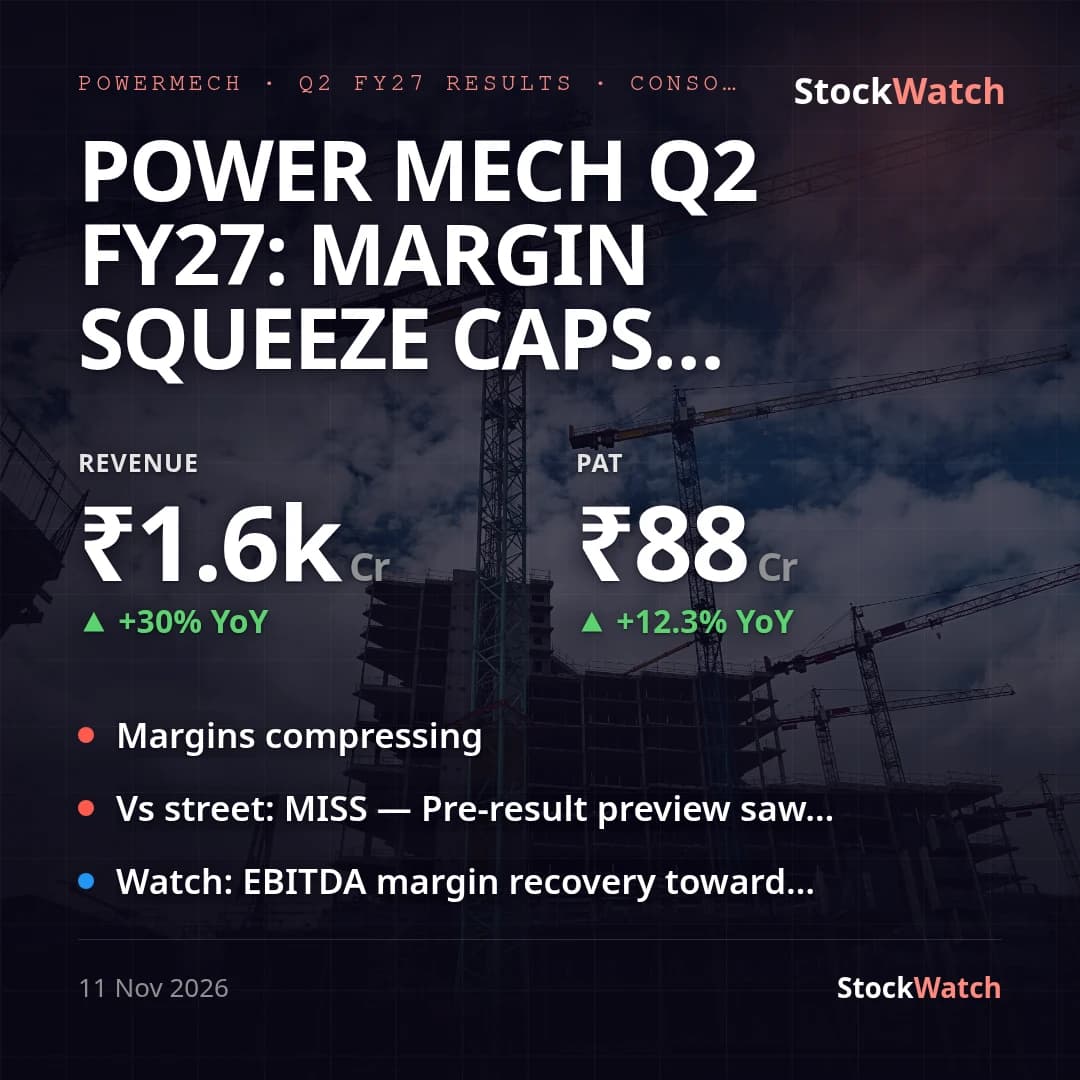
Power Mech Q2 FY27: margin squeeze caps PAT growth at 12% YoY despite 30% revenue surge
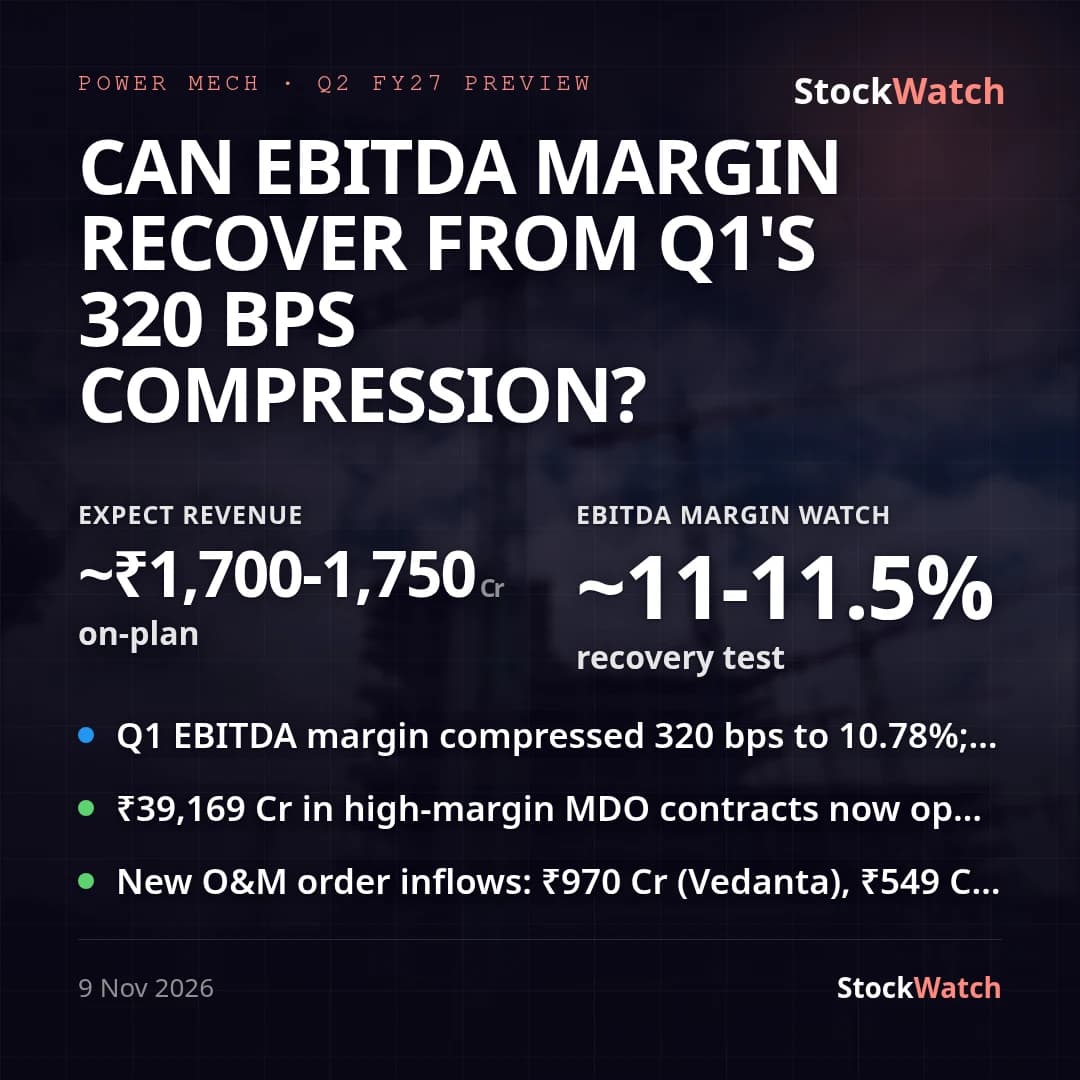
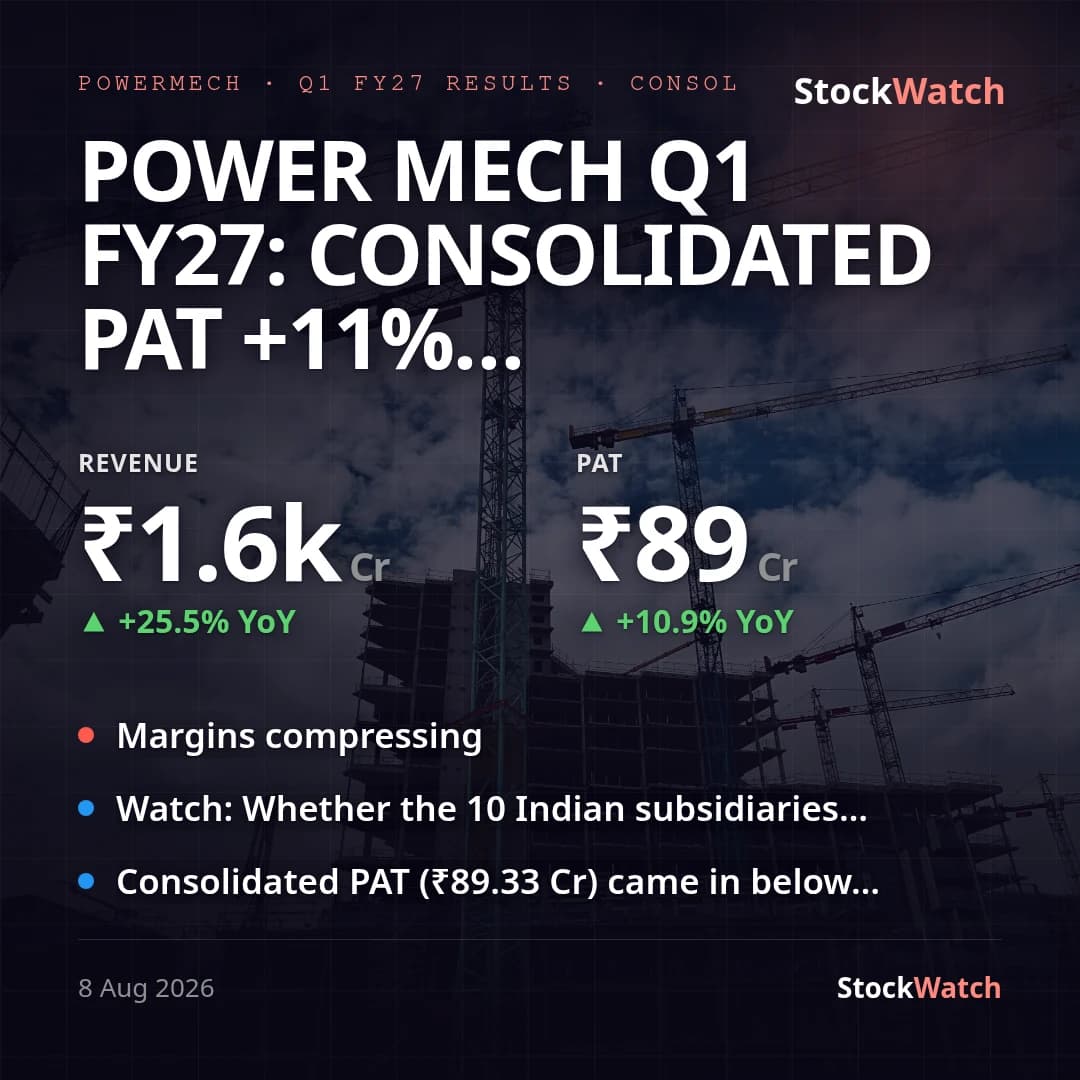
Power Mech's consolidated Q2 FY27 print came in below the bar the Street and our own pre-result preview had set. Revenue of ₹1,609.34 Cr (+30.0% YoY, -0.9% QoQ) missed the previewed ₹1,700-1,750 Cr range, and consolidated PAT of ₹87.75 Cr (+12.3% YoY, -1.8% QoQ) fell short of the previewed ₹95-105 Cr — both reported with no exceptional items on either side, so the shortfall is operational, not accounting. The YoY read is the one that matters: revenue growth of 30% badly outran profit growth of 12%, with NPM compressing to 5.43% from 6.25% a year ago. OPM also compressed YoY, to 11.11% from 11.88%, even though it did recover sequentially from Q1's 10.30% — progress toward, but still ~140 bps short of, management's stated 12.5% FY27 EBITDA margin target. The squeeze sits on costs running ahead of revenue: employee benefit expense rose 36% YoY to ₹239.90 Cr (MDO business ramp-up) and contract execution costs rose 37% YoY to ₹915.43 Cr, both outpacing the 30% topline growth, while depreciation jumped 43% YoY to ₹24.92 Cr and finance costs rose 18% YoY to ₹33.51 Cr as capital work-in-progress nearly tripled to ₹575.98 Cr (from ₹171.64 Cr at FY26-end) and short-term borrowings rose to ₹1,021.50 Cr — capex and funding costs for the MDO/BOP build-out are landing before the associated revenue and margin benefit shows up.
Against management's own FY27 guidance (21% revenue growth, ₹12,000 Cr order inflow target, 12.5% EBITDA margin), the half-year is actually tracking ahead on growth — H1 FY27 consolidated revenue is up 27.7% YoY — but the margin target remains unmet this quarter, so the read is mixed: revenue guidance on track to beat, margin guidance still a work in progress. On order inflows, the ₹549.37 Cr Adani Moxie Power O&M win booked within the quarter (Sep 29) sits inside the ₹400-600 Cr range we flagged pre-result as the watch item, suggesting the order engine is executing to plan even as reported margins lag. Subsequent-quarter developments — the ₹327.35 Cr Vedanta Aluminium order (Oct 19), the ~USD 52.1 Mn Saudi Arabia contract via Power Mech Arabia (Nov), and the ₹469 Cr guarantee extended for subsidiary KTMPL (Oct 15) — fall after the Sep 30 cutoff and don't affect this print, but the KTMPL guarantee is the capital-structure watch item we'd flagged materializing, and bears monitoring given rising consolidated borrowings. Power Mech did not issue an accompanying management press release with this filing, so there is no additional management commentary to reconcile against the numbers this quarter.
Taken together, this is a quarter where the headline YoY PAT growth (+12%) looks respectable only in isolation; set against 30% revenue growth, a still-short-of-target EBITDA margin, and a miss versus both Street and our own pre-result expectations on revenue and profit, the underlying signal is a company still mid-way through converting a large capex and order book build-out into margin, not yet there.