Prasol Chemicals: maiden post-IPO print — PAT +151% YoY as margins expand sharply
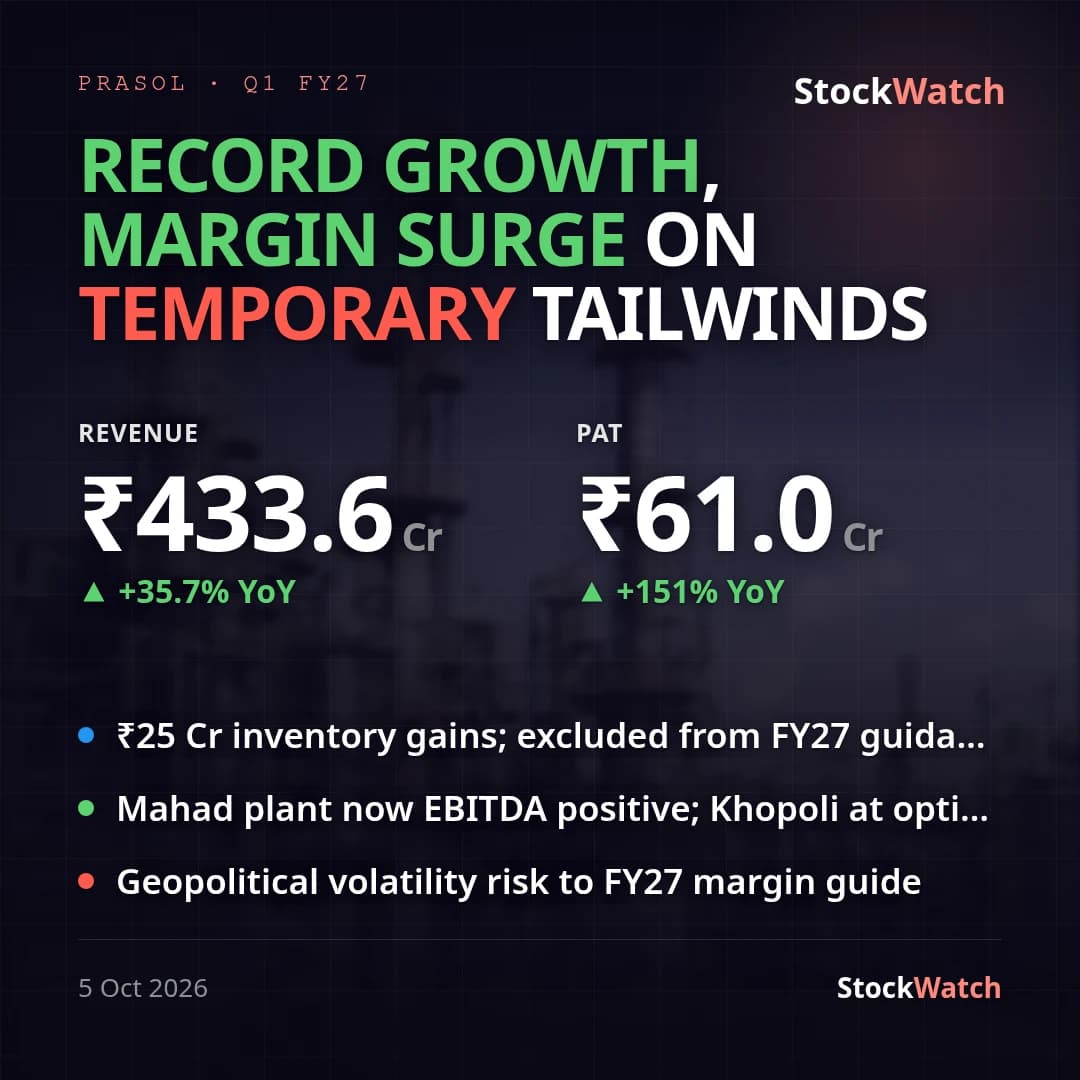
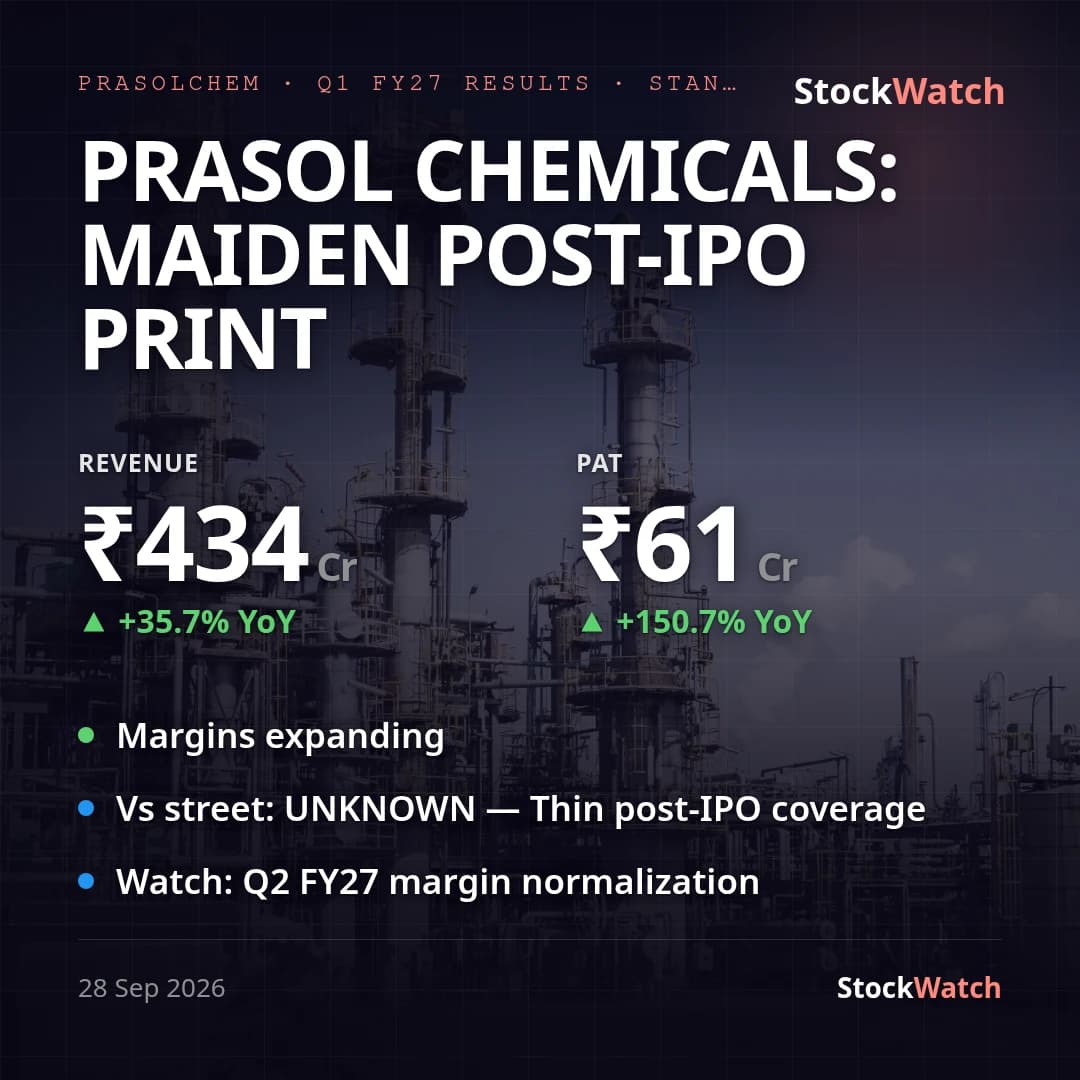
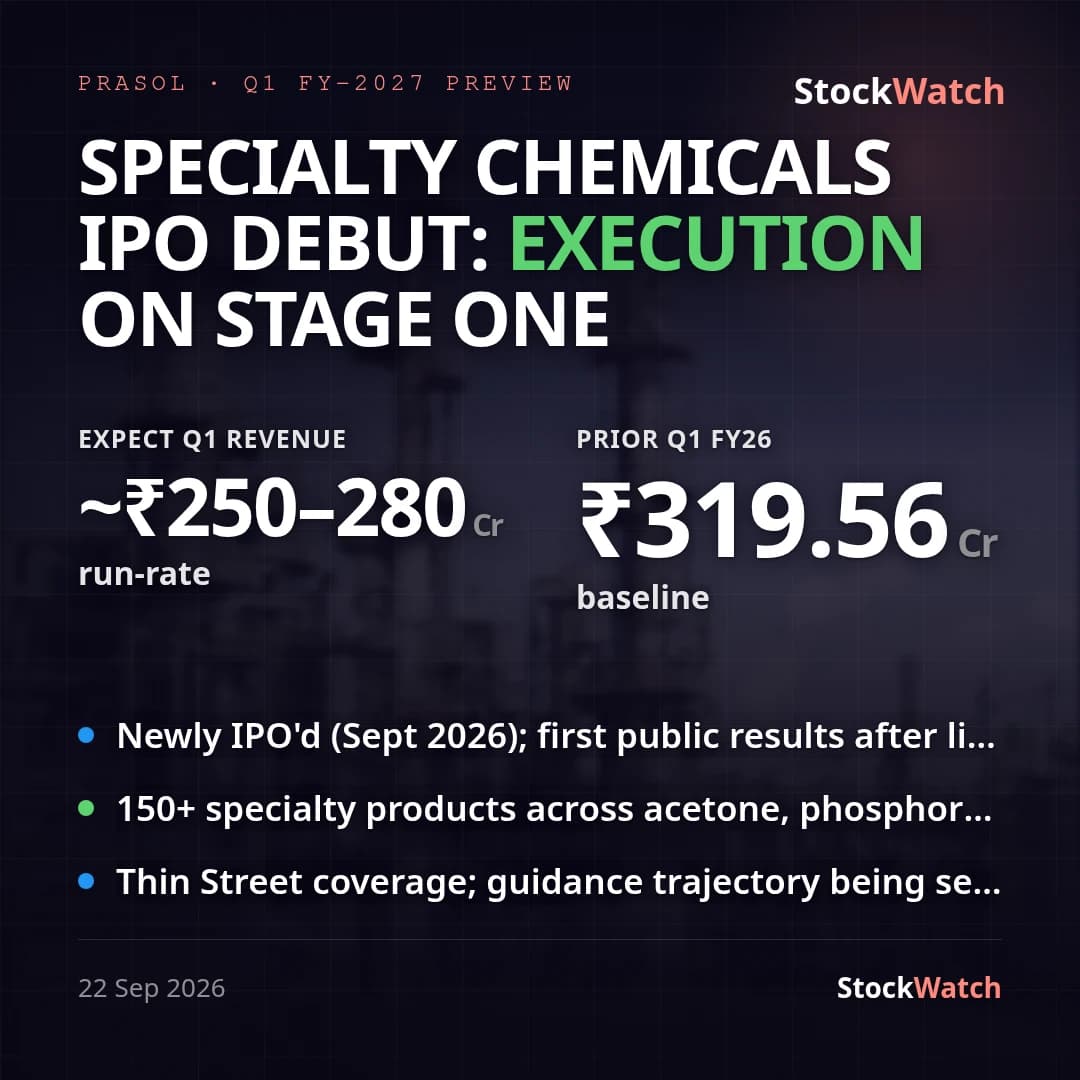
Prasol Chemicals' first results since its September 16, 2026 listing show standalone revenue from operations of ₹433.6 Cr for Q1 FY27, up 35.7% year-on-year from ₹319.6 Cr and 29.5% sequentially from ₹334.9 Cr. Standalone PAT more than doubled YoY to ₹61.0 Cr (+150.7% from ₹24.3 Cr) and rose 207.3% QoQ from ₹19.9 Cr, with EPS of ₹10.52 against ₹4.20 a year ago. The print runs well ahead of the on-plan revenue range of ₹250–280 Cr and the 8–9% volume growth guidance flagged in our pre-result preview — a clear beat on both counts, though the company has published no formal quarterly guidance in the filing itself. Street coverage remains thin post-listing; no formal Q1 FY27 consensus estimates turned up in a search, consistent with the neutral, low-coverage posture flagged pre-result, so this print becomes the first real anchor for analyst models.
Margin expansion is the bigger story than topline growth: net profit margin rose to 14.1% from 7.6% YoY (5.9% QoQ), and PBT margin to 19.3% from 10.3% YoY. Total expenses fell to 81.1% of revenue from operations from 90.0% a year ago. A meaningful share of that improvement traces to the 'changes in inventories' line, which swung from a ₹6.4 Cr drawdown a year ago to a ₹39.2 Cr net build this quarter — a roughly ₹45 Cr swing that mechanically reduces reported cost of goods sold when finished-goods/WIP stock is added rather than sold. Purchases of stock-in-trade also rose faster than revenue (20.1% of revenue vs 14.6% YoY), while employee costs and other expenses held broadly flat as a share of sales. Underlying margin quality should be read with the inventory build in mind rather than taken purely as pricing or cost-efficiency gains.
The Board that approved these results also accepted the retirement of Dr. Chitra Vaidya, Vice-President – R&D (effective September 30, 2026), and closed the trading window ahead of Q2/H1 FY27 results — both routine disclosures alongside the results filing. Separately, the company reported an insider-trading violation on September 24, 2026, a governance flag worth tracking for resolution in coming filings, though it carries no read-through to this quarter's P&L. Management has issued no separate press release or commentary with this filing, so there is no company framing to reconcile against the numbers.
Going into Q2 FY27, the key questions are whether the inventory-aided margin holds up once stock normalizes, and how EPS reads on the enlarged post-IPO share base after the September fresh issue of ~11.8 lakh shares. With the stock down ~7.8% from its ₹676 IPO price to ₹623.25 pre-result and only nascent analyst coverage, this result — a clear beat on the company's own on-plan revenue range and pre-IPO growth guidance — is likely to be the first data point consensus estimates get built around.